Fintech software development services for payments, lending and digital banking

THE TISA provides fintech software development services for startups, lenders, payment companies and financial institutions. We build fintech apps, banking platforms, payment systems, digital wallets and AI fraud detection, from a first version to production.

  • CampusFlow — THE TISACampusFlow
  • EZSKU — THE TISAEZSKU
  • Group Hotel Index — THE TISAGroup Hotel Index
  • LockYantra — THE TISALockYantra
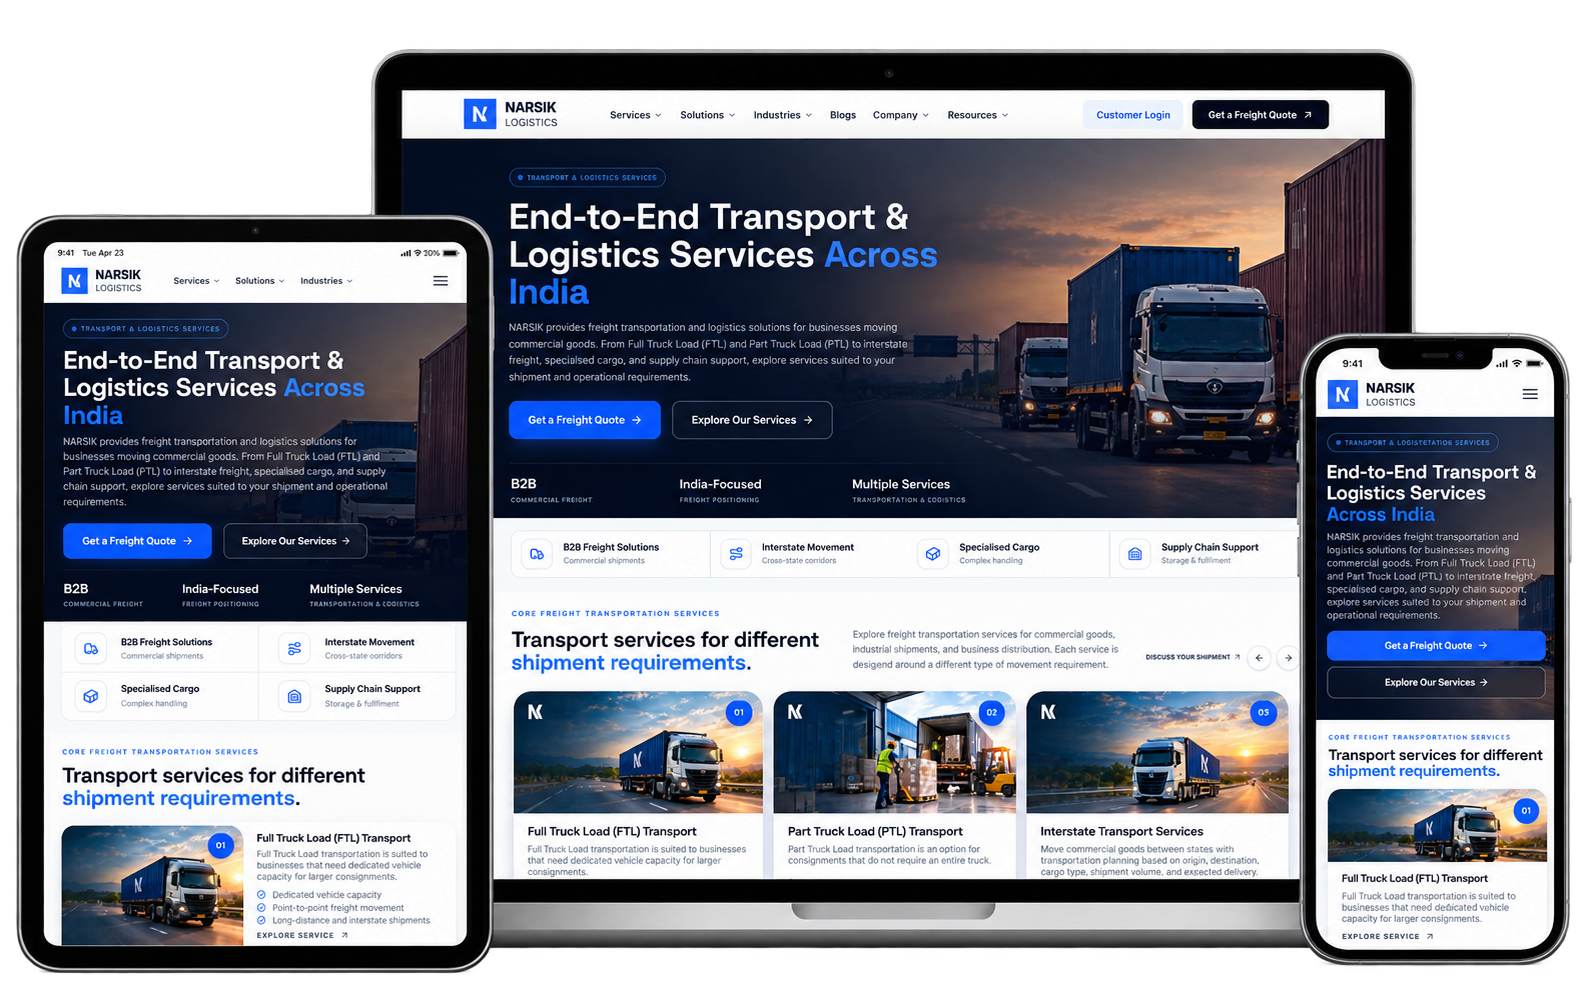
  • Narsik Logistics — THE TISANarsik Logistics
  • OpsPilot — THE TISAOpsPilot
  • Ratiwal — THE TISARatiwal
  • Speakify — THE TISASpeakify
  • 50+Team Members
  • 100+Projects Delivered
  • 40+Happy Clients
  • 12+Industries Served
  • 30+Technologies
  • 10+Countries Reached
  • 20+Technical Specialists
  • 35+AI Projects
  • 25+Products Launched
  • 20Published Case Studies

What are the fintech software development services we build?

Fintech software development services cover the design, engineering, compliance and support of software that moves, stores or manages money. That includes mobile banking apps, payment gateways, digital wallets, lending platforms, trading apps and the back-office systems behind them.

Fintech software differs from ordinary software in three ways. It must keep balances exact, meet financial regulations such as PCI DSS and KYC/AML, and connect safely to banks, card networks and payment rails. A fintech development company handles all three alongside the product itself.

What are fintech software development services

Comprehensive fintech software
development services for every layer

We cover every layer of a financial product, from the app and the ledger to the rails, the compliance workflows and the support after launch. Start with one service or hand us the whole platform. Each topic below is summarised here, and a dedicated page will cover it in depth when that page is live.

Fintech App Development

iOS, Android and cross-platform apps for banking, payments, budgeting and investing. Biometric login, card controls, instant transfers and statements, designed for trust on a small screen, with the money path explained before a user confirms it.

Explore Service

Banking Software and Website Development

Online banking portals, customer onboarding websites, internal banking dashboards and integrations with core banking systems for banks, credit unions and digital lenders, connected to the core system you already run today.

Explore Service

Payment Software and Gateway Development

Payment processing, payouts, recurring billing, multi-currency checkout and merchant dashboards built on Stripe, Adyen and direct bank rails, with retries, webhooks and a daily reconciliation against the product ledger.

Explore Service

Digital Wallet Development

P2P transfers, QR payments, stored balances, virtual cards and rewards in a wallet your users trust with their money, with limits, device binding and a ledger entry for every movement.

Explore Service

Lending Software Development

Loan origination, underwriting workflows, repayment schedules, collections and borrower portals for consumer, SMB, BNPL and P2P lending, with a person still approving every decision the rules do not cover.

Explore Service

Neobank and Banking-as-a-Service Apps

Accounts, debit cards and transfers launched on a sponsor bank through a banking-as-a-service partner, without building a bank from scratch. Your partner holds the licence. We build the software that sits on it.

Explore Service

Investment and Trading Platform Development

Portfolio tracking, brokerage integrations, real-time market data and order flows for retail and advisory platforms, with the record-keeping an investment product has to keep for later review.

Explore Service

AI Fraud Detection and Risk Scoring

Real-time transaction scoring, account-takeover detection and AML alert triage, with a person reviewing every case where money or a compliance decision is at stake.

Explore Service

Fintech API Integration

Reliable connections to banks, processors, KYC vendors, open banking APIs and accounting systems, with retries, monitoring and a daily reconciliation against the ledger.

Explore Service

Insurtech Software

Quote engines, policy administration, claims workflows and premium payments for insurers and MGAs, from the first quote through a claim and the premium payment that follows it.

Explore Service

RegTech and Compliance Automation

KYC and KYB onboarding, sanctions screening, transaction monitoring rules, case management and regulatory reporting, so those checks live in the product rather than in a separate spreadsheet.

Explore Service

Blockchain and Crypto Development

Crypto wallets, on-ramp and off-ramp integrations, tokenisation and blockchain-based settlement through regulated custody partners, rather than an unregulated wallet you would have to hold on your own servers.

Explore Service

Innovative fintech development solutions to
empower your business

Each solution is written out in full so the page can be read and indexed without opening a hidden panel. The six below cover a first release, a scaled product, a legacy core, an embedded feature, a multi-country launch and a build that stays with one team.

Laptop, phone, card, and security tools for fintech solutions
  1. 01

    Advanced digital wallet solutions

    Multi-currency wallets with instant P2P transfers, QR and NFC payments, bill pay, virtual cards and rewards. We add spending limits, device binding and fraud checks so convenience never weakens security.

  2. 02

    Secure money transfer solutions

    Domestic and cross-border transfer apps with FX quotes, recipient management, compliance screening and real-time status tracking. We support ACH, RTP and FedNow in the US, and SEPA and SWIFT for UK and EU corridors.

  3. 03

    Mobile banking solutions

    Account opening with identity verification, balances, transfers, card controls, statements, alerts and in-app support. Built for banks, credit unions and neobanks that run on a banking-as-a-service partner rather than a core built from scratch.

  4. 04

    Investment and trading platform development

    Brokerage-connected apps with portfolio views, watchlists, real-time quotes, order placement, fractional shares and the record-keeping investment products require, so an order and the disclosure around it can be reconstructed later.

  5. 05

    Custom money lending solutions

    Digital loan applications, automated underwriting rules, e-signatures, disbursement, repayment schedules, reminders and collections dashboards, with a person still approving the loan decisions the written rules still do not cover alone.

  6. 06

    Mobile POS system development

    Card-present payments on phones and tablets with tap to pay, receipts, inventory sync and settlement reports for merchants, reconciled against the processor so a day's takings match what the ledger recorded.

Build an app like PayPal, Venmo or Chime,
custom-built and fully yours

Many founders start with a reference: they want something like Venmo, but for their market. We build that as custom software you own, not a resold clone script. You get the proven experience of a known product type, plus the features, compliance and brand that make yours different.

These names describe the product type only. This page does not use those brands' logos or visual identity, and the mockups are references for the kind of product, not a claim that we built those apps.

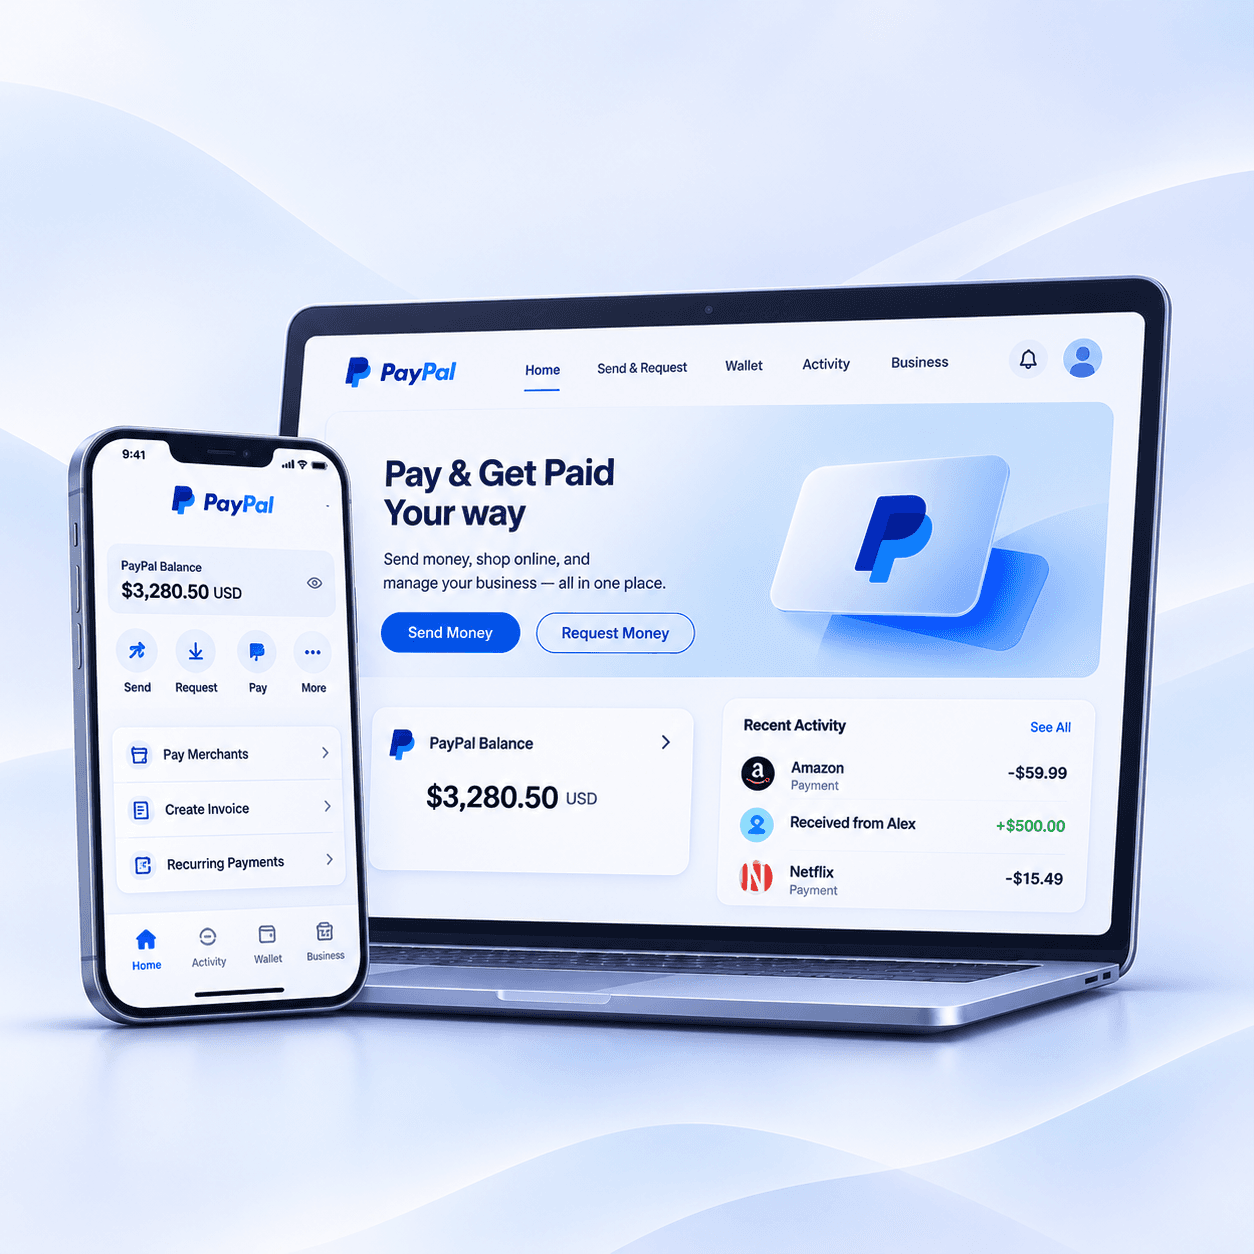
App like PayPal

A comprehensive digital payment platform that enables users to send and receive money, make secure online payments, manage transactions and pay merchants across multiple channels. Includes merchant checkout integrations, recurring payments, invoicing, digital wallets, transaction history, refunds, buyer and seller protection, fraud detection, payment verification, multi-currency support and real-time transaction notifications. Businesses can also access payment dashboards, reporting tools, settlement management and APIs to integrate payment processing into websites and mobile applications.

Mockup of a payments app with checkout, transfers, and merchant tools

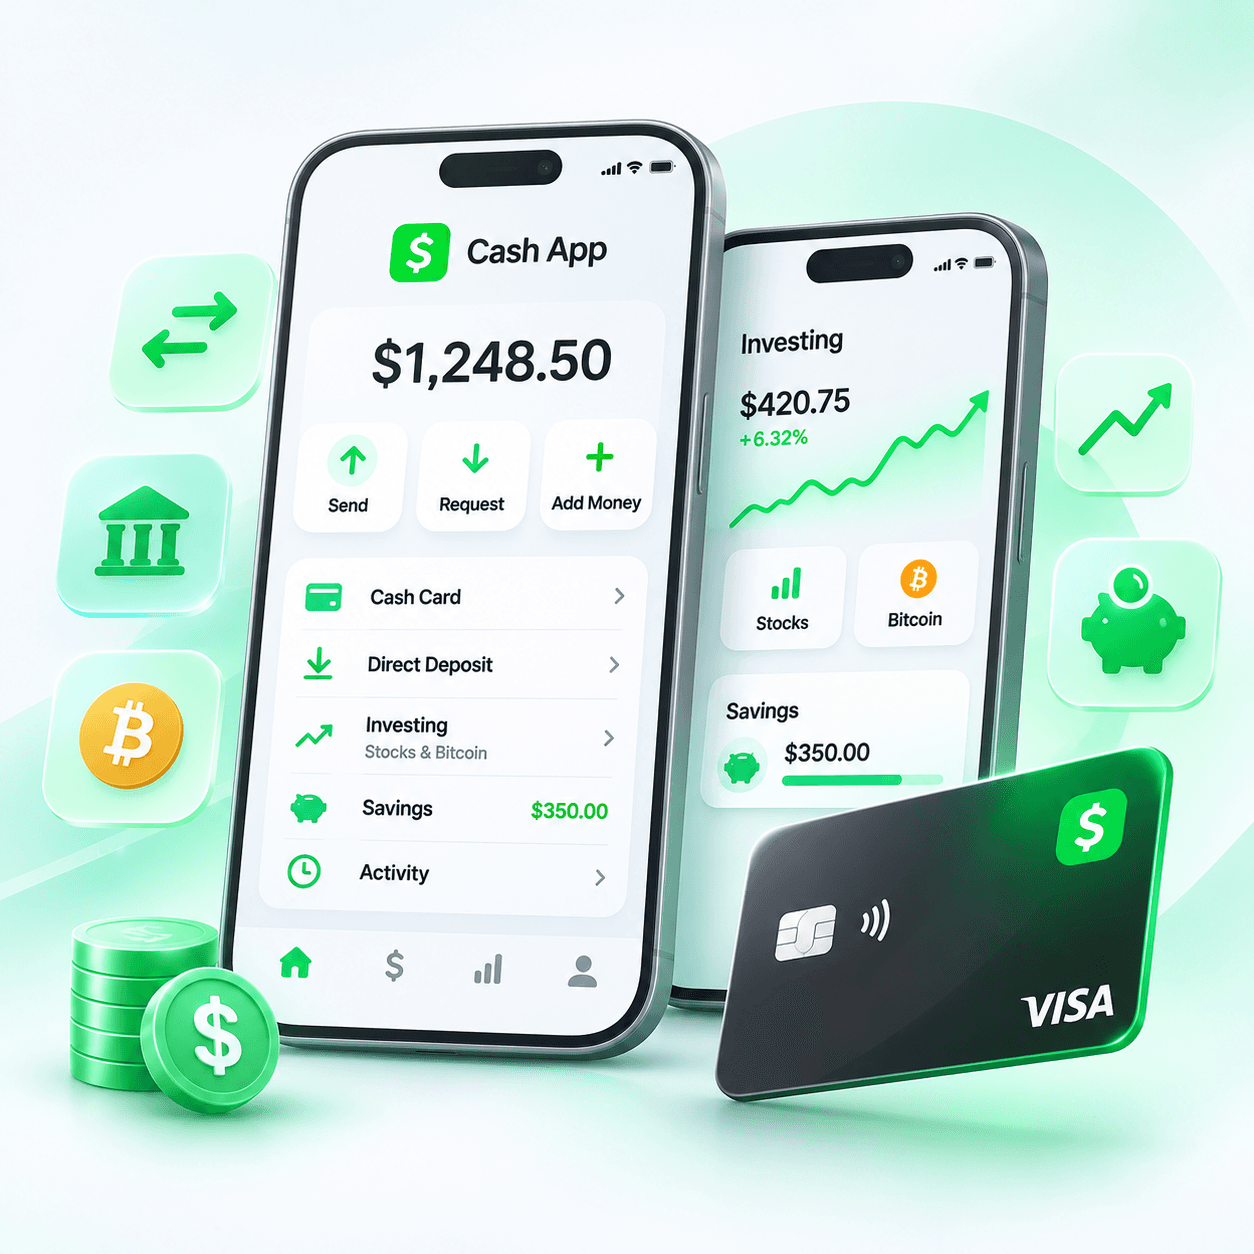
App like Cash App

A modern peer-to-peer payment application that allows users to instantly send, receive and request money through a simple and intuitive mobile interface. Includes digital wallets, linked bank accounts, debit cards, direct deposits, transaction tracking, savings features and simple investment options such as stocks and Bitcoin. Additional capabilities can include customizable payment profiles, QR code payments, instant cash-outs, recurring transfers, spending insights, card controls, account notifications and identity verification to provide a convenient all-in-one financial experience.

Mockup of a peer-to-peer payment app with a wallet, card, savings, and investing

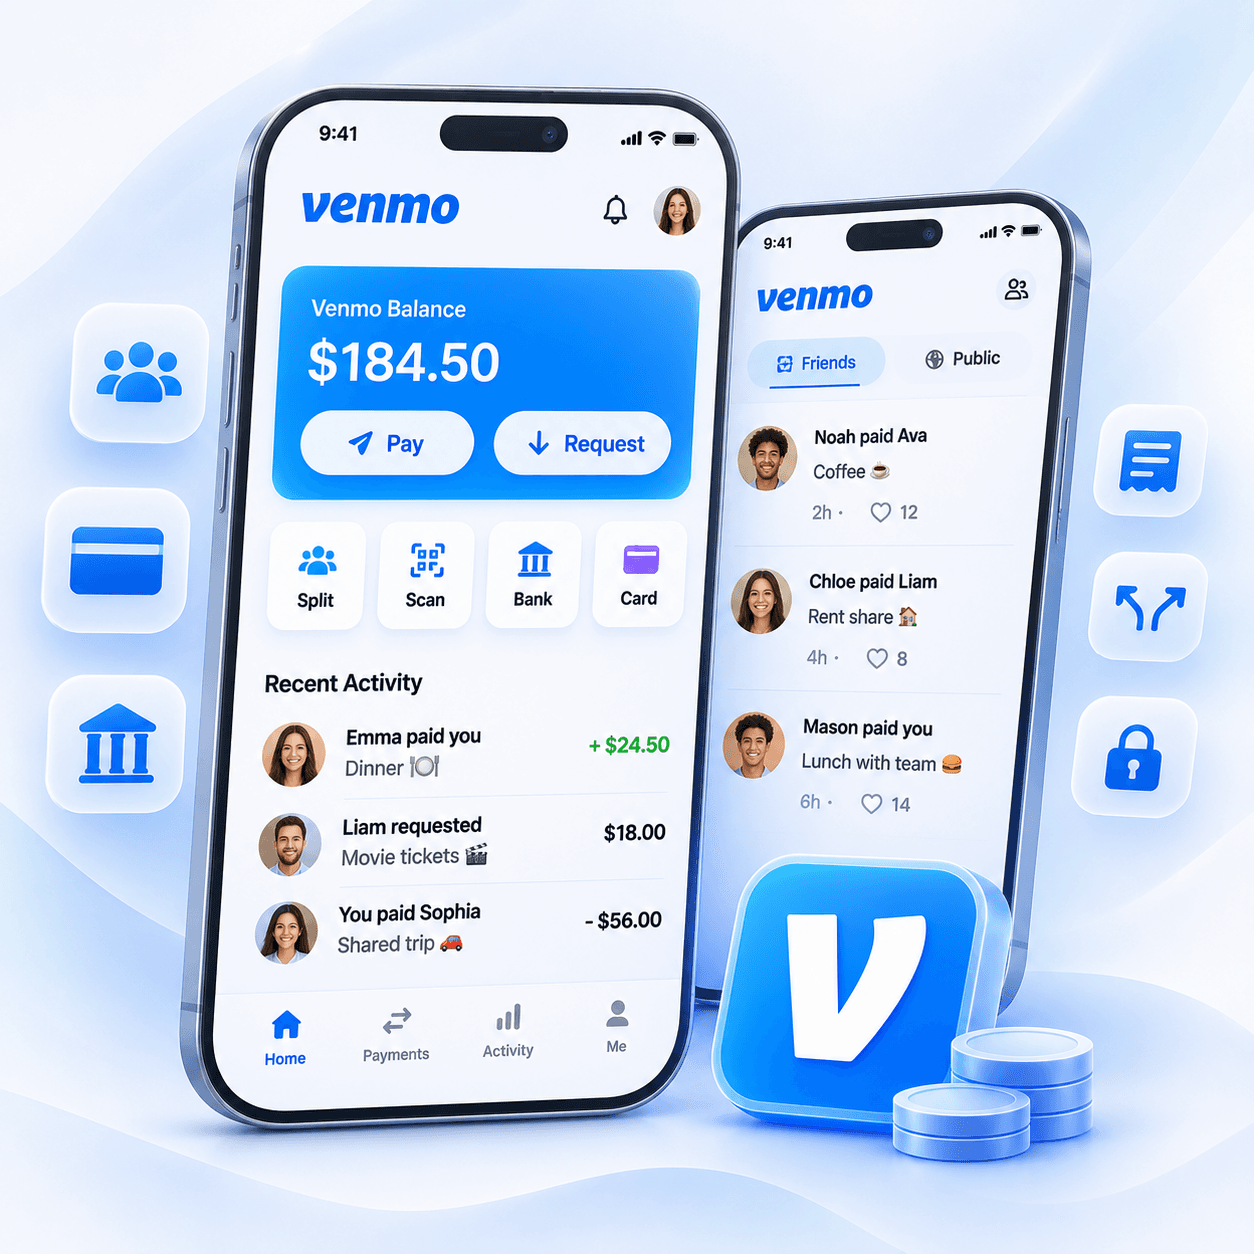
App like Venmo

A social payment application designed for seamless money transfers between friends, family and contacts, combining everyday payments with a familiar social experience. Features include contact synchronization, payment requests, bill splitting, shared expenses, customizable transaction notes, social activity feeds, privacy settings, instant transfers and linked bank accounts or debit cards. The platform can also support group payments, shared expense tracking, payment reminders, emoji reactions, transaction search, user profiles, customizable visibility controls and secure payment authentication for effortless social money management.

Mockup of a social payments app with requests, bill splitting, and an activity feed

App like Robinhood

A mobile-first investment and stock trading platform that makes financial markets accessible to everyday investors through an intuitive trading experience. Includes commission-free style trading, fractional shares, stocks, ETFs, watchlists, interactive charts, real-time market data, portfolio tracking, price alerts, investment insights and secure brokerage integrations. Advanced capabilities can include recurring investments, market news, personalized dashboards, order management, dividend tracking, investment performance analytics, educational resources and account funding options. Brokerage infrastructure and regulatory compliance can be handled through appropriately licensed partners.

Mockup of an investing app with charts, watchlists, and a portfolio

App like Coinbase

A cryptocurrency trading and digital asset management platform that allows users to buy, sell, convert and securely store cryptocurrencies through an easy-to-use interface. Includes crypto wallets, portfolio tracking, live market prices, price alerts, recurring purchases, transaction history, educational resources, staking where permitted and integrations with regulated custody and payment partners. Additional features can include multi-asset portfolio views, blockchain transaction tracking, supported network transfers, advanced trading tools, identity verification, withdrawal controls, security alerts and real-time market insights to help users manage their digital assets.

Mockup of a crypto app with a wallet, prices, and buy and sell actions

App like Chime

A mobile-first digital banking application offering convenient everyday banking without the traditional branch experience. Includes checking and savings accounts through sponsor bank partnerships, early direct deposit where supported, fee-free spending options, virtual and physical debit cards, automatic savings, spending insights, transaction notifications and account management. The platform can also provide mobile check deposits, peer-to-peer transfers, recurring bill payments, card locking, balance alerts, savings goals, automated round-ups, account statements and personalized financial insights. Secure onboarding, identity verification and banking integrations help deliver a seamless digital banking experience.

Mockup of a digital banking app with checking, savings, and a debit card

App like Revolut

A global digital banking and financial management platform designed for travellers, professionals and international users who need flexible financial services across borders. Includes multi-currency accounts, international money transfers, real-time foreign exchange conversions, virtual and physical cards, travel spending, budgeting tools, transaction analytics, spending limits and international payment capabilities. Additional features can include currency exchange alerts, shared accounts, recurring transfers, expense categorization, travel notifications, card security controls, subscription management and detailed spending reports. The platform can integrate with banking, payment and card-issuing partners to support cross-border financial operations.

Mockup of a multi-currency banking app with transfers, cards, and spending tools

App like LendingClub

A digital lending and personal finance marketplace connecting eligible borrowers with lending institutions and investors through a streamlined online platform. Includes online loan applications, borrower verification, credit scoring, risk assessment, loan comparison, interest rate calculations, investor dashboards, repayment schedules, automated collections, loan servicing and payment tracking. The system can also support loan eligibility checks, document uploads, automated underwriting workflows, borrower profiles, repayment reminders, interest calculations, portfolio performance reports and administrative dashboards. Integrated financial data providers and lending partners can help streamline credit assessments and loan management operations.

Mockup of a lending app with applications, rates, and repayment tracking

App like Klarna or Affirm

A buy now, pay later (BNPL) platform that allows customers to purchase products immediately and pay through flexible instalment plans, creating a smoother checkout experience for both shoppers and merchants. Includes merchant checkout integrations, instant credit eligibility assessments, configurable repayment schedules, interest-free and interest-bearing payment options, automated payment reminders, repayment tracking, refunds, purchase management and merchant analytics. Additional features can include virtual shopping cards, spending limits, customer payment dashboards, automated billing, missed-payment notifications, order synchronization, merchant settlement management and risk monitoring. Credit assessment, lending and payment operations can be supported through compliant financial partners.

Mockup of a buy now, pay later app with instalments and checkout

Key features of our
fintech solutions for every panel

User, business and admin features are listed in full on this page so the whole set can be read without opening a panel. A first release uses only the subset your product, your users and the compliance review actually need.

User panel

  • Sign-up with phone, email or social login
  • KYC identity verification with document and selfie check
  • Biometric and passwordless login
  • Account balances and transaction history
  • Send, request and split payments
  • Bill pay and scheduled payments
  • Virtual and physical card management
  • Freeze, unfreeze and spending limits
  • Multi-currency wallet and FX
  • Savings goals and round-ups
  • Spending insights and budgets
  • Real-time push notifications
  • Downloadable statements and tax documents
  • Rewards and referral bonuses
  • Dispute a transaction
  • In-app chat support
  • Two-factor authentication
  • Privacy and data-sharing controls

Business panel

  • Business onboarding with KYB verification
  • Multi-user access with roles
  • Invoicing and payment links
  • Bulk and scheduled payouts
  • Accounts payable approvals
  • Corporate cards with spend controls
  • Payroll and contractor payments
  • Merchant checkout and payment links
  • Settlement and payout reports
  • Refunds and chargeback handling
  • Accounting sync with QuickBooks and Xero
  • API keys and webhooks
  • Cash-flow dashboard
  • Tax and fee reports
  • Multi-currency collections
  • Approval workflows
  • Audit log of user actions
  • Dedicated support channel

Admin panel

  • User and business management
  • KYC and KYB review queue
  • Transaction monitoring rules
  • AML alert and case management
  • Fraud scoring dashboard
  • Limits, fees and pricing configuration
  • Double-entry ledger view
  • Daily reconciliation reports
  • Dispute and chargeback workflow
  • Refund approvals
  • Promotions and rewards setup
  • Content and notification management
  • Role-based admin access
  • Immutable audit trail
  • Regulatory and partner-bank reports
  • Revenue and usage analytics
  • System health and alerts
  • Support ticket management

Payment rails and
integrations we work with

Fintech products depend on their integrations. These are the rails and providers US and UK fintechs use most, from bank transfers and cards to open banking, sponsor banks, KYC, accounting and messaging. Every integration is idempotent, retried safely, monitored and reconciled daily.

US bank transfers

Rails and providers

ACH under NACHA rules, plus RTP and FedNow for instant bank transfers We connect the product to these providers. Which ones we use depends on the market, the partner bank and the licence you already hold.

What we build

Pay-ins, payouts, returns handling and same-day ACH, with an idempotency key on every call and a daily match against the bank file. Failed calls retry safely, and the ledger is reconciled every day.

Cards

Rails and providers

Stripe, Adyen and Marqeta for acceptance and issuing We connect the product to these providers. Which ones we use depends on the market, the partner bank and the licence you already hold.

What we build

Card acceptance, card issuing, spend controls and webhooks, so a freeze, a limit or a decline is reflected in the ledger the same day. Failed calls retry safely, and the ledger is reconciled every day.

Open banking and data

Rails and providers

Plaid and MX for account linking and balance checks We connect the product to these providers. Which ones we use depends on the market, the partner bank and the licence you already hold.

What we build

Account linking, balance checks and consent-based data access aligned with the FDX API standard. The CFPB 1033 rule is under revision, so we track the final version. Failed calls retry safely, and the ledger is reconciled every day.

Banking-as-a-service

Rails and providers

Sponsor-bank platforms that hold the accounts We connect the product to these providers. Which ones we use depends on the market, the partner bank and the licence you already hold.

What we build

Accounts, cards and ledgers on a partner bank, so you can offer banking features without building a bank or holding the licence yourself. Failed calls retry safely, and the ledger is reconciled every day.

KYC and KYB

Rails and providers

Persona, Alloy and Onfido for identity and business checks We connect the product to these providers. Which ones we use depends on the market, the partner bank and the licence you already hold.

What we build

Identity checks, sanctions screening and business verification, with the result stored so an auditor can see who was checked and when. Failed calls retry safely, and the ledger is reconciled every day.

Europe and UK

Rails and providers

SEPA Credit Transfer and Instant, SWIFT, and UK open banking We connect the product to these providers. Which ones we use depends on the market, the partner bank and the licence you already hold.

What we build

Cross-border and euro payment flows for UK and EU products, alongside the US rails when the same product serves both markets. Failed calls retry safely, and the ledger is reconciled every day.

Accounting

Rails and providers

QuickBooks, Xero and NetSuite for the books We connect the product to these providers. Which ones we use depends on the market, the partner bank and the licence you already hold.

What we build

Automated sync of invoices, payouts and fees, so finance does not retype what the product already recorded in the ledger. Failed calls retry safely, and the ledger is reconciled every day.

Crypto infrastructure

Rails and providers

Regulated custody and on-ramp and off-ramp APIs We connect the product to these providers. Which ones we use depends on the market, the partner bank and the licence you already hold.

What we build

Wallets, fiat ramps and transaction history through a regulated custody partner, rather than an unregulated wallet held on your own servers. Failed calls retry safely, and the ledger is reconciled every day.

Ensuring fintech compliance for secure and trusted software solutions

Shield, lock, fingerprint check, and compliance icons

THE TISA builds software to these requirements so a partner bank or an assessor can review it. Your organisation or your bank partner holds the licences and certifications. We make sure the software passes their reviews, and we do not issue the certification ourselves.

  • PCI DSS v4.0

    Who it applies to

    Anyone whose product handles card data, including a merchant or a platform that stores or passes a card number We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    Tokenisation and hosted fields so raw card data never touches your servers, and the card number stays with the processor. Those controls sit in the product from the very first release.

  • SOC 2

    Who it applies to

    B2B fintechs selling to banks and enterprises that ask for a control report before they connect We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    Access controls, change management, logging and encryption mapped to SOC 2 controls, so an assessor can see how the product is run. Those controls sit in the product from the very first release.

  • KYC, AML and the Bank Secrecy Act

    Who it applies to

    Products that move money, hold a wallet balance, or originate a loan for a customer We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    Identity verification, sanctions screening, transaction monitoring and suspicious-activity case workflows, with a person deciding the cases the rules flag. Those controls sit in the product from the very first release.

  • GLBA and CCPA

    Who it applies to

    Products that hold US consumer financial data and have to say how that data is used We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    Data minimisation, consent records, encryption and deletion workflows, so a customer can see what was collected and ask for it to be removed. Those controls sit in the product from the very first release.

  • CFPB Section 1033

    Who it applies to

    Apps that access or share a consumer's financial data with that consumer's permission We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    Secure, consumer-permissioned data access. The rule is enjoined and under revision in 2026, so we track the final version before treating any date as in force. Those controls sit in the product from the very first release.

  • SEC and FINRA record-keeping

    Who it applies to

    Investment and trading apps that have to keep a record of what a customer was shown and what they did We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    Immutable records and audit trails, so an order, a disclosure or a change can be reconstructed later without rewriting history. Those controls sit in the product from the very first release.

  • PSD2, PSD3 and SCA

    Who it applies to

    Payment products that serve customers in the UK and the EU We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    Strong customer authentication and open banking consent, so a payment or a data share has a recorded permission behind it. Those controls sit in the product from the very first release.

  • GDPR

    Who it applies to

    Products with users in the UK or the EU, including a US company that serves them We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    A lawful basis for the data, data subject rights and data residency options, so a request to access or delete can be completed from the product. Those controls sit in the product from the very first release.

  • ISO/IEC 27001 controls

    Who it applies to

    Enterprise buyers who ask how the team runs security, even when they do not ask for the certificate itself We build the software so this review can be completed, and we do not issue the certification or the licence.

    How we build for it

    Security practices aligned to the standard's controls, covering access, change and logging on the systems that hold customer money and data. Those controls sit in the product from the very first release.

  • Security at THE TISA

    Data protection, access control, secure development and privacy on client projects, written out on the security page so the same controls can be read outside this compliance list.

    Explore the security page

What we get right
beneath the interface

Users see a balance and a send button. Your business depends on the ledger, the payment calls, the audit trail and the daily reconciliation that sit under them, because that is what keeps every cent traceable.

A ledger that always balances

We use double-entry accounting. Balances are calculated from immutable entries, so every cent traces back to a transaction and a break can be found without rewriting the history of the account.

Payment APIs that never charge twice

Every money movement carries an idempotency key. Network retries, webhook repeats and double taps return the original result, so they never create a second payment for that same payment request.

Audit trails regulators can follow

Every state change records who did what and when. Partner banks and auditors can follow that trail and get an answer in minutes, not weeks of reconstructing the whole account by hand.

Daily reconciliation

Automated jobs match your ledger against processor and bank reports each day and flag any break the same day, before it becomes a customer complaint or a later audit problem.

Security in depth

Encryption at rest and in transit, secrets in a managed vault, rate limiting, least-privilege access and penetration testing before launch, so the controls are in the build rather than added later.

Failures handled, not hidden

Money movement fails in predictable ways, so we design for each one instead of treating it as an exception. Each failure has a defined state in the ledger, an alert, and a recovery path your operations team can follow without guessing.

  • ACH returns and NOC codes
  • Card chargebacks and disputes
  • Webhook retries and duplicates
  • Processor or bank-partner outages
  • Partial payouts

How a payment moves

  1. Customer app
  2. API gateway with auth and an idempotency key
  3. Payment service
  4. Double-entry ledger
  5. Processor or bank rail
  6. Webhook
  7. Reconciliation job
  8. Admin dashboard and alerts

How we apply AI in
fintech with a person in control

We add AI where it saves money or time, and keep a person in the loop where money or compliance is at stake. The build is vendor-agnostic, so you can switch between OpenAI, Claude and Gemini as quality and pricing change. AI runs inside your security boundary, with customer data masked before it reaches any model.

AI capabilities and the human control on each
AI capabilityWhat it doesHuman control
Fraud scoringScores transactions and sign-ups in real timeAnalysts review high-risk scores before blocking accounts
AML alert triageSummarises alerts and gathers evidenceCompliance officers make every decision
Underwriting assistanceExtracts data from bank statements and documentsUnderwriters approve every loan
Support assistantAnswers account and policy questions from your documentsHands money disputes to a person
Spending insightsExplains spending and forecasts cash flowUsers control what data is used

Showcasing published work and
fintech excellence from shipped products

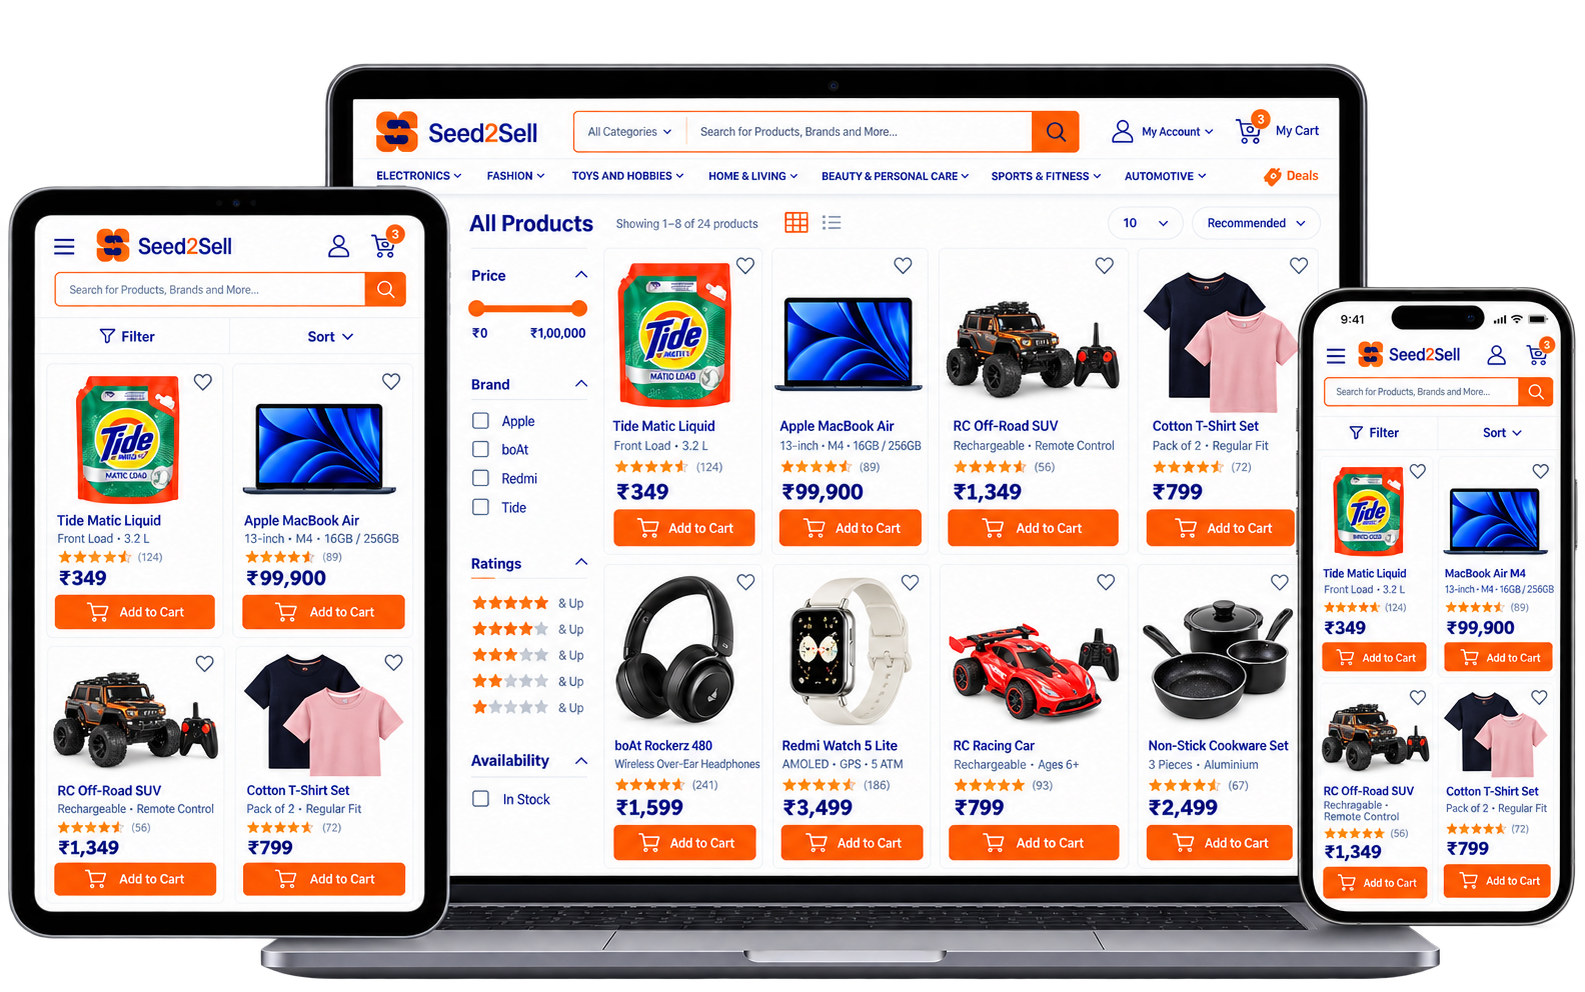
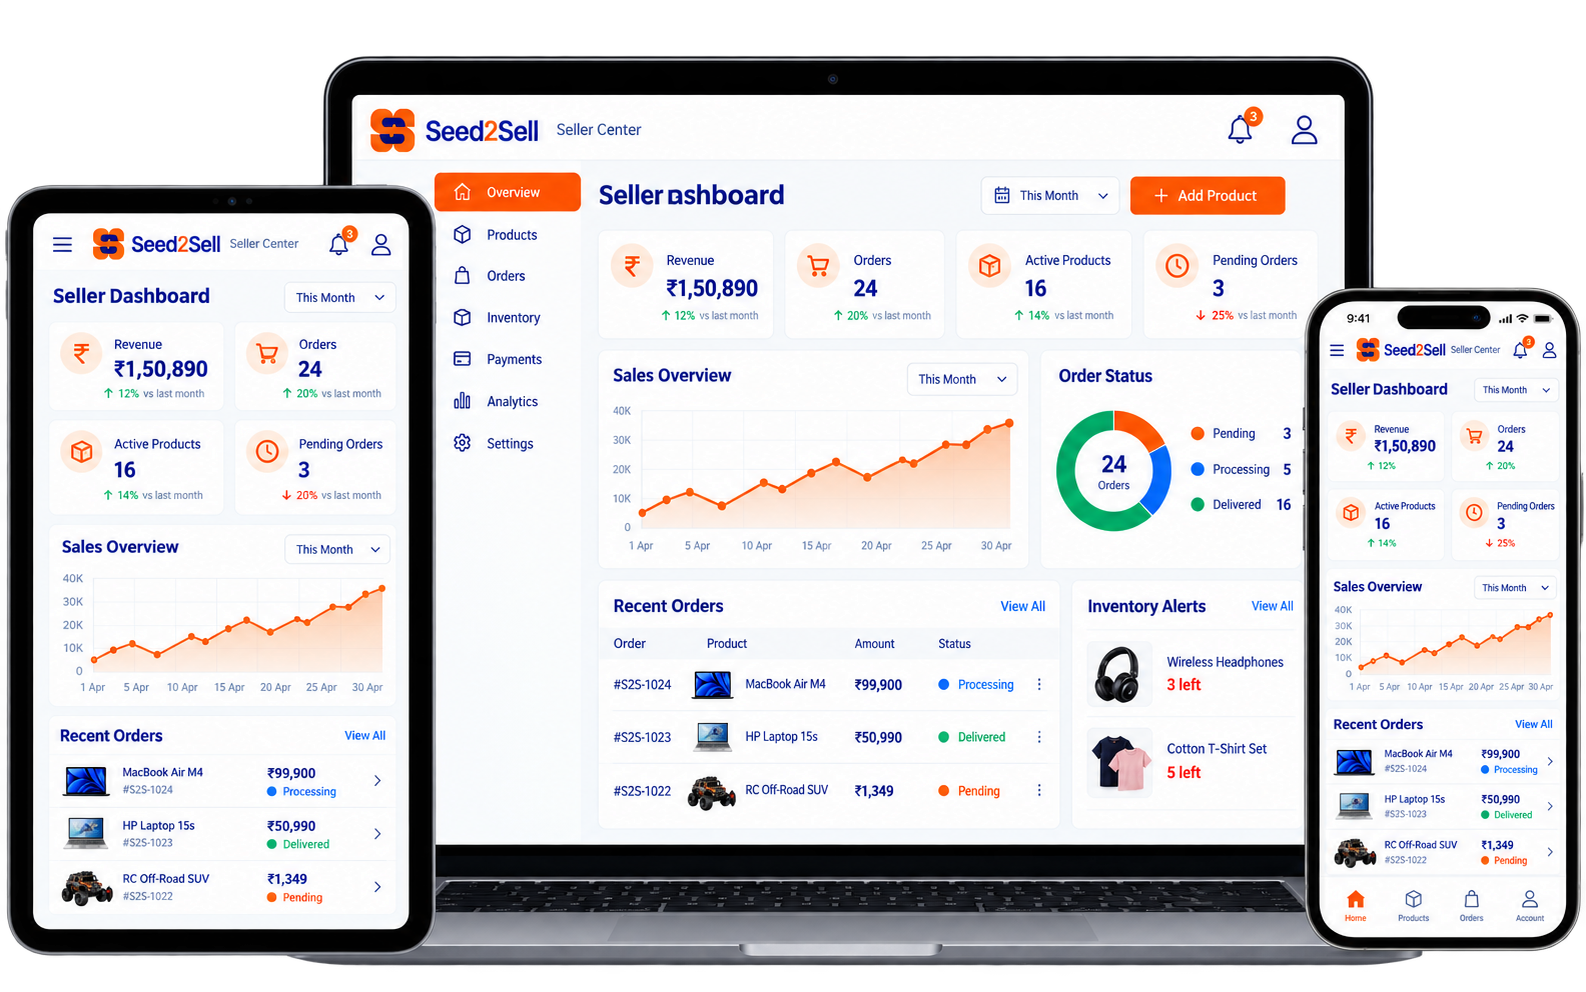
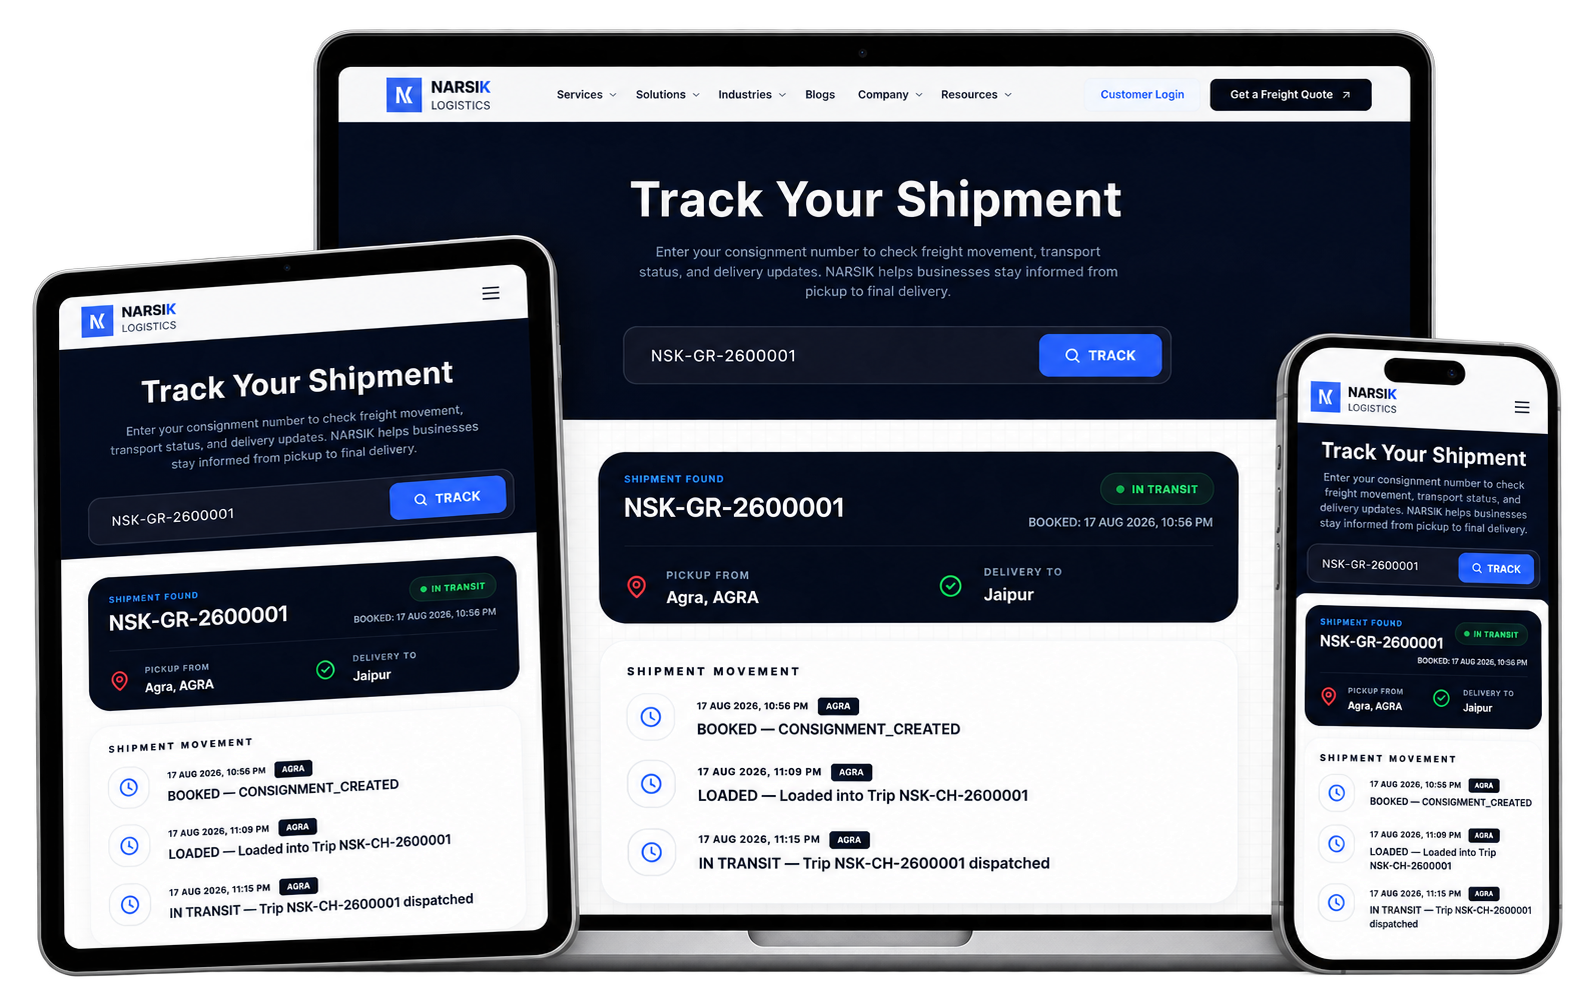
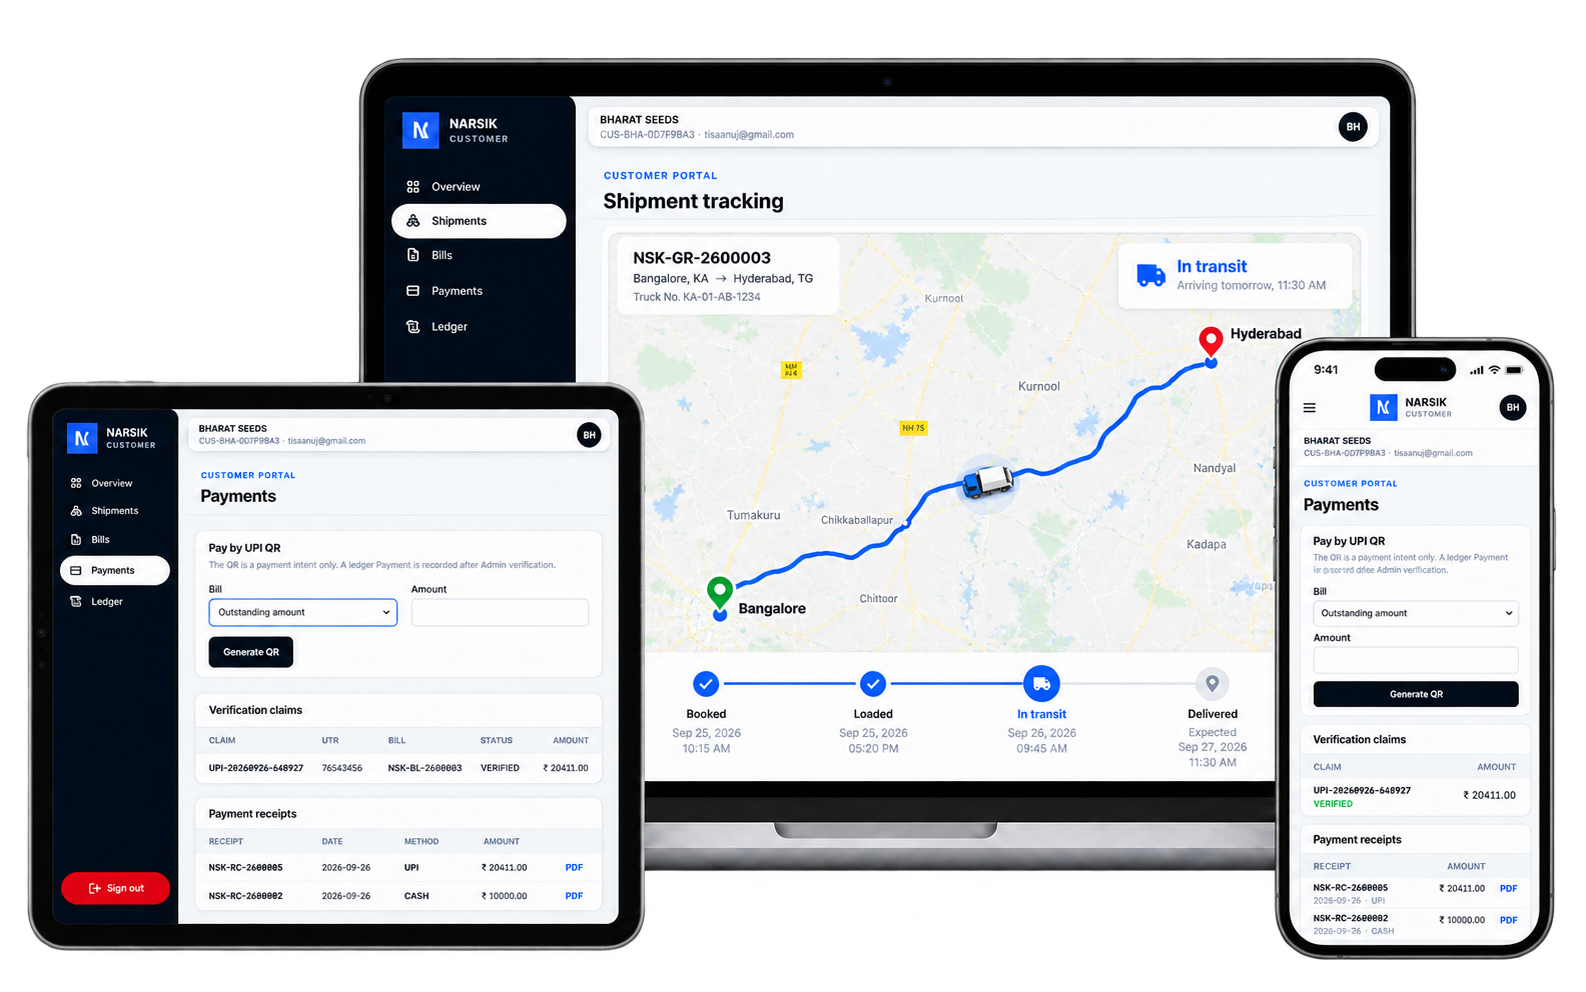
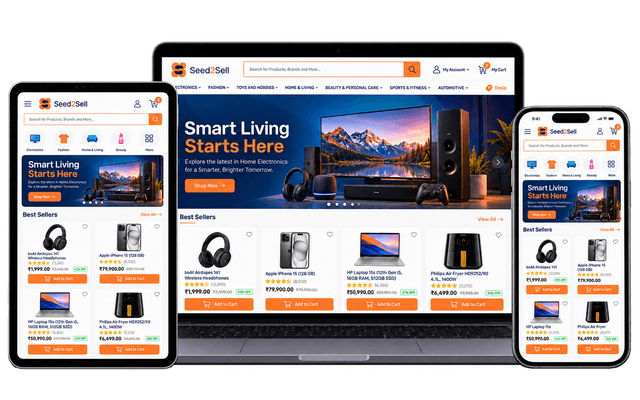
These are published case studies that include money movement, orders or billing. Seed2Sell covers a B2B marketplace with payment and OTP checks. Narsik Logistics covers freight booking and tracking. A payments, wallet or lending case study will be added here when it is published.

Seed2Sell marketplace home

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

Seed2Sell product list

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

Seed2Sell seller dashboard

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

Narsik Logistics shipment tracking

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Narsik Logistics customer portal

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Narsik Logistics services

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Explore all case studies

Who we build production
fintech software for in practice

We build for startups, lenders, banks and credit unions, payment companies, and businesses that want payments, wallets, cards or financing inside a product they already run. The fit depends on the licence model, the rails and how fast the first version needs to reach customers.

  • Fintech startups

    We scope a first version your sponsor bank and first customers will accept, then scale it after launch once the rails, the limits and the compliance checks are already in place.

  • Lenders and credit providers

    We digitise origination, underwriting and servicing so loans close with fewer manual checks, while underwriters still approve every decision the rules do not cover on their own, without a manual workaround.

  • Banks and credit unions

    We build modern digital banking experiences that integrate with your core system instead of replacing it overnight, so balances and accounts stay on the system you already run in production today.

  • Payment and money transfer companies

    We build reliable rails, payouts and daily reconciliation that scale with transaction volume, including returns, retries and the breaks that show up the same day they happen in live production.

  • Businesses adding embedded finance

    We add payments, wallets, cards or financing inside the product you already run, using banking and payment partners so you do not have to become a bank to offer them.

The audiences above are the kinds of teams we already build for, from a first version through to a live product. See how we work with financial services teams.

Choose your build path:
custom, white-label or embedded

Fintech buyers compare three ways to launch: a custom build, a white-label product, or a feature embedded in software they already run. We build all three and tell you which one fits your timeline, budget and licence model. A fixed estimate confirms the range.

  1. 01Custom fintech development

    A product built from the ground up around your fees, limits, workflows and brand. You own the code and the IP. Best for funded startups and institutions whose product is their advantage. Typical range: $50,000–$250,000+ over 3–9 months.

  2. 02White-label fintech platform

    A pre-built wallet, lending or banking framework configured and branded for you. Faster to market, with less control over the roadmap. Best for testing a market or launching in a new region. Typical range: $40,000–$100,000 over 6–12 weeks.

  3. 03Embedded finance in your existing product

    Payments, wallets, cards or financing added inside a SaaS platform, marketplace or app you already run, using banking-as-a-service and payment partners. Best for platforms that want new revenue without becoming a bank. Typical range: $30,000–$90,000 over 2–4 months.

Estimate the cost of your
fintech software development

Fintech software development costs between $25,000 and $250,000+ for most products. Compliance needs, integrations and transaction volume drive that cost more than the number of screens. The table below is a range, and a fixed estimate follows a scoping call.

Fintech product cost and timeline ranges in US dollars
Fintech productCost (USD)Timeline
Fintech MVP or personal finance app$25,000–$60,0003–4 months
Payments or digital wallet platform$50,000–$130,0004–7 months
Lending or BNPL platform$60,000–$160,0004–8 months
Neobank or banking app on banking-as-a-service$90,000–$220,0006–9 months
Investment or trading platform$110,000–$250,000+6–12 months

What changes the cost most

  • Number of payment rails and third-party integrations
  • KYC, AML and other compliance workflows
  • Number of user roles and panels: user, business and admin
  • Real-time features such as trading data or instant transfers
  • AI features that need evaluation and monitoring
  • Security testing and partner-bank review requirements
Calculator linked to payments, compliance, roles, real-time transfers, AI, and security

Ranges exclude licensing, audits and third-party provider fees. We return a fixed estimate within 48 hours of a scoping call, once the rails, the roles and the compliance work are clear enough to price.

Our fintech software
development process, stage by stage

The work runs from discovery and compliance mapping through design, architecture, sprints, security testing, partner sign-off and support after launch. Each stage below names its timing and the outcome your team can review before the next one starts.

  1. 01

    Discovery and compliance mapping

    2–3 weeks

    We map the product model, the regulations, the partner banks, the integrations and the risks before build starts, so the scope is known before anyone writes code. Your team reviews that outcome before the next stage starts.

  2. 02

    UX and trust design

    3–4 weeks

    We design clear money flows, fee disclosures and a clickable prototype so users can see what a payment does before any engineering work starts on the build. Your team reviews that prototype before the next stage starts.

  3. 03

    Architecture and integrations first

    Before the screens

    The ledger, payment services and sandbox integrations are built before the app screens, so the money path is proven before the screens are built around it. Your team reviews that foundation before the next stage starts.

  4. 04

    Development in two-week sprints

    Each sprint

    Each two-week sprint ends with a working build and a demo, so progress is something you can use rather than a written status report you cannot use. Your team reviews that build before the next stage starts.

  5. 05

    Security and quality testing

    Before launch

    Automated tests, code review, dependency scans and penetration testing run before launch, against the flows that actually move a customer's money. Your team reviews those results before the next stage starts.

  6. 06

    Launch with partner sign-off

    Release

    Production keys, monitoring, runbooks and a phased rollout go live only after the partner bank has signed off on that release. Your team reviews that rollout before ongoing support begins.

  7. 07

    Support and scale

    After launch

    After launch we stay on reconciliation monitoring, new rails, features and audits, with the response time written into the support agreement. That work continues for as long as the product is live.

Our comprehensive tech stack for
fintech software development

The languages, databases, cloud and AI tools we use most often for payments, wallets, lending and digital banking. The set changes with the product, the partner bank and the rails, and it is chosen for that build rather than copied from a template.

React
Next.js
Angular
Vue.js
TypeScript
Node.js
NestJS
Python
Django
Java
Spring
Go
FastAPI
Swift
Kotlin
Flutter
Fintech technology stack by layer
LayerTechnologies
Front-endReact, Next.js, Angular, Vue.js, TypeScript
Back-endNode.js, NestJS, Python, Django, Java, Spring, Go, .NET, FastAPI
MobileSwift, Kotlin, Flutter, React Native
BlockchainEthereum, Hyperledger, Corda, Stellar, Solidity
DatabasePostgreSQL, MongoDB, Redis
Cloud and DevOpsAWS, Azure, Google Cloud, Docker, Kubernetes, Terraform
AIOpenAI, Claude, Gemini, LangChain, scikit-learn, XGBoost
SecurityAWS KMS, HashiCorp Vault, OAuth 2.0, OpenID Connect

Advanced technologies driving
fintech innovation in live products

Blockchain, artificial intelligence, machine learning, automation, biometrics and analytics are used only where they change how a financial product settles, decides or stays secure. Each one below is tied to a job the product already has to do.

  • Blockchain

    Shared ledgers for faster settlement, tokenised assets and transparent audit trails, connected to regulated custody partners rather than held as an unregulated wallet running on servers that you yourself own.

  • Artificial intelligence

    Fraud scoring, support assistants, document extraction and personalised insights, with human review wherever money or a compliance decision is at stake and a model must not be left to act alone.

  • Machine learning

    Credit risk models, churn prediction and anomaly detection trained on your own transaction data, so the scores reflect your own book rather than a generic sample taken from somewhere else.

  • Robotic process automation

    Bots that handle repetitive back-office work such as reconciliation checks, report generation and data entry, with a person still able to see exactly what the bot changed and the time it happened.

  • Biometric authentication

    Face ID, fingerprint and liveness checks that secure logins and high-value transactions without relying only on a password that can be reused, shared, or phished at some later date.

  • Big data analytics

    Real-time dashboards across transactions, customers and risk, so operations and compliance teams can act on a trend the same day instead of waiting for it to appear in a monthly report.

Hire experienced fintech developers for your team

Need engineers inside your own team? Add vetted fintech developers with payments, banking and compliance experience on monthly contracts, with overlap on US business hours. They can take on ledgers, payment rails, KYC and AML workflows, and the monitoring that follows launch. See IT staff augmentation.

Developer at a laptop beside a banking screen, payment card, and phone transfer

Why choose THE TISA for
fintech development?

50+ engineers. 100+ projects delivered. 20 published case studies. Those numbers are the public record. The points below are how that shows up on a fintech build: compliance from the first sprint, one team through launch, and ownership of the code.

  • Compliance engineered in

    We design for PCI DSS, SOC 2 and KYC/AML from sprint one, so the controls are part of the product instead of a review that starts after the screens are done.

  • AI-native engineering

    Fraud scoring, AML alert triage and support assistants, with a person in control wherever money or a compliance decision is at stake and the automation must not be left to act alone.

  • US-first delivery

    US payment rails, US regulations and daily overlap with US business hours, so reviews, partner calls and release decisions do not have to wait overnight until the next business morning.

  • One team end to end

    Product design, apps, backend, admin panels and integrations stay with one team, so the ledger, the screens and the partner connections are built together as one complete working product system.

  • You own everything

    You own the code, the IP and the documentation. An NDA is available before the detailed conversation, so the product is not locked to our own product roadmap after launch.

  • Support after launch

    Audit-ready releases, security patching and monitoring continue after launch, with the response written into the agreement rather than left as a verbal promise after the product has already gone live.

What they say about working with THE TISA

The Seed2Sell team, and other founders we have shipped with, on the work itself. These notes come from published case studies and from founders whose products we built, not from a rating we have not verified.

We really appreciate the TISA team. They are hardworking, committed, and clear about our needs. They built a platform that works well today and will grow with us in the future.

THE TISA demonstrated excellent project management, clear communication, and a highly professional approach throughout our collaboration. They delivered the project on time and exceeded our expectations with outstanding results.

Parmeshwar Kumawat

Founder & CEO, NARSIK Logistics

Parmeshwar Kumawat

THE TISA helped us build a reliable e-commerce operations platform with clean workflows, strong delivery, and a product foundation ready to scale.

Sam Patel

Founder, EZSKU

Sam Patel

The student portal gave us a structured platform to manage learning, operations, reporting, and AI-powered student support from one system.

Albert Joe

Product Owner, Education Technology Platform

Albert Joe

THE TISA delivered a scalable hotel platform with strong architecture, complex backend logic, and a performance-focused execution process.

Luke Thompson

Founder, Group Hotel Index

Luke Thompson

The platform helped us shape a modern multilingual learning experience with a clear product structure and dependable technical execution.

Abdul Aziz Sudais

Director, Global Language Center

Abdul Aziz Sudais

More of the same work is written up in the case studies, and the public reviews sit on Clutch and GoodFirms.

FAQs about Fintech Development

Frequently asked questions about
fintech software development

Answers on cost, timelines, compliance, licences, payment rails, security and how a fintech build with THE TISA starts. The same questions and answers are in the page text and in the structured data, so they can be read without opening a hidden panel.

Fintech software development is the design, building and support of software that moves, stores or manages money, such as banking apps, payment systems, wallets, lending platforms and trading apps. It combines product engineering with financial compliance and secure integrations.

Most fintech applications cost $25,000 to $250,000+. An MVP costs $25,000–$60,000. Payments and lending platforms cost $50,000–$160,000. Digital banking and trading platforms cost more. These are ranges, and a fixed estimate follows a scoping call.

Common choices include React and Next.js for web, Swift, Kotlin or Flutter for mobile, Node.js, Python, Java or Go for back-end services, PostgreSQL for ledgers, and AWS or Azure with managed key storage for security.

A fintech development company offers app and web development, payment and banking integrations, compliance workflows such as KYC and AML, security testing, legacy modernization, AI features and ongoing support after the product is live.

Compliance protects customers and keeps your licence or bank partnership. Card data must meet PCI DSS, money movement must meet KYC and AML rules, and consumer data must meet privacy laws. Non-compliant software can be shut down by partners or regulators.

A fintech MVP takes 3–4 months. Payments and lending platforms take 4–8 months. Banking and trading platforms take 6–12 months. The range depends on the rails, the compliance work and how many panels the first release includes.

Yes. We build custom fintech software, so features, fees, limits, workflows and branding follow your business model rather than a template. A white-label path is available when speed matters more than owning every feature.

We use encryption at rest and in transit, tokenisation for card data, multi-factor and biometric login, role-based access, rate limiting, audit logs, secrets management and penetration testing before the product launches.

Look for real fintech case studies, knowledge of your payment rails and regulations, a clear security process, transparent pricing and code ownership. Ask how they handle ledgers, reconciliation and failed payments, because that is where a fintech build usually breaks.

Yes. We offer support plans with the response written into the agreement, covering monitoring, security patches, reconciliation checks, OS updates and new features after the product is already in production.

Usually yes. Most US fintechs partner with a sponsor bank through a banking-as-a-service provider or obtain their own licences. THE TISA builds the software. You or your partner hold the licence, and we do not provide one.

Section 1033 of the Dodd-Frank Act gives consumers the right to access and share their financial data. The CFPB finalised a rule in October 2024, but a federal court has blocked its enforcement and the CFPB is rewriting it, so compliance dates are not in force. Apps that use consumer financial data should still build secure, consent-based data access, because banks are already moving to token-based APIs.

Yes. We build SEPA Credit Transfer, SEPA Instant and SWIFT flows for UK and EU products alongside US rails such as ACH, RTP and FedNow, when the same product needs both markets.

Yes. We connect a scoring service to your transaction flow, run it in monitor-only mode first, then automate actions once accuracy is proven on your data. A person still reviews the cases where money is at stake.

Custom development builds a product you fully own around your model and takes 3–9 months. White-label starts from a pre-built framework and launches faster, with less control over features. Embedded finance adds payments, wallets, cards or lending inside a product you already run, usually in 2–4 months.

Yes. Every fintech product we build records money movements as immutable double-entry postings, and balances are calculated from those entries. That makes every cent traceable and lets daily reconciliation catch breaks the same day.
Let's build your next fintech success story

Share your product idea and the market you want to launch in. A fintech architect replies within one business day with an approach, a timeline range and a cost range, before any detailed build conversation starts.

Use the form for your name, work email, company, product type, budget and a short description of what the product has to do. You can request an NDA before that detailed conversation, so the idea stays private.

Explore our work across 10 capability areas, from AI integrations and intelligent agents to web platforms, mobile apps, SaaS products, and cloud solutions. 20 projects are published as case studies.

50+Team Members
100+Projects Delivered
40+Happy Clients
12+Industries Served
30+Technologies
10+Countries Reached
20+Technical Specialists
35+AI Projects
25+Products Launched
20Published Case Studies

Share your scope

Tell us about the workflow or product. A solutions architect replies within one business day.
7 + 8 =