Lending Software Development for Origination, Servicing and Credit Decisions

THE TISA builds custom lending software for US lenders, credit unions, fintechs and embedded-finance platforms. We develop loan origination systems, loan management systems, BNPL platforms and AI-assisted underwriting that decide faster, explain every decision and keep servicing accurate to the cent. From application to payoff, one platform handles intake, verification, decisioning, documents, funding, repayments and collections. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Lending Software Development
  • CampusFlow — THE TISACampusFlow
  • EZSKU — THE TISAEZSKU
  • Group Hotel Index — THE TISAGroup Hotel Index
  • LockYantra — THE TISALockYantra
  • Narsik Logistics — THE TISANarsik Logistics
  • OpsPilot — THE TISAOpsPilot
  • Ratiwal — THE TISARatiwal
  • Speakify — THE TISASpeakify
  • 50+Team Members
  • 100+Projects Delivered
  • 40+Happy Clients
  • 12+Industries Served
  • 30+Technologies
  • 10+Countries Reached
  • 20+Technical Specialists
  • 35+AI Projects
  • 25+Products Launched
  • 20Published Case Studies

What Is Lending Software Development
for your team?

Lending software development is building the systems that run a loan's full life cycle: application, identity and income verification, credit decisioning, pricing, document signing, funding, payment servicing and collections. A loan origination system (LOS) handles everything up to funding. A loan management system (LMS) handles servicing after funding. Good lending software produces compliant disclosures, explainable decisions and accurate amortisation.

Lending Software We Build
for this product

The lending software development products in this section are Loan Origination Systems (LOS), Loan Management and Servicing Systems (LMS), BNPL and Point-of-Sale Financing, SMB and Commercial Lending Platforms, Mortgage and Home Equity Software, Peer-to-Peer and Marketplace Lending, Collections and Recovery Software. Each product covers the customer flow, the records behind it, and the checks that have to be ready before release.

Loan Origination Systems (LOS)

Online applications, document upload, bank and income verification, decision rules, pricing, e-signature and funding. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Loan Management and Servicing Systems (LMS)

Amortisation schedules, autopay, payment allocation, late fees, payoff quotes, statements and hardship plans. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
BNPL and Point-of-Sale Financing

Pay-in-4 and longer instalment plans at checkout, merchant portals and settlement. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
SMB and Commercial Lending Platforms

Business applications with KYB, cash-flow underwriting, lines of credit, invoice and revenue-based financing. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Mortgage and Home Equity Software

Borrower portals, document collection, pricing engines and integrations with LOS platforms such as Encompass . We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Peer-to-Peer and Marketplace Lending

Borrower and investor portals, loan listing, investor allocation and payment distribution. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Collections and Recovery Software

Rules-based reminders, promise-to-pay tracking and compliant communication limits. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Build Path: Custom,
Configured or Embedded

The table above is the planning range for this build. Final cost depends on volume, integrations, review scope and how much of the platform you already have. We price the work as a range, not a single quote.

Build Path: Custom, Configured or Embedded
PathBest forTimelineTypical cost (USD)
Configure a lending core and build custom front endsLenders with standard products who need speed2–4 months$100,000
Custom LOS or LMSLenders with unique products, data or underwriting4–9 months$250,000+
Embedded lending in a SaaS or marketplacePlatforms offering financing to their users with a lending partner3–5 months$120,000

The Lending Engine
for this product

Decision engine with versioned rules. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Explainable adverse action reasons

Each decline produces specific principal reasons that feed adverse action notices, including for machine-learning models. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.

Accurate amortisation and payment allocation

Interest accrual, payment waterfall (fees, interest, principal), partial payments, prepayments and rate changes are tested against reference calculations. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Loan ledger

Disbursements, payments, fees, charge-offs and recoveries post to a double-entry ledger that ties to the general ledger. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Failures handled, not hidden

Returned autopays, failed disbursements and disputed payments reverse correctly and reschedule what they must. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Lending Software Features
for this product

Features for lending software development are grouped by who uses them: Borrower Portal and App, Underwriter and Loan Officer Workspace, Admin and Compliance. Each group is the set of screens and actions that role needs in the finished product.

Borrower Portal and App

  • Mobile application with save and resume
  • Pre-qualification with a soft credit pull
  • Bank linking for income and cash-flow verification
  • Document upload with automatic data capture
  • Offer comparison with APR and total cost shown clearly
  • E-signature and instant funding
  • Autopay, payment reminders and payoff quotes
  • Hardship and payment plan requests

Underwriter and Loan Officer Workspace

  • Application queue with risk flags
  • Credit report, bank data and document views in one screen
  • Conditions, exceptions and approval limits
  • Notes, tasks and audit trail

Admin and Compliance

  • Product, pricing and fee configuration
  • Policy and model version management
  • Fair lending and decline-reason reports
  • Servicing reports, delinquency buckets and roll rates
  • Investor and partner reporting

Build Lending Software Like Upstart,
Affirm or Kabbage

These names describe the product type for lending software development, not a client list: Like Upstart, Like Affirm or Klarna, Like SoFi, Like Kabbage or Fundbox, Like LendingClub, Like Rocket Mortgage. They show the shape of the product. This page does not use those brands' logos or claim that we built their apps.

These names describe the product type only. This page does not use those brands' logos or visual identity. They are here so you can compare the product shape, not as a claim that we built those companies' apps.

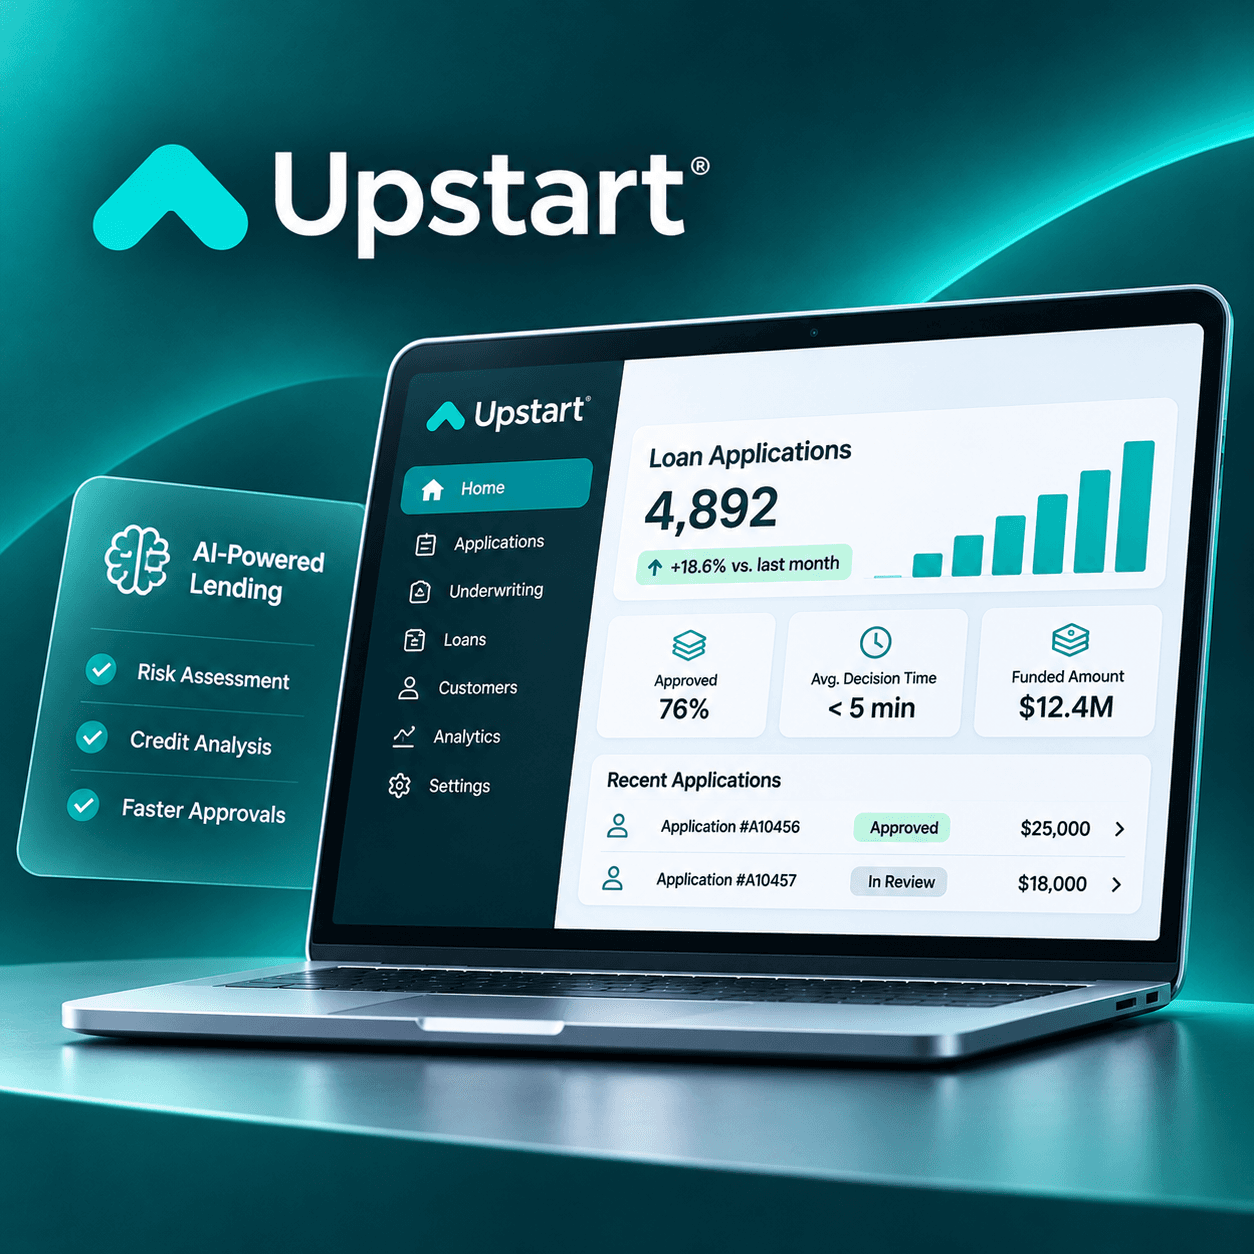
Like Upstart

A personal-loan product of this type takes an application online, prices it from credit and the extra data the lender chooses, and can show an offer the same day. The build covers the form, the decision, the documents, and the payment schedule. A person can still decline a file the model would approve. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a personal lending dashboard with applications, rates, and repayment

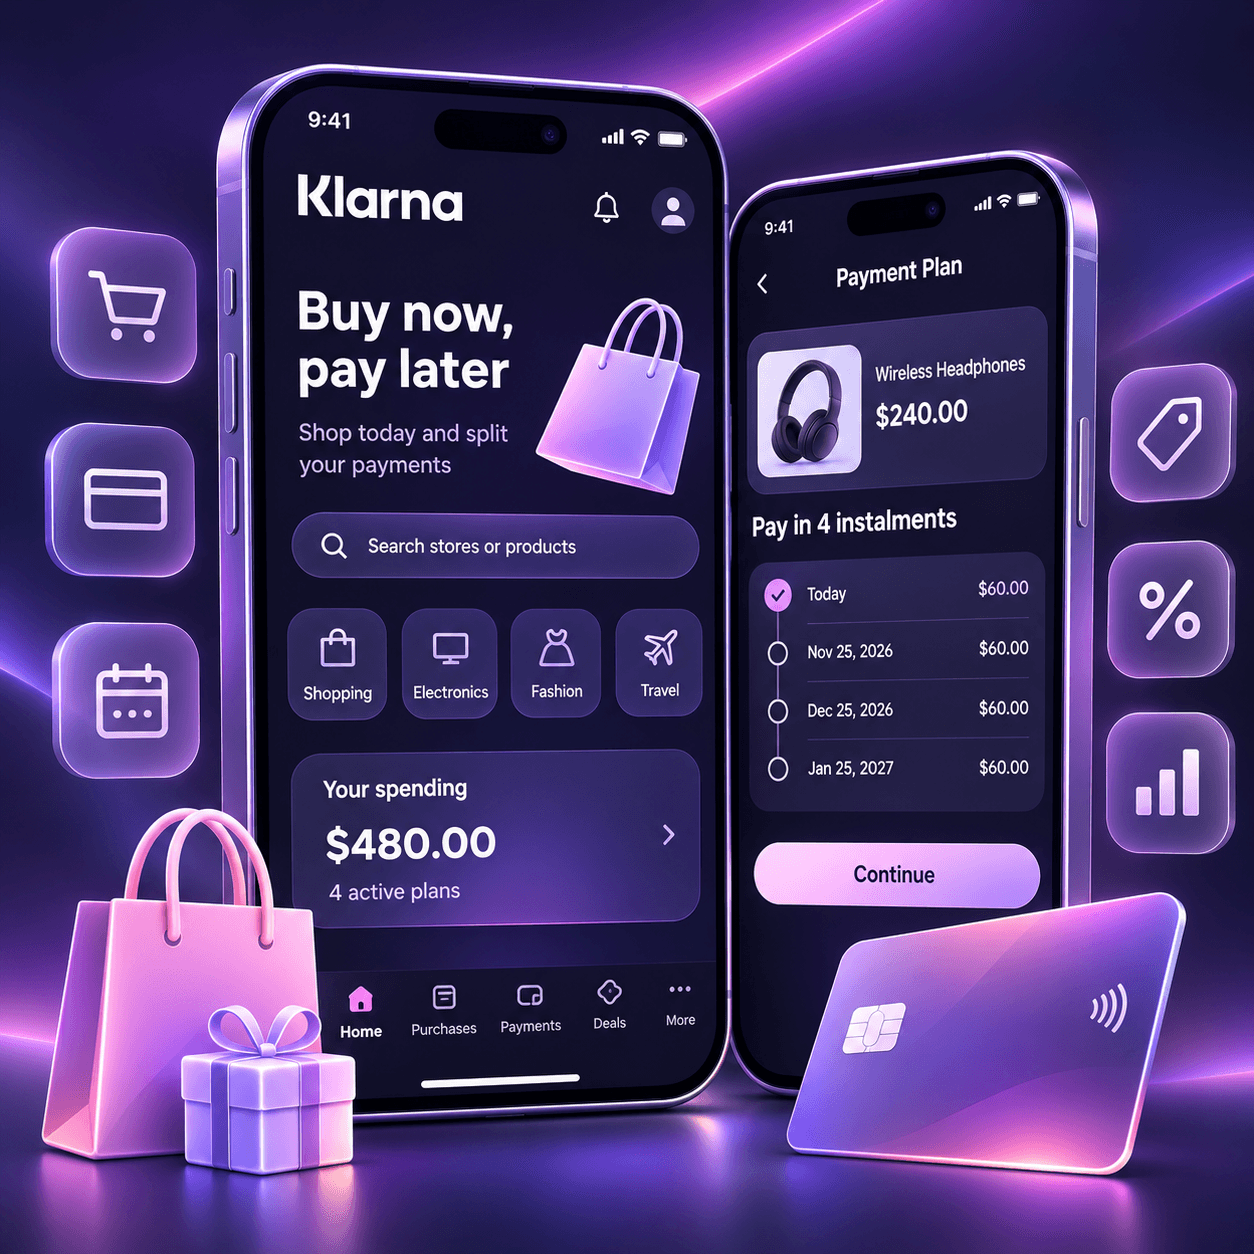
Like Affirm or Klarna

A buy-now-pay-later product of this type offers an instalment plan at checkout and collects the repayments after the merchant is paid. The build covers the eligibility check, the schedule, reminders, refunds, and what the merchant is owed. The credit decision and the licence sit with the lender, not with the storefront alone. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a buy now, pay later app with instalments and checkout

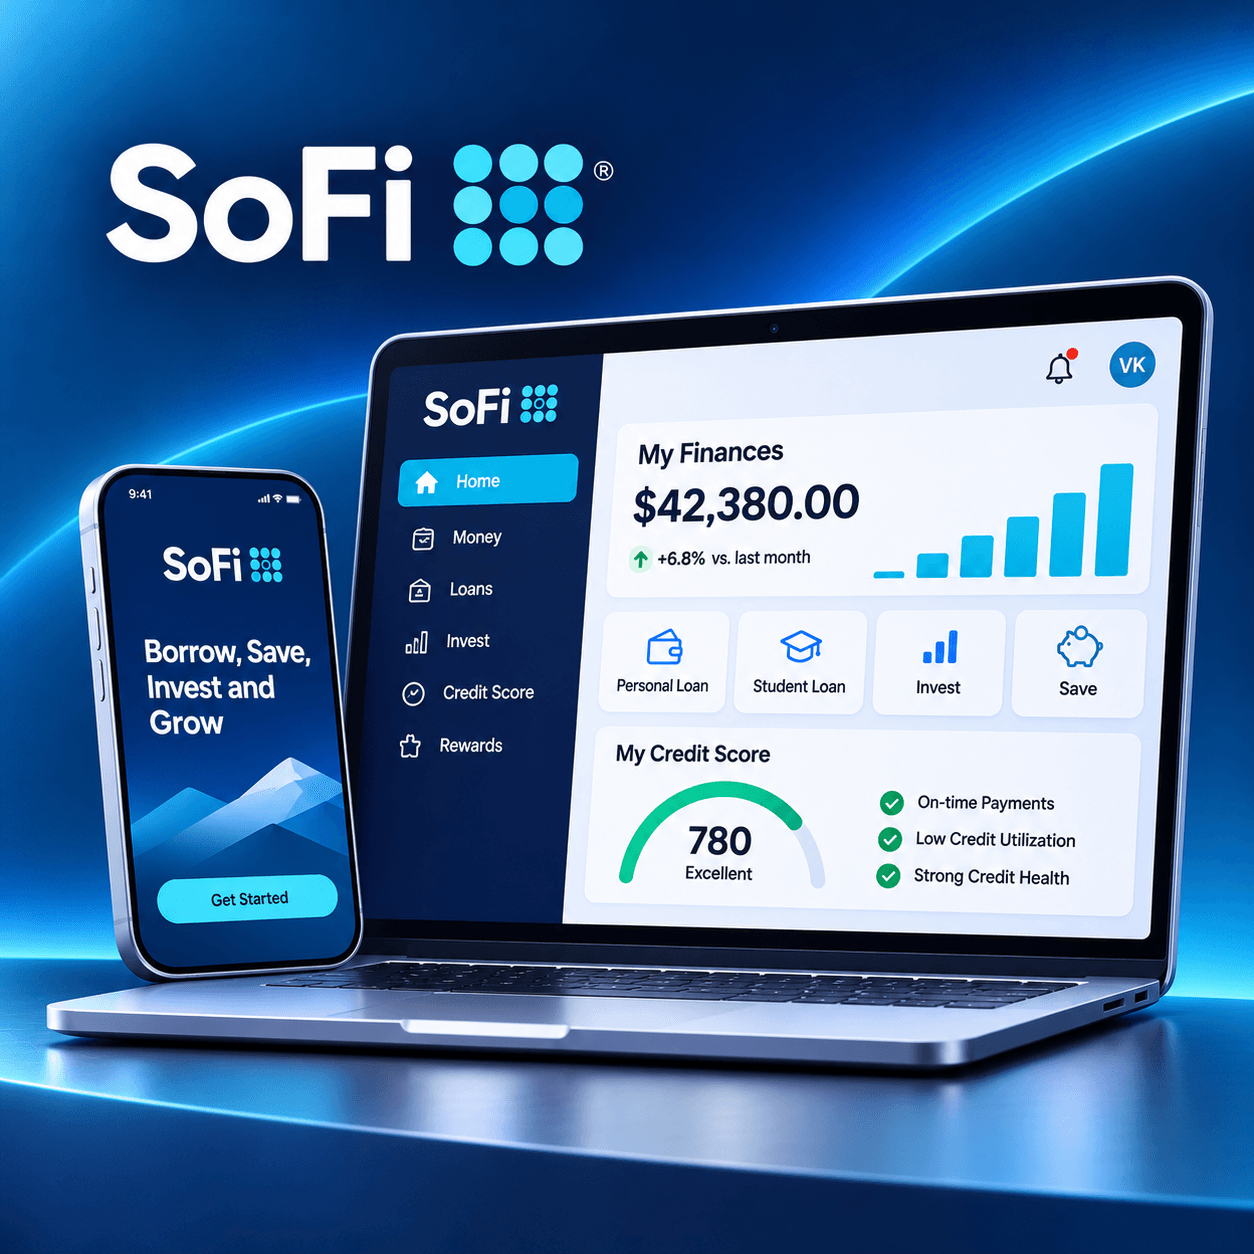
Like SoFi

A combined finance app of this type holds banking, lending, and investing in one login, with a clear line between each balance. A payment to a loan is not the same record as a deposit to spending. Each product still has its own disclosures, and the customer can see which balance changed. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a lending dashboard with personal loans, student loans, and a credit score

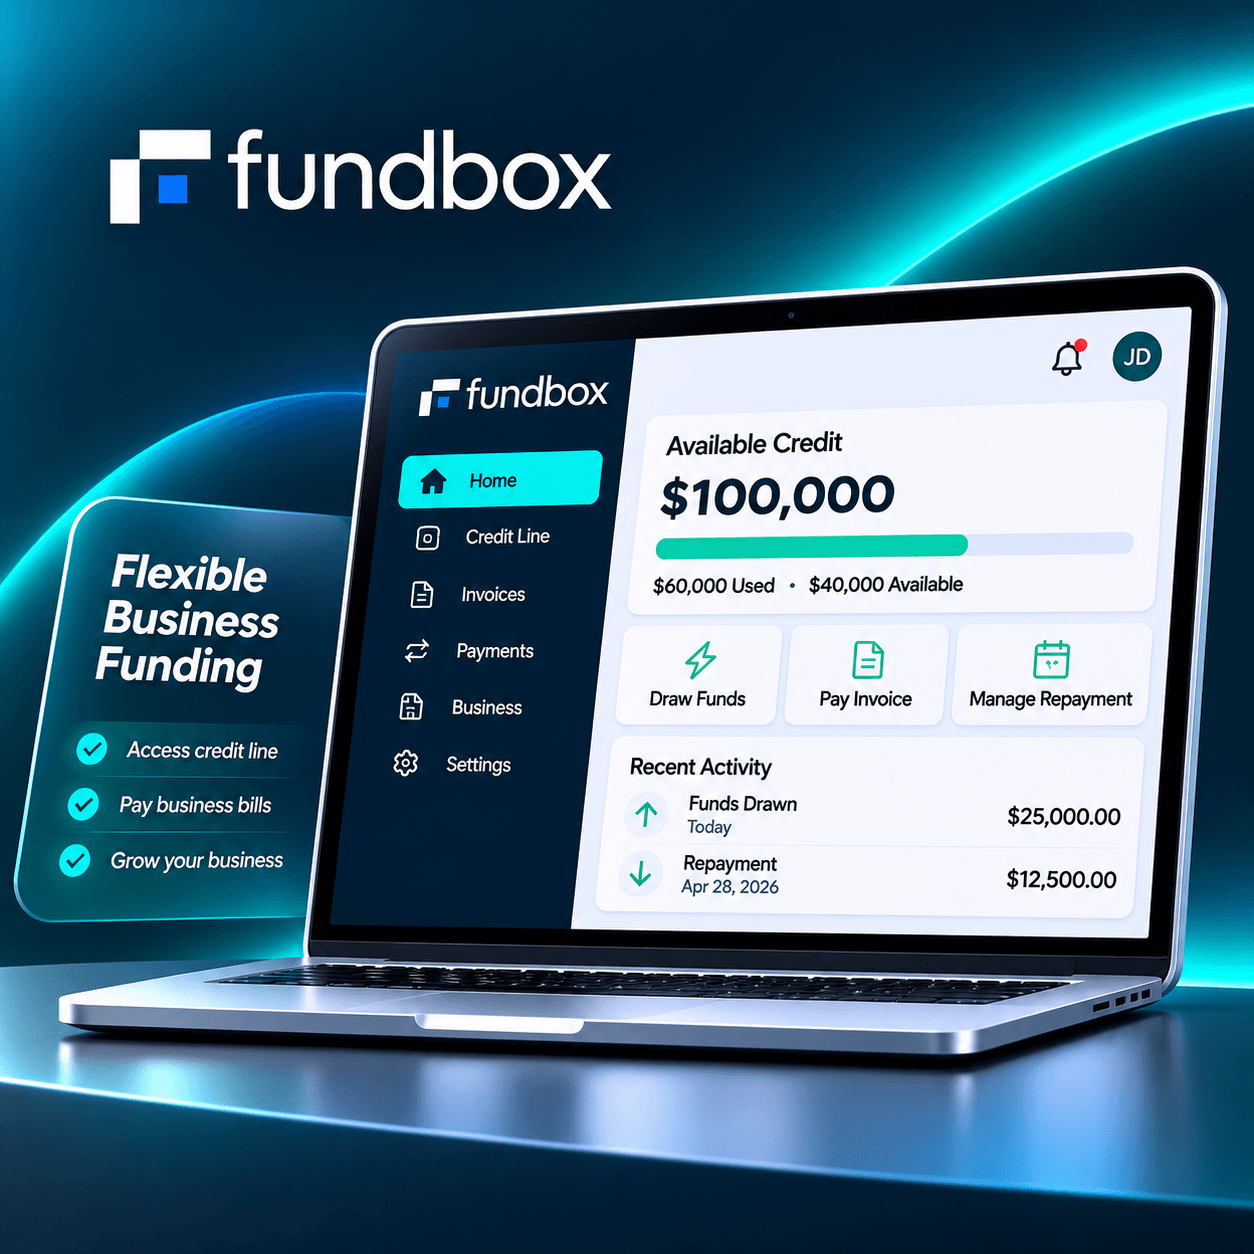
Like Kabbage or Fundbox

A small-business line of credit of this type looks at the company's deposits and invoices, not only a personal credit score. The owner connects accounts, sees a limit, and draws funds that become a balance to repay. Each draw, fee, and repayment is visible, and the limit can change when the cash flow changes. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a small-business funding dashboard with a credit line and draws

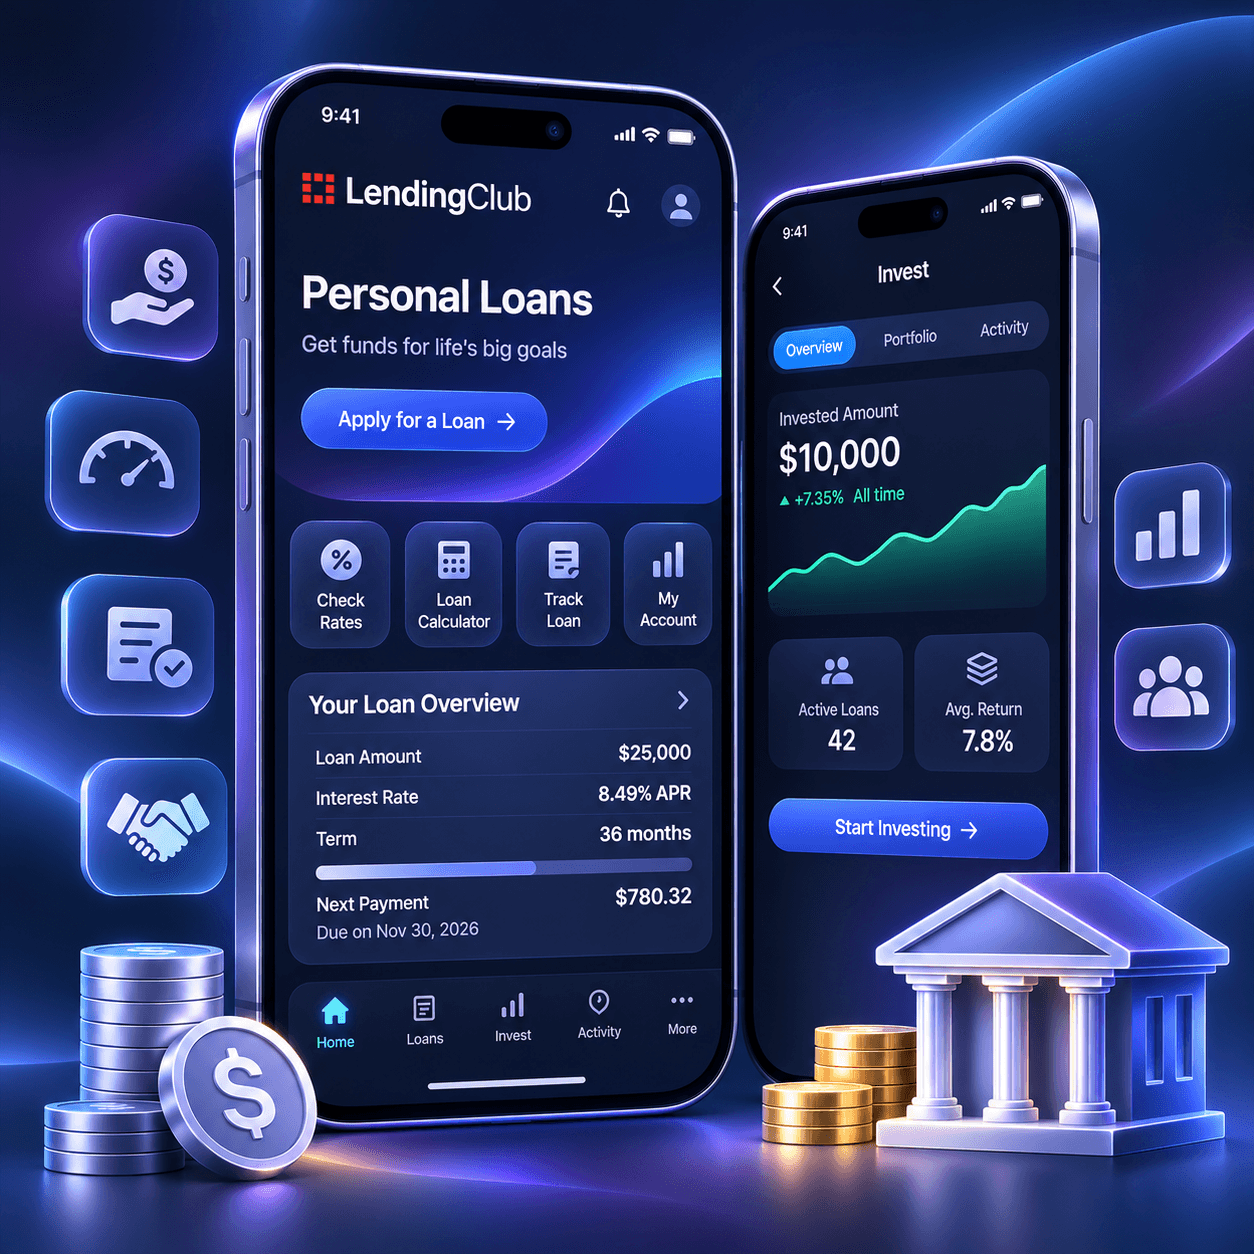
Like LendingClub

A marketplace lending product of this type matches borrower applications with investors or a funding source that agrees to take the loan. The build covers the listing, the documents, servicing, and the payments as they are collected and passed on. Investors see performance without being handed the borrower's raw identity files. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a lending app with applications, rates, and repayment tracking

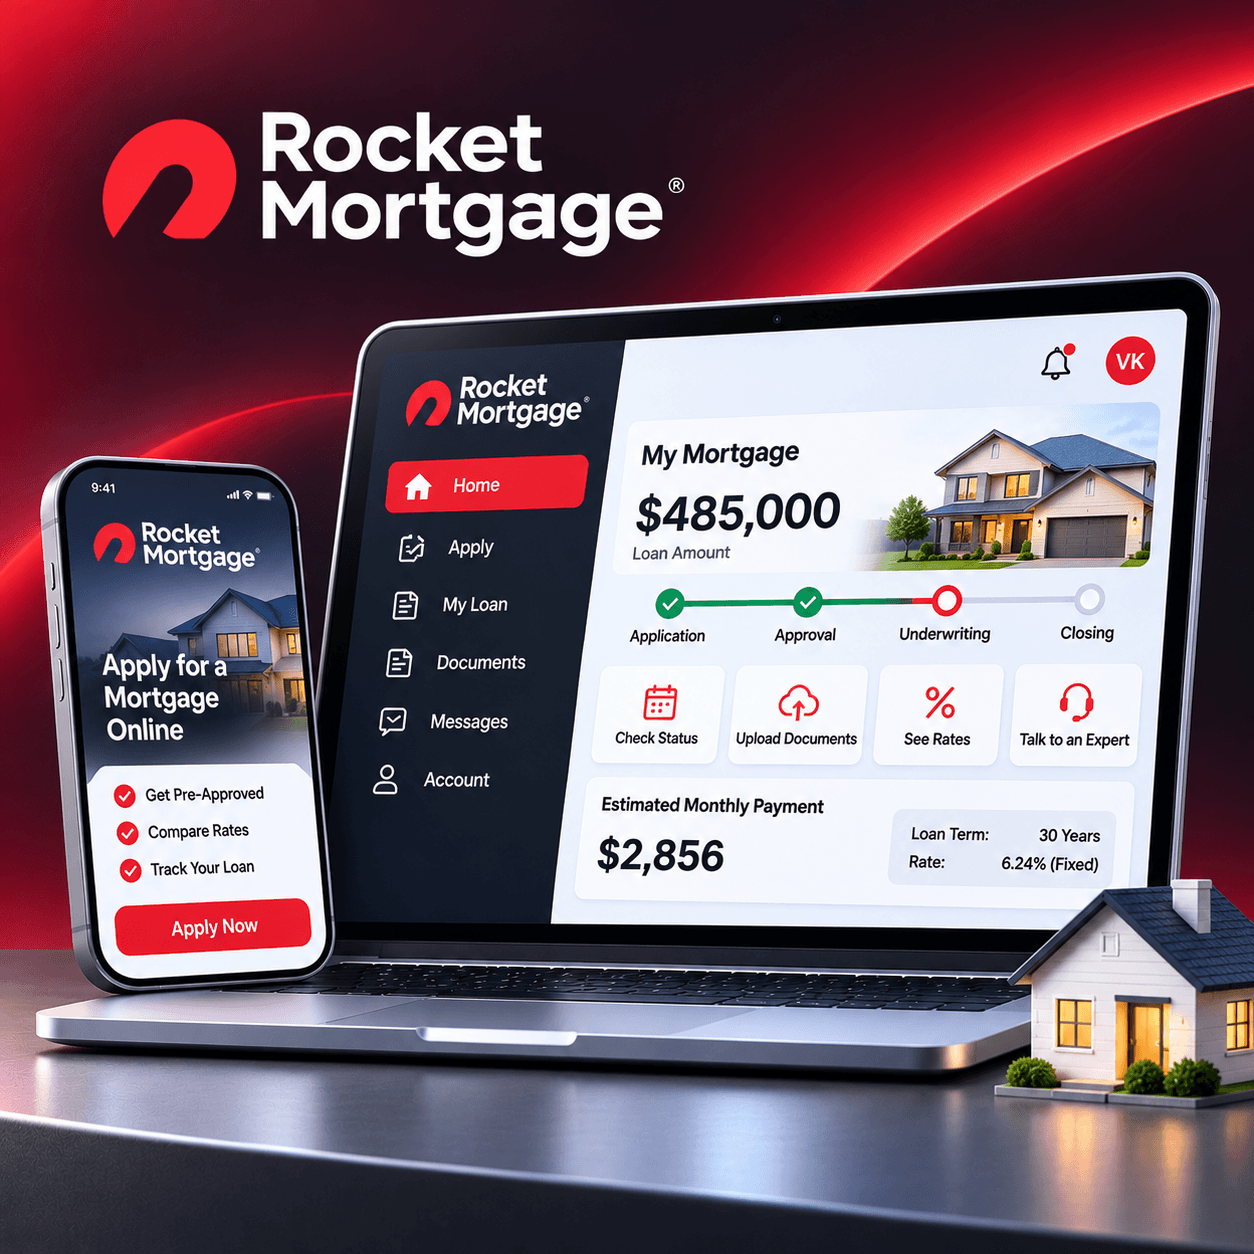
Like Rocket Mortgage

A digital mortgage product of this type lets a borrower start an application, upload documents, and follow the file through to a decision. The build covers the checklist, the status the borrower can see, and the conditions still open. The lender of record makes the credit decision, and the app stores the file they reviewed. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a home financing app with an application, rate, and loan status

Lending Integrations we cover
for this product

Integrations for lending software development cover Credit bureaus, Alternative data and cash flow, Identity and fraud, Income and employment, E-signature, Payments, Lending cores, Accounting. Each connection uses a documented interface, stores the response, and reconciles it against the product record.

Credit bureaus

  • Experian
  • Equifax
  • TransUnion

Alternative data and cash flow

  • Plaid
  • MX
  • Finicity
  • Nova Credit

Identity and fraud

  • Socure
  • Alloy
  • Persona
  • LexisNexis

Income and employment

  • Argyle
  • Pinwheel
  • Truework

E-signature

  • DocuSign
  • Dropbox Sign

Payments

  • ACH
  • Stripe
  • RTP
  • FedNow

Lending cores

Configurable lending cores and LOS platforms

Accounting

  • NetSuite
  • QuickBooks

Lending Compliance Built In
for this product

Compliance for lending software development covers ECOA / Regulation B, TILA / Regulation Z, FCRA, FDCPA / Regulation F, State lending licences and rate caps, Military Lending Act, E-SIGN Act, BNPL rules. Each control is built into the software, and the product keeps the evidence a reviewer can ask for later.

Lending Compliance Built In for this product
RequirementApplies toHow we build for it
ECOA / Regulation BAll credit decisionsAdverse action notices with specific reasons, including for complex AI models (CFPB Circulars 2022-03 and 2023-03); fair lending testing
TILA / Regulation ZConsumer creditAPR and finance charge calculations, disclosures and timing
FCRAUse of consumer reportsPermissible purpose, risk-based pricing and adverse action notices
FDCPA / Regulation FDebt collectionCall frequency limits, time-of-day rules and validation notices
State lending licences and rate capsLenders by stateState-by-state product rules, fee and APR limits
Military Lending ActCovered borrowersMLA status checks and 36% MAPR cap
E-SIGN ActElectronic documentsConsent capture and record retention
BNPL rulesPay-in-4 productsFlexible disclosure and dispute workflows as the CFPB's 2024 interpretive rule was withdrawn in 2025 and states set their own rules

General information, not legal advice. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
AI in Lending Software
for this product

AI in lending software development covers Credit risk models, Document intelligence, Income verification, Collections prioritisation, Underwriter co-pilot. The model scores or drafts, a person can still review the result, and the product keeps a record of what happened.

AI in Lending Software for this product
AI featureWhat it doesHuman control
Credit risk modelsScores applicants using bureau and cash-flow dataModel risk review, bias testing, reason codes
Document intelligenceReads pay stubs, bank statements and tax formsLow-confidence fields go to review
Income verificationCalculates income from bank transactionsUnderwriter confirms edge cases
Collections prioritisationPredicts who needs a reminder or hardship planContact limits enforced by rules
Underwriter co-pilotSummarises the file and flags conditionsUnderwriter makes the decision

Showcasing published work and
fintech excellence from shipped products

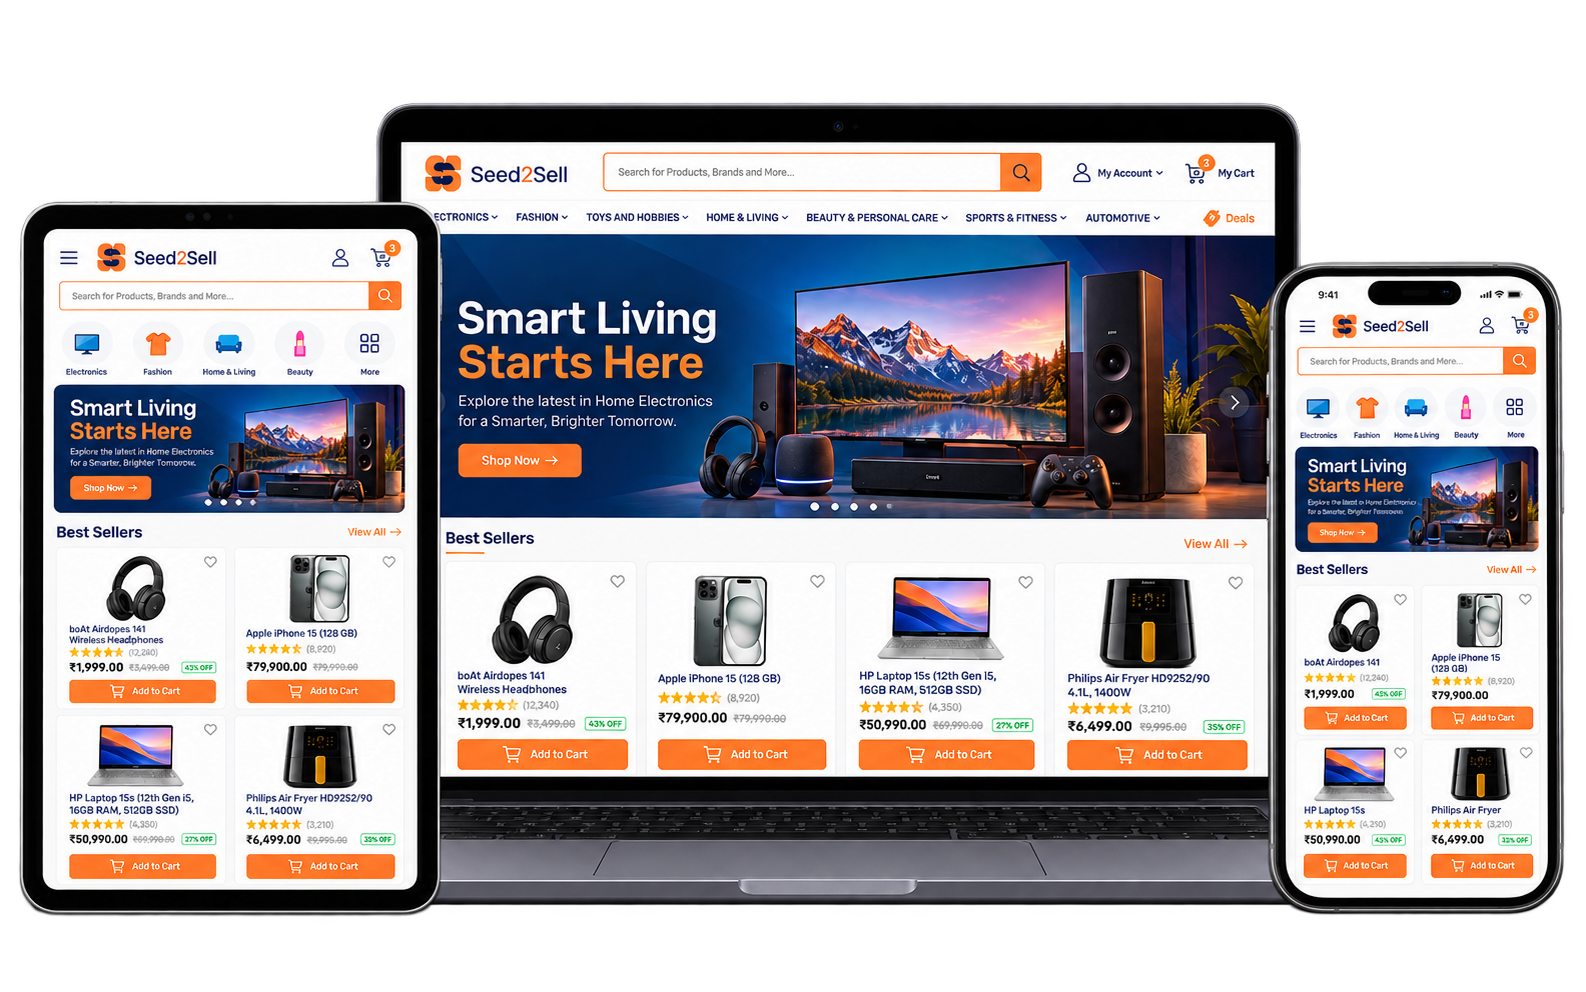
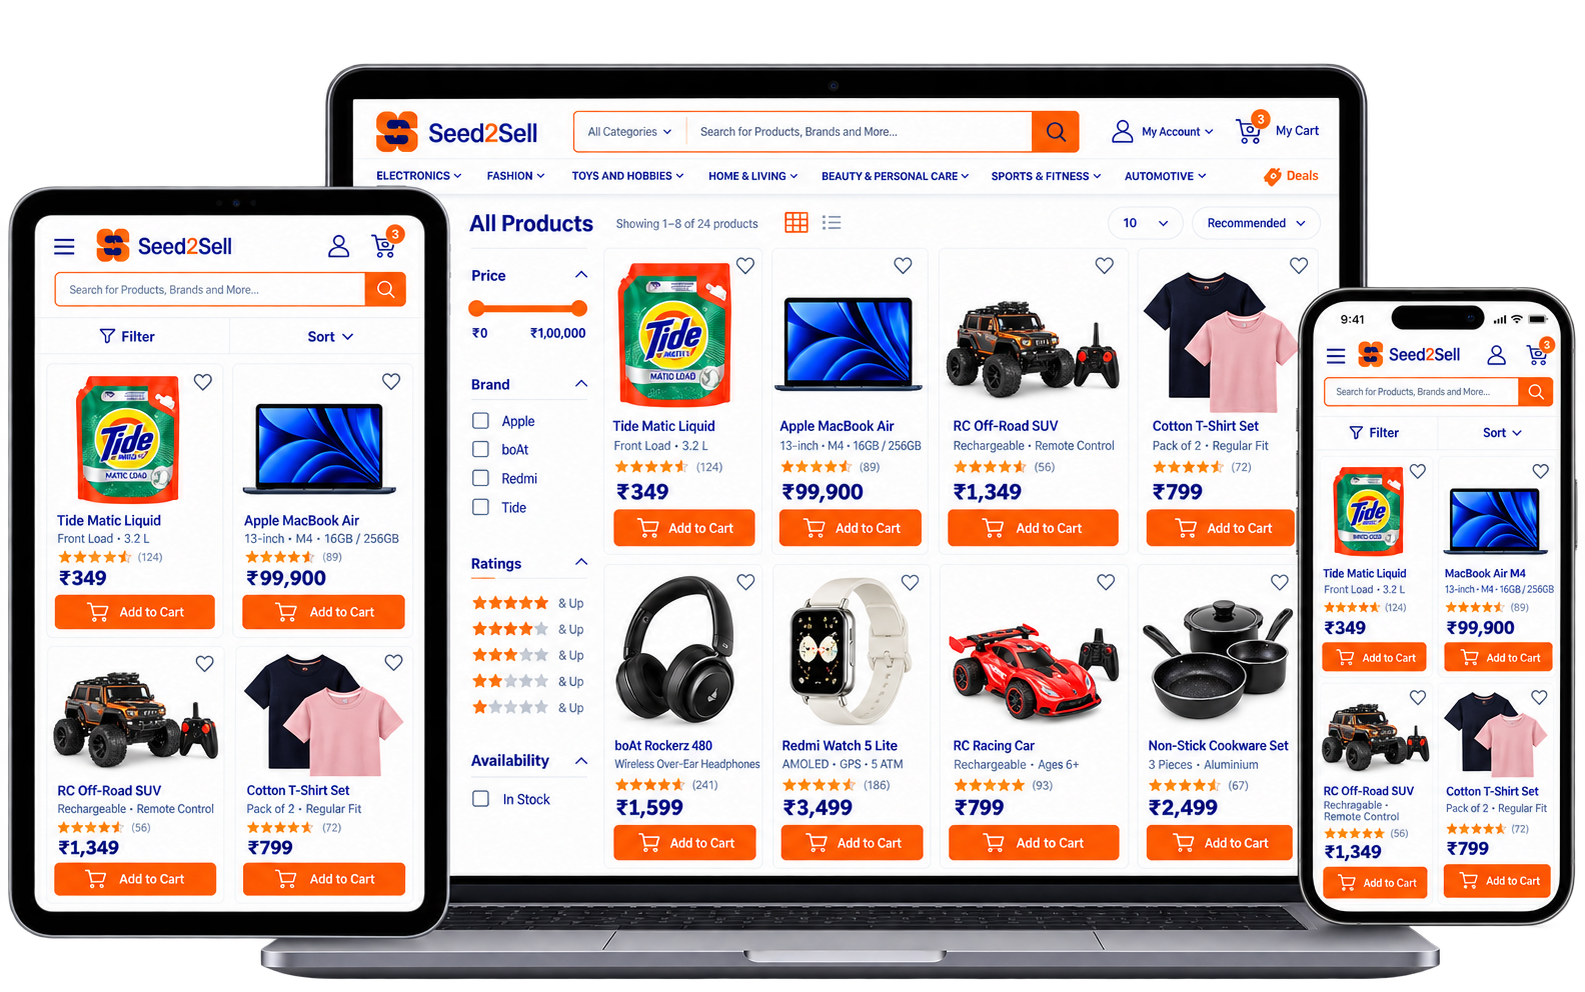
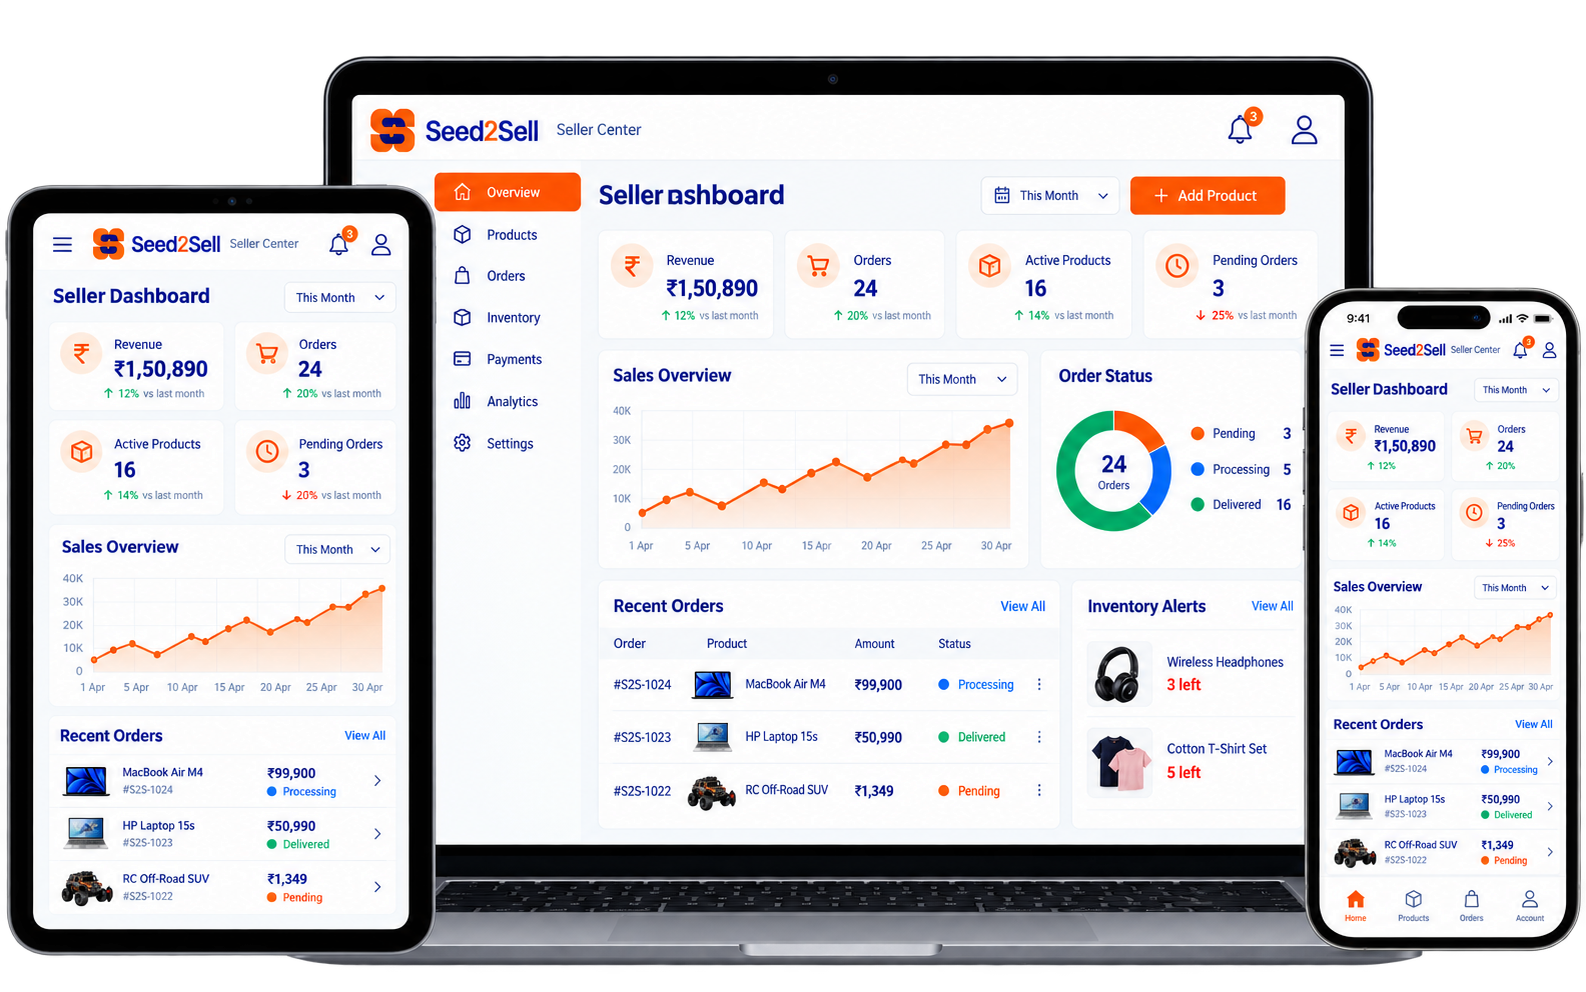
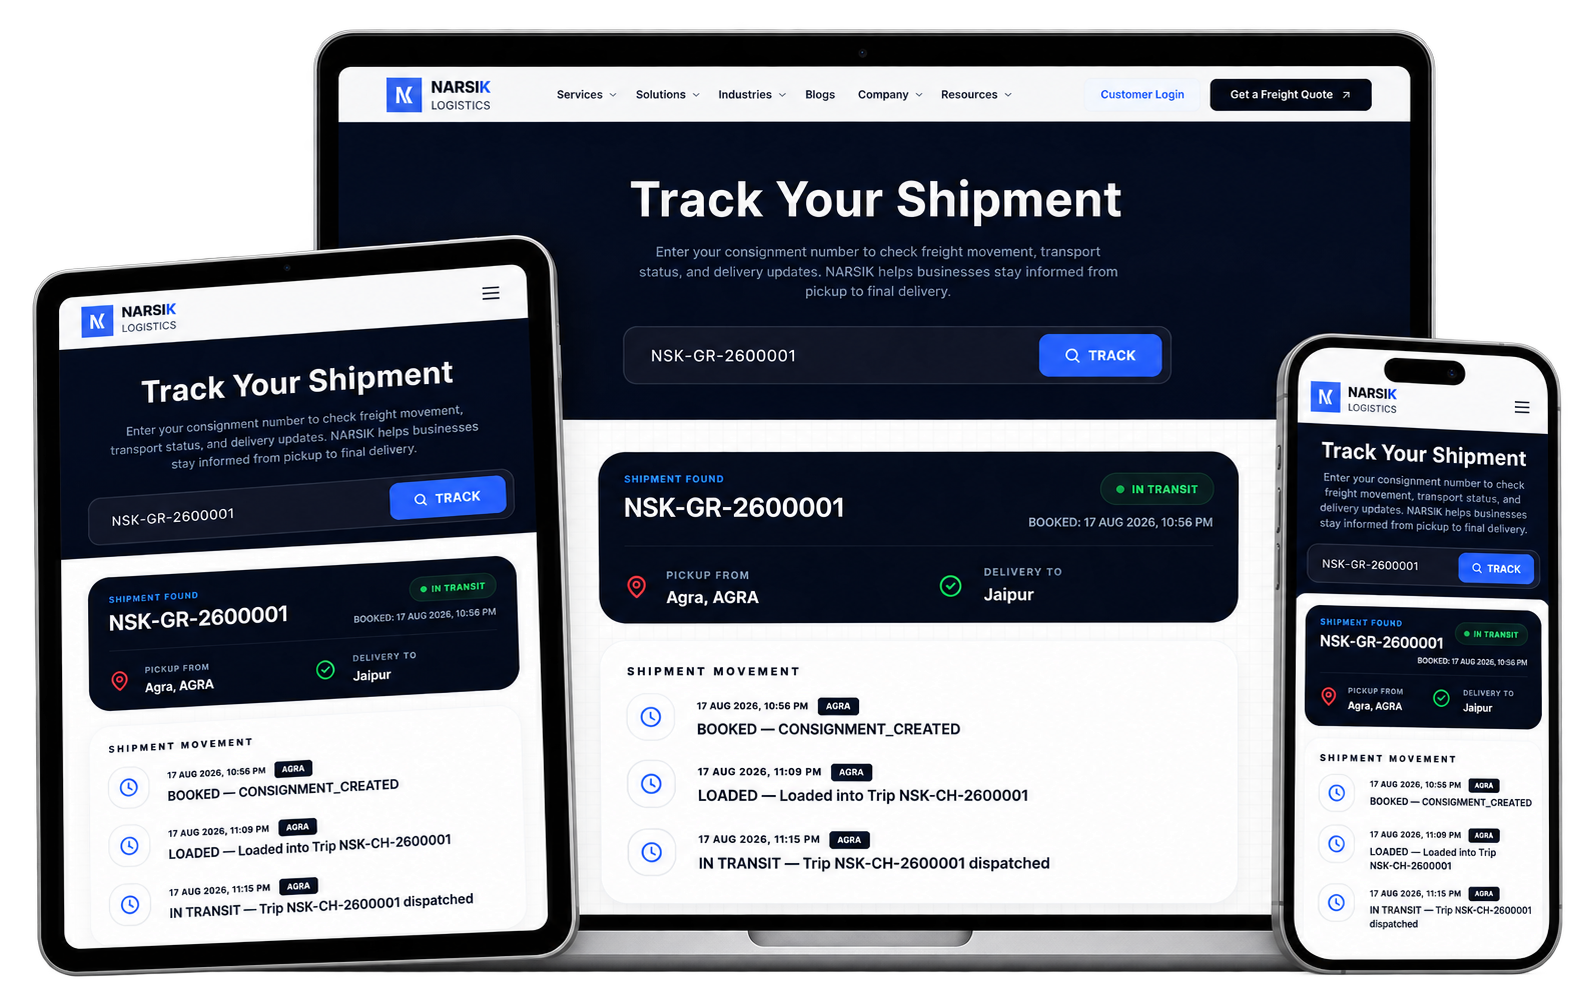
These are published case studies that include money movement, orders or billing. Seed2Sell covers a B2B marketplace with payment and OTP checks. Narsik Logistics covers freight booking and tracking. A payments, wallet or lending case study will be added here when it is published.

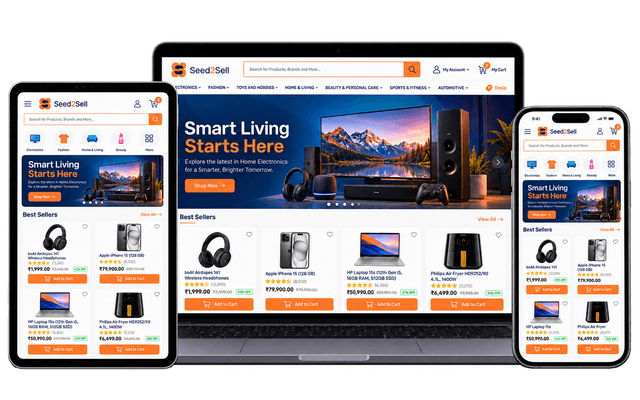
Seed2Sell marketplace home

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

Seed2Sell product list

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

Seed2Sell seller dashboard

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

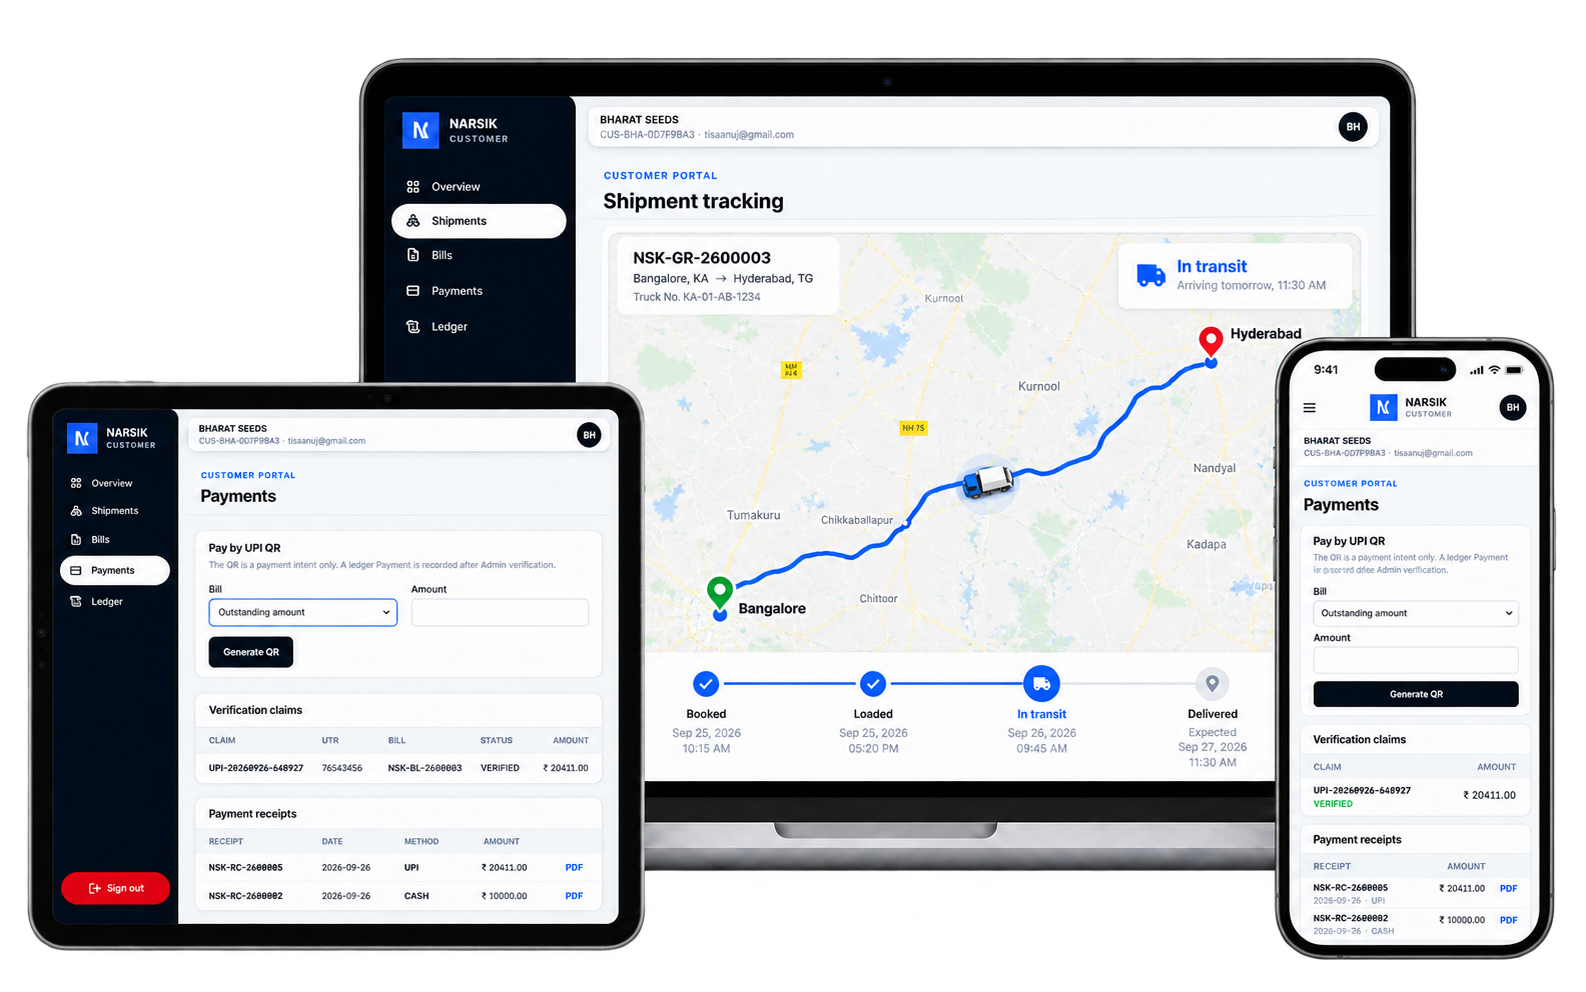
Narsik Logistics shipment tracking

Narsik Logistics

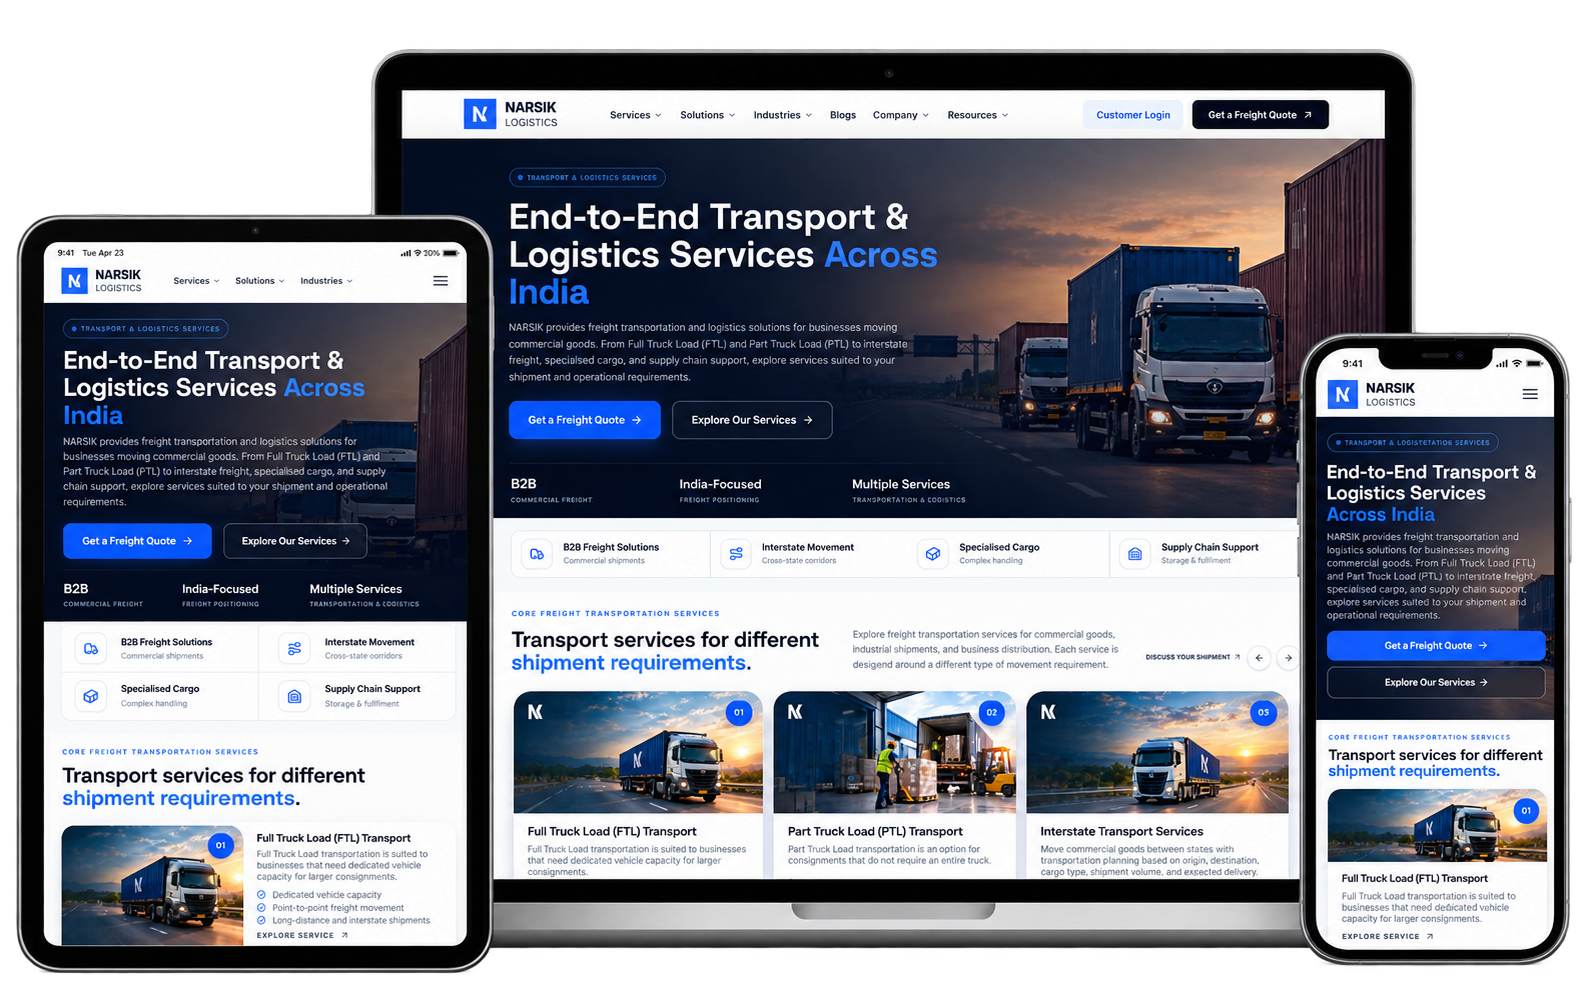
A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Narsik Logistics customer portal

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Narsik Logistics services

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Explore all case studies

How Much Does Lending
Software Development Cost?

Lending software costs $40,000 to $250,000+. Decisioning, servicing complexity and state-by-state compliance drive the cost. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
How Much Does Lending Software Development Cost?
ProductCost (USD)Timeline
Lending softwareBorrower portal on a lending core80,000
2–3 monthsLoan origination system160,000
4–6 monthsLoan management / servicing system180,000
4–7 monthsBNPL platform220,000
5–8 monthsFull LOS + LMS with AI underwriting250,000+

Lending Software Development Process
for this product

The lending software development build moves through Product and policy mapping, Compliance matrix with counsel, 3. Decision engine and ledger design with reference calculations, 4. Borrower and staff UX design with plain-language disclosures, Integrations in sandbox, Testing, 7. Phased launch with monitoring of approval rates, losses and servicing. Each step ends with a written outcome and a handoff, so the next step starts from an agreed scope.

  1. 01

    Product and policy mapping

    loan types, states, pricing and credit policy. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
  2. 02

    Compliance matrix with counsel

    disclosures, notices and limits per state. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
  3. 03

    Decision engine and ledger design with reference calculations

  4. 04

    Borrower and staff UX design with plain-language disclosures

  5. 05

    Integrations in sandbox

    bureaus, bank data, KYC, e-sign, payments. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
  6. 06

    Testing

    amortisation accuracy, fair lending checks and security. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
  7. 07

    Phased launch with monitoring of approval rates, losses and servicing

These stages sit inside the studio software development process. The chart is the order for this product. The linked page explains how a build moves from discovery through release and handover.

See the development process

Tech Stack we use
for this product

Java, Kotlin, Python, Node.js · PostgreSQL · Kafka · React, Next.js, Flutter · Python ML (scikit-learn, XGBoost) with SHAP explanations · AWS and Azure. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Java
Kotlin
Python
Node.js
PostgreSQL
React
Next.js
Flutter
scikit-learn
AWS
Azure

Why Choose THE TISA for
Lending Software Development

Teams hire THE TISA for lending software development because one team owns the product, the integrations and the evidence. You receive the code, the records and a launch handover when the build is done.

  • Every decision replayable with inputs, policy version and reasons
  • Explainable AI that supports adverse action notices
  • Servicing math tested against reference calculations
  • State-by-state rules configured, not hard-coded
  • Full code ownership and US time-zone collaboration

Related Fintech Services
for this product

Pages related to lending software development include Banking software development, Fintech API integration. Open the one that matches the next part of the product, or return to the fintech hub for the full list.

Banking Software and Website Development

Online banking portals, customer onboarding websites, internal banking dashboards and integrations with core banking systems for banks, credit unions and digital lenders, connected to the core system you already run today.

Explore Service

Fintech API Integration

Reliable connections to banks, processors, KYC vendors, open banking APIs and accounting systems, with retries, monitoring and a daily reconciliation against the ledger.

Explore Service

fintech software development services

What they say about working with THE TISA

The Seed2Sell team, and other founders we have shipped with, on the work itself. These notes come from published case studies and from founders whose products we built, not from a rating we have not verified.

We really appreciate the TISA team. They are hardworking, committed, and clear about our needs. They built a platform that works well today and will grow with us in the future.

THE TISA demonstrated excellent project management, clear communication, and a highly professional approach throughout our collaboration. They delivered the project on time and exceeded our expectations with outstanding results.

Parmeshwar Kumawat

Founder & CEO, NARSIK Logistics

Parmeshwar Kumawat

THE TISA helped us build a reliable e-commerce operations platform with clean workflows, strong delivery, and a product foundation ready to scale.

Sam Patel

Founder, EZSKU

Sam Patel

The student portal gave us a structured platform to manage learning, operations, reporting, and AI-powered student support from one system.

Albert Joe

Product Owner, Education Technology Platform

Albert Joe

THE TISA delivered a scalable hotel platform with strong architecture, complex backend logic, and a performance-focused execution process.

Luke Thompson

Founder, Group Hotel Index

Luke Thompson

The platform helped us shape a modern multilingual learning experience with a clear product structure and dependable technical execution.

Abdul Aziz Sudais

Director, Global Language Center

Abdul Aziz Sudais

More of the same work is written up in the case studies, and the public reviews sit on Clutch and GoodFirms.

Frequently asked questions about
this fintech service

Answers on cost, timelines, licences and compliance for lending software development. The same questions and answers are in the page text and in the structured data, so a reader can find them without opening the accordion.

Lending software costs $40,000 to $250,000+. A loan origination system costs 160,000. A full LOS and LMS with AI underwriting costs $150,000 or more. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
An LOS manages applications through approval and funding. An LMS manages the loan after funding: payments, interest, fees, statements and collections. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes, with controls. Lenders must still give specific adverse action reasons under ECOA, test for bias and govern models. We build explainability into every model. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
A borrower portal takes 2–3 months. An LOS or LMS takes 4–7 months. Full platforms take 6–10 months. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We build checkout integrations, instant decisions, instalment schedules, merchant settlement and dispute flows. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
We configure products, fees, rate caps and disclosures by state, so compliance changes do not need code changes. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We integrate Experian, Equifax and TransUnion along with cash-flow data from Plaid, MX or Finicity. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We migrate loans in stages, run old and new systems in parallel and reconcile balances before cutover. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We build KYB onboarding, cash-flow underwriting, lines of credit and revenue-based financing. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
You or your bank partner hold the licence. We build software that supports your compliance programme. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Plan your next build with our team

Talk to a Lending Software Architect Share your loan products, states and volume. We return an architecture recommendation and cost range within 48 hours. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Explore our work across 10 capability areas, from AI integrations and intelligent agents to web platforms, mobile apps, SaaS products, and cloud solutions. 20 projects are published as case studies.
50+Team Members
100+Projects Delivered
40+Happy Clients
12+Industries Served
30+Technologies
10+Countries Reached
20+Technical Specialists
35+AI Projects
25+Products Launched
20Published Case Studies

Share your scope

Tell us about the workflow or product. A solutions architect replies within one business day.

4 + 8 =