Neobank App Development for Digital Banks Built on Trust

THE TISA builds neobank apps for US founders and brands launching digital banking through a sponsor bank. We develop the mobile app, ledger, card programme, onboarding and partner compliance tooling that a bank partner needs to say yes. Accounts, debit cards, early direct deposit, savings and credit-building in one app your customers can trust with their paycheck. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Neobank App Development
  • CampusFlow — THE TISACampusFlow
  • EZSKU — THE TISAEZSKU
  • Group Hotel Index — THE TISAGroup Hotel Index
  • LockYantra — THE TISALockYantra
  • Narsik Logistics — THE TISANarsik Logistics
  • OpsPilot — THE TISAOpsPilot
  • Ratiwal — THE TISARatiwal
  • Speakify — THE TISASpeakify
  • 50+Team Members
  • 100+Projects Delivered
  • 40+Happy Clients
  • 12+Industries Served
  • 30+Technologies
  • 10+Countries Reached
  • 20+Technical Specialists
  • 35+AI Projects
  • 25+Products Launched
  • 20Published Case Studies

What Is a Neobank
for your team?

A neobank is a digital-only financial company that offers bank-like accounts through an app. In the US, most neobanks are not chartered banks. They partner with an FDIC-insured sponsor bank that holds deposits, often through a banking-as-a-service (BaaS) provider. The neobank owns the customer experience, brand and product, while the bank holds the licence and regulatory responsibility.

Neobank Products We Build
for this product

The neobank app development products in this section are Consumer Checking and Spending Accounts, Early Wage Access and Early Direct Deposit, Savings and High-Yield Accounts, Credit-Builder Products, SMB and Freelancer Banking, Niche Neobanks. Each product covers the customer flow, the records behind it, and the checks that have to be ready before release.

Consumer Checking and Spending Accounts

Mobile accounts with debit cards, direct deposit and fee-free features. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Early Wage Access and Early Direct Deposit

Paycheck up to two days early and earned wage access products . We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Savings and High-Yield Accounts

Round-ups, goals and automated saving rules. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Credit-Builder Products

Secured cards and credit-builder loans that report to bureaus. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Lending software development

SMB and Freelancer Banking

Business accounts, invoicing, tax set-aside and expense cards. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Niche Neobanks

Banking for creators, gig workers, immigrants, teens with parental controls, or specific communities. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Build Path: BaaS, Direct Sponsor
Bank or Charter

After the 2024 Synapse bankruptcy and the enforcement actions against several sponsor banks, partners now expect stronger ledgers, reconciliation and compliance from programme managers. We build for that standard from day one.

Build Path: BaaS, Direct Sponsor Bank or Charter
PathBest forTimelineTypical cost (USD)
Time to launchSoftware cost (USD)BaaS platform with a sponsor bankMost new neobanks
5–8 months200,000Direct sponsor bank integrationFunded neobanks wanting control and lower unit costs
8–14 months400,000Own charterLate-stage neobanks

The Neobank Engine
for this product

Per-customer ledger reconciled to the bank. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Card programme integration

Issuer processor integration for authorisations, holds, clearing and disputes, with real-time balance checks. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Direct deposit and early pay

Payroll switching, early deposit logic and risk limits on advance credits. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Partner oversight tooling

Dashboards and reports your sponsor bank uses to monitor KYC, transactions, complaints and risk. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Failures handled, not hidden

Processor outages, returned deposits and disputed transactions follow defined ledger paths and user messages. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Neobank App Features
for this product

Features for neobank app development are grouped by who uses them: Customer App, Operations and Compliance Console. Each group is the set of screens and actions that role needs in the finished product.

Customer App

  • Five-minute account opening with KYC
  • Virtual card instantly; physical card shipping and activation
  • Apple Pay and Google Pay
  • Direct deposit switching and early pay
  • Fee-free overdraft buffer
  • P2P transfers and bill pay
  • Savings goals and round-ups
  • Credit-builder and credit score tracking
  • Spending insights and budgets
  • Card lock, limits and dispute flow
  • 24/7 chat support with AI and human agents

Operations and Compliance Console

  • KYC review and document checks
  • AML monitoring and case management
  • Complaint tracking
  • Card and account management
  • Ledger and reconciliation reports
  • Partner bank reporting

Build a Neobank App Like Chime,
Current or Varo

These names describe the product type for neobank app development, not a client list: Like Chime, Like Current, Like Varo, Like Dave, Like Revolut, Like Mercury or Novo. They show the shape of the product. This page does not use those brands' logos or claim that we built their apps.

These names describe the product type only. This page does not use those brands' logos or visual identity. They are here so you can compare the product shape, not as a claim that we built those companies' apps.

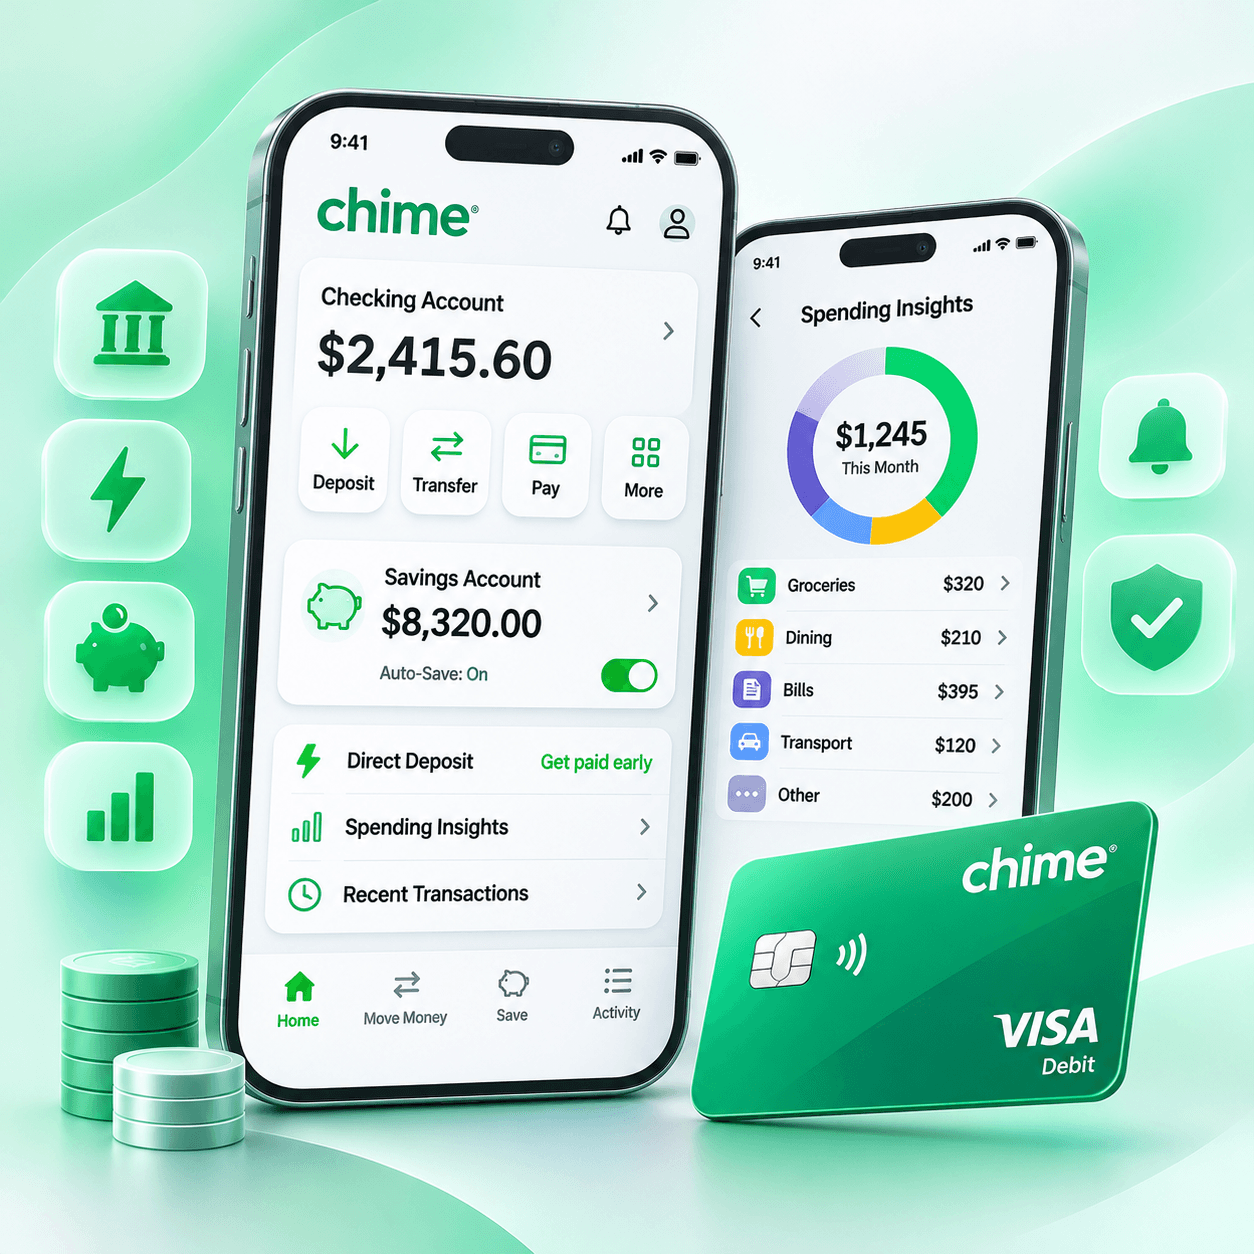
Like Chime

A mobile-first spending app of this type offers everyday checking and savings through a sponsor bank, with early direct deposit where the bank supports it, alerts, and simple savings tools. There is no branch workflow. The ledger reconciles to the bank each day, and the customer sees pending and posted money separately. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a digital banking app with checking, savings, and a debit card

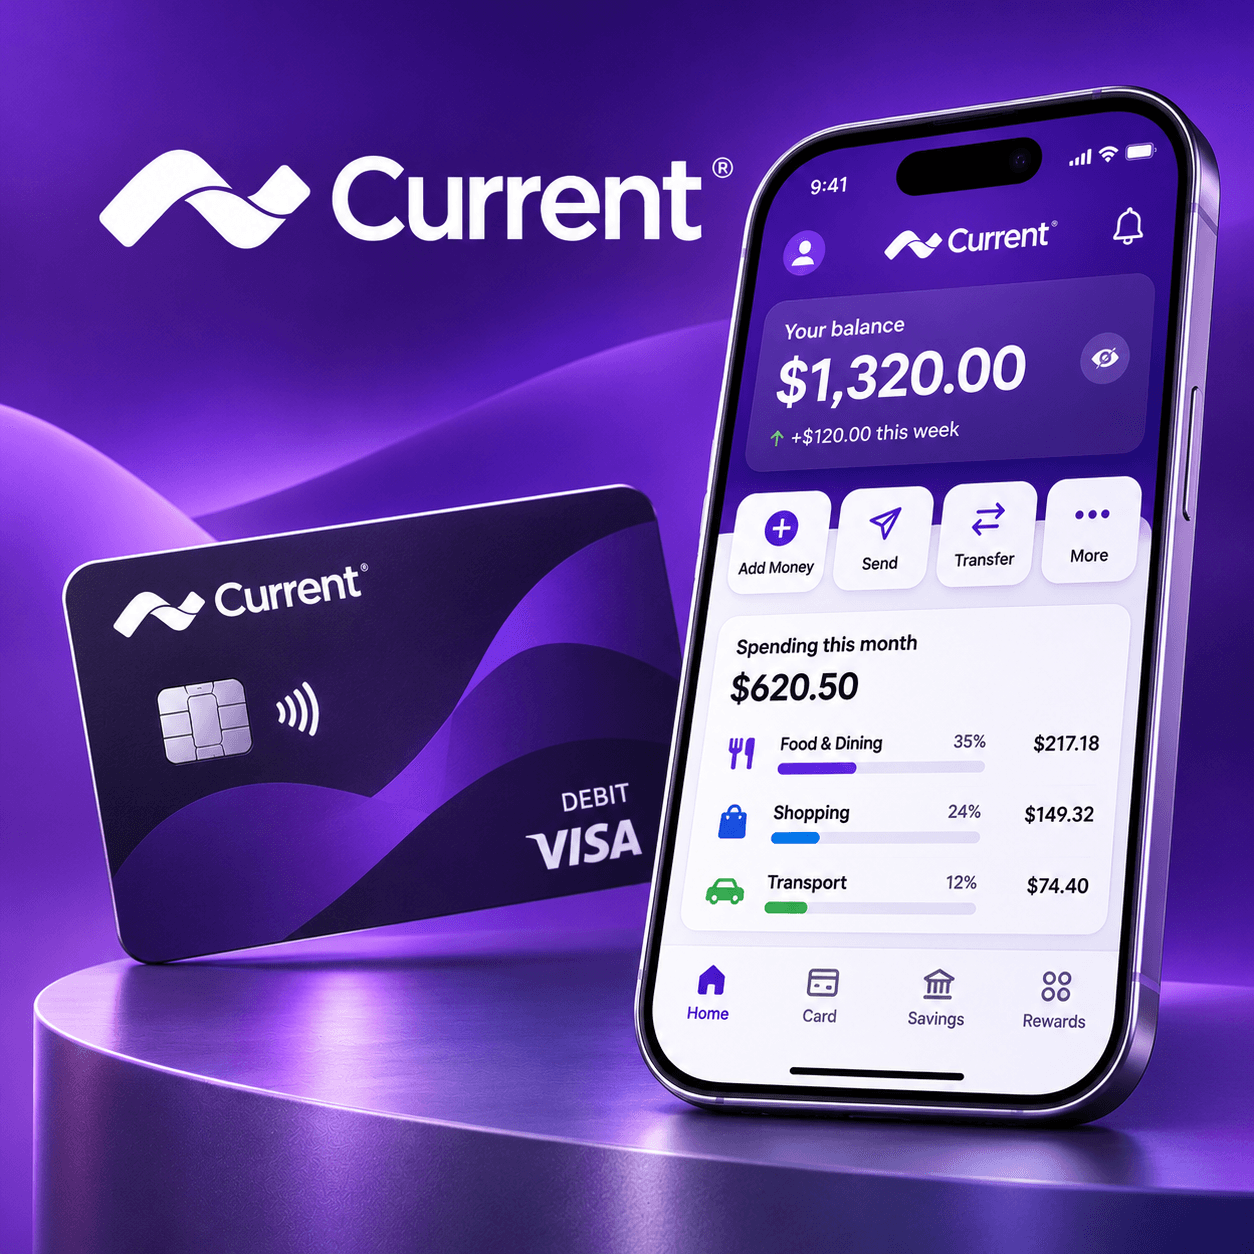
Like Current

A neobank app of this type offers spending accounts for teens and adults, with faster deposits where the sponsor bank allows them, card controls, and alerts parents or the account owner can act on. The teen account and the adult account do not share a balance. Funds reconcile to the bank. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a neobank app with a balance, debit card, and savings

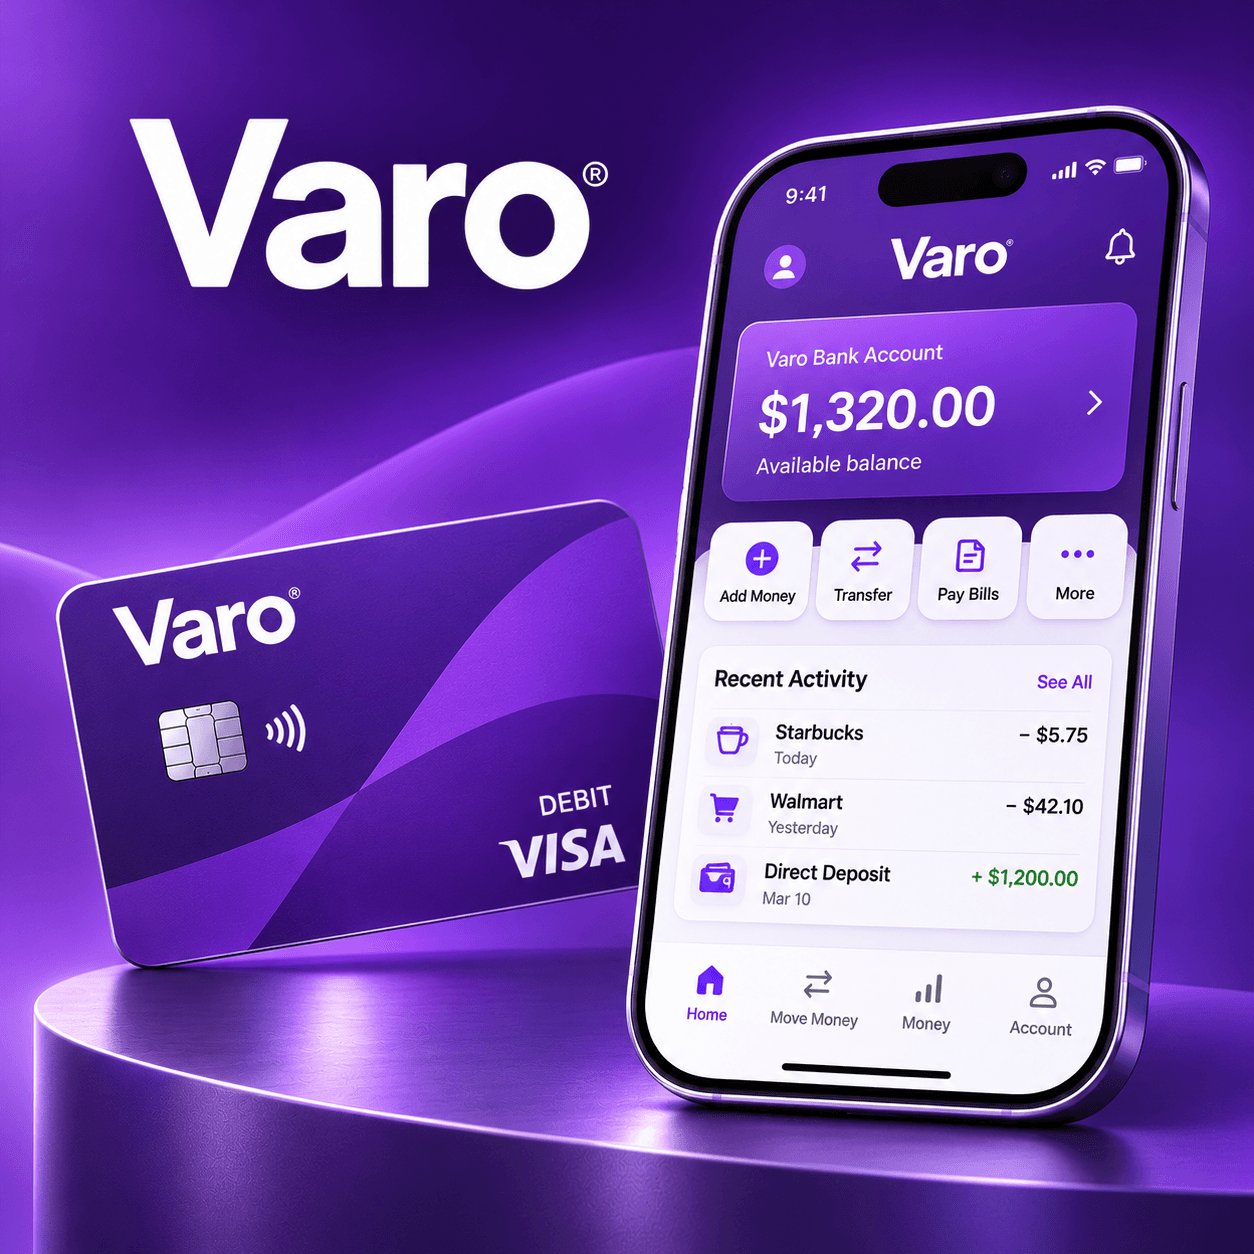
Like Varo

A savings-led banking app of this type makes the savings balance as visible as spending, and can offer a small cash advance only inside the rules of the bank partner. Round-ups and goals move money between those balances with a record of each transfer. Advances are a separate amount owed, not a silent overdraft. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a neobank app with checking, savings, and a debit card

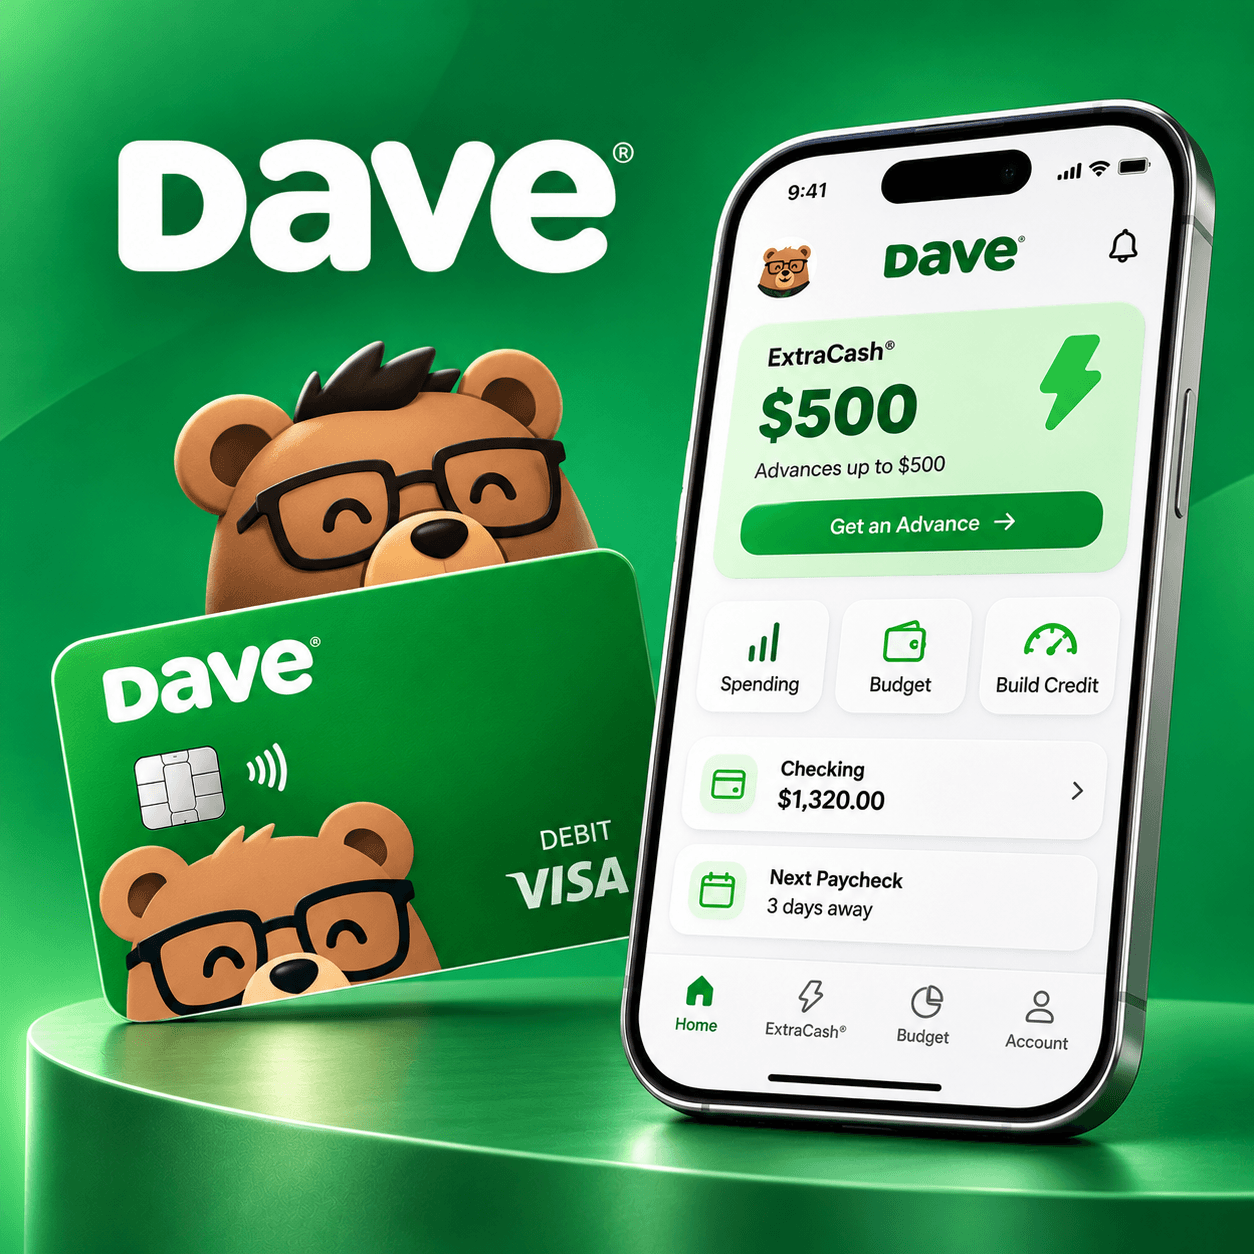
Like Dave

A cash-advance app of this type shows a small advance against expected income and pairs it with tools that look at side income or bills. The advance amount, the fee, and the repayment date are shown before the customer accepts. Repayment is tracked as its own balance. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a neobank app with a debit card, balance, and cash advance

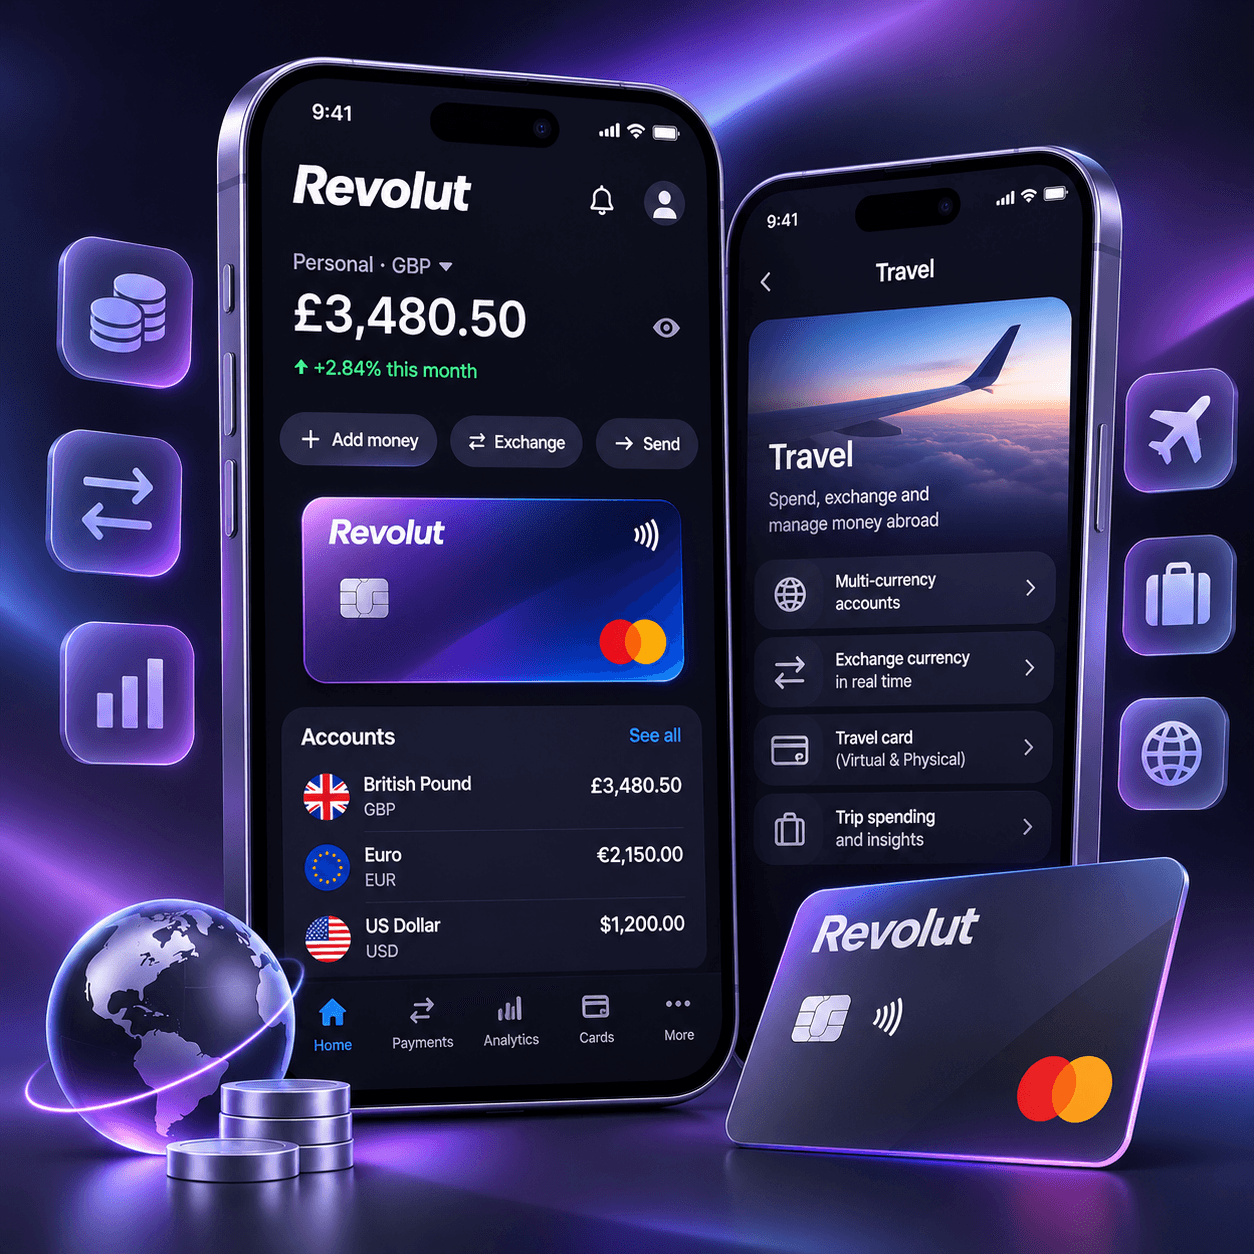
Like Revolut

A multi-currency wallet of this type combines spending, cards, and budgets, with extra products added only when a partner is allowed to offer them. People hold more than one currency, freeze a card, and see spending by category. Each added product, such as savings or trading, keeps its own balance and disclosures. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a multi-currency banking app with transfers, cards, and spending tools

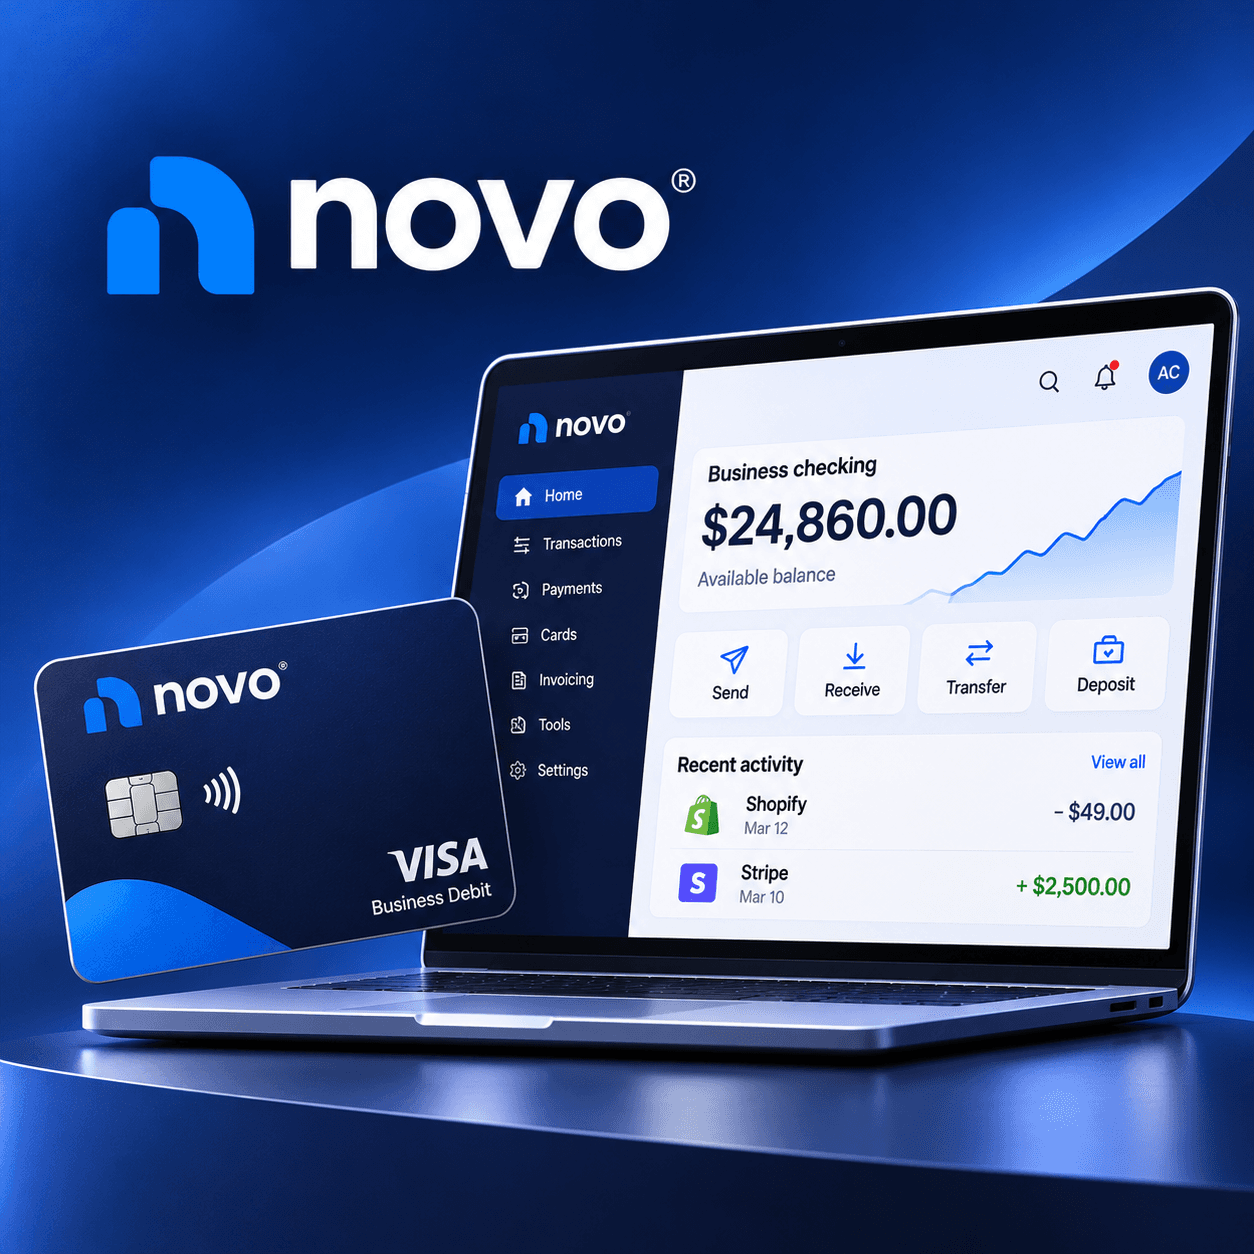
Like Mercury or Novo

A startup banking app of this type gives a company accounts, team cards, and transfers with an approval step before money leaves. The owner can see which teammate spent on a card and which bill was scheduled. An API or export lets the accountant read the same transactions without a second set of books. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a business banking dashboard with accounts, cards, and transfers

Neobank Integrations we cover
for this product

Integrations for neobank app development cover BaaS and sponsor banks, Card issuing, KYC and fraud, Bank linking, Payroll and direct deposit switching, Credit reporting, Support. Each connection uses a documented interface, stores the response, and reconciles it against the product record.

BaaS and sponsor banks

BaaS platforms and sponsor banks

Card issuing

  • Marqeta
  • Lithic
  • Galileo

KYC and fraud

  • Alloy
  • Socure
  • Persona
  • Sardine

Bank linking

  • Plaid
  • MX

Payroll and direct deposit switching

  • Atomic
  • Pinwheel
  • Argyle

Credit reporting

Credit bureau reporting via furnishing partners

Support

  • Zendesk
  • Intercom

Neobank Compliance we cover
for this product

Compliance for neobank app development covers Sponsor bank programme requirements, BSA/AML, CIP and CDD, FDIC deposit insurance rules and Part 328 signage, Recordkeeping for custodial accounts, Regulation E, Regulation DD, UDAAP, PCI DSS v4.0.1. Each control is built into the software, and the product keeps the evidence a reviewer can ask for later.

Neobank Compliance we cover for this product
RequirementApplies toHow we build for it
Sponsor bank programme requirementsAll BaaS programmesOversight reports, approvals for marketing and product changes
BSA/AML, CIP and CDDAccount opening and monitoringKYC, beneficial ownership for business accounts, alerts and SAR support
FDIC deposit insurance rules and Part 328 signageMarketing and disclosuresCorrect "banking services provided by" language and pass-through insurance disclosures
Recordkeeping for custodial accountsFBO structuresPer-customer records that support pass-through insurance
Regulation E, Regulation DDTransfers and deposit accountsDisputes, disclosures and fee transparency
UDAAPAll consumer productsPlain-language fees and honest marketing
PCI DSS v4.0.1Card dataProvider-hosted card data and tokenisation

General information, not legal advice. Confirm your obligations with qualified counsel. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
AI in Neobanks
for this product

AI in neobank app development covers Support assistant, Fraud and ATO detection, Cash advance risk, Financial coaching. The model scores or drafts, a person can still review the result, and the product keeps a record of what happened.

AI in Neobanks for this product
AI featureWhat it doesHuman control
Support assistantResolves common questions instantlyDisputes and complaints go to people
Fraud and ATO detectionSpots risky logins and paymentsStep-up before blocking. AI fraud detection
Cash advance riskDecides advance limitsPolicy limits and adverse action reasons
Financial coachingSuggests savings and budgetsUsers opt in

Showcasing published work and
fintech excellence from shipped products

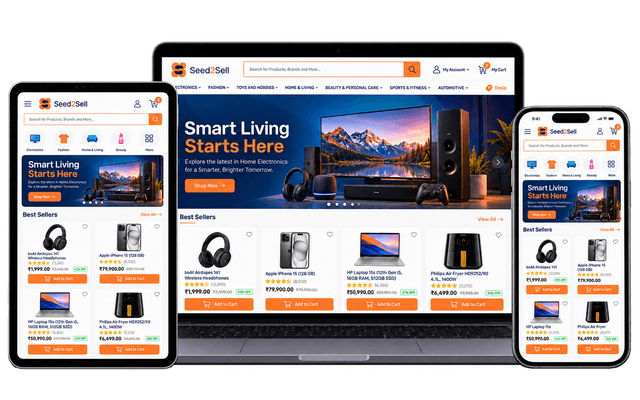
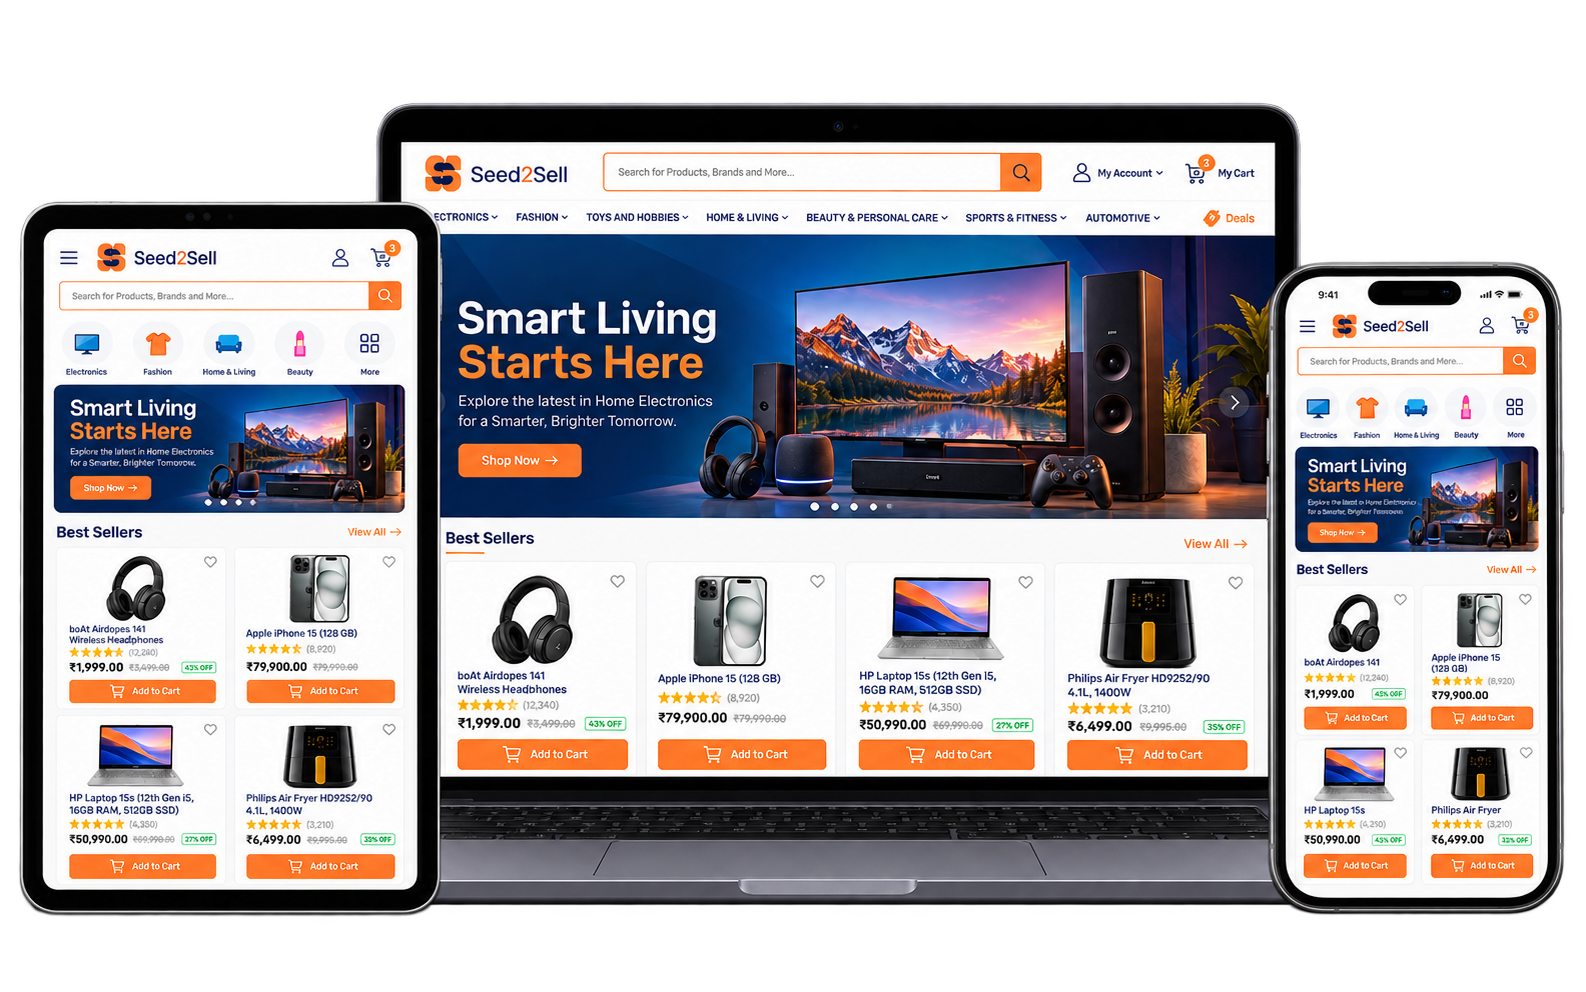
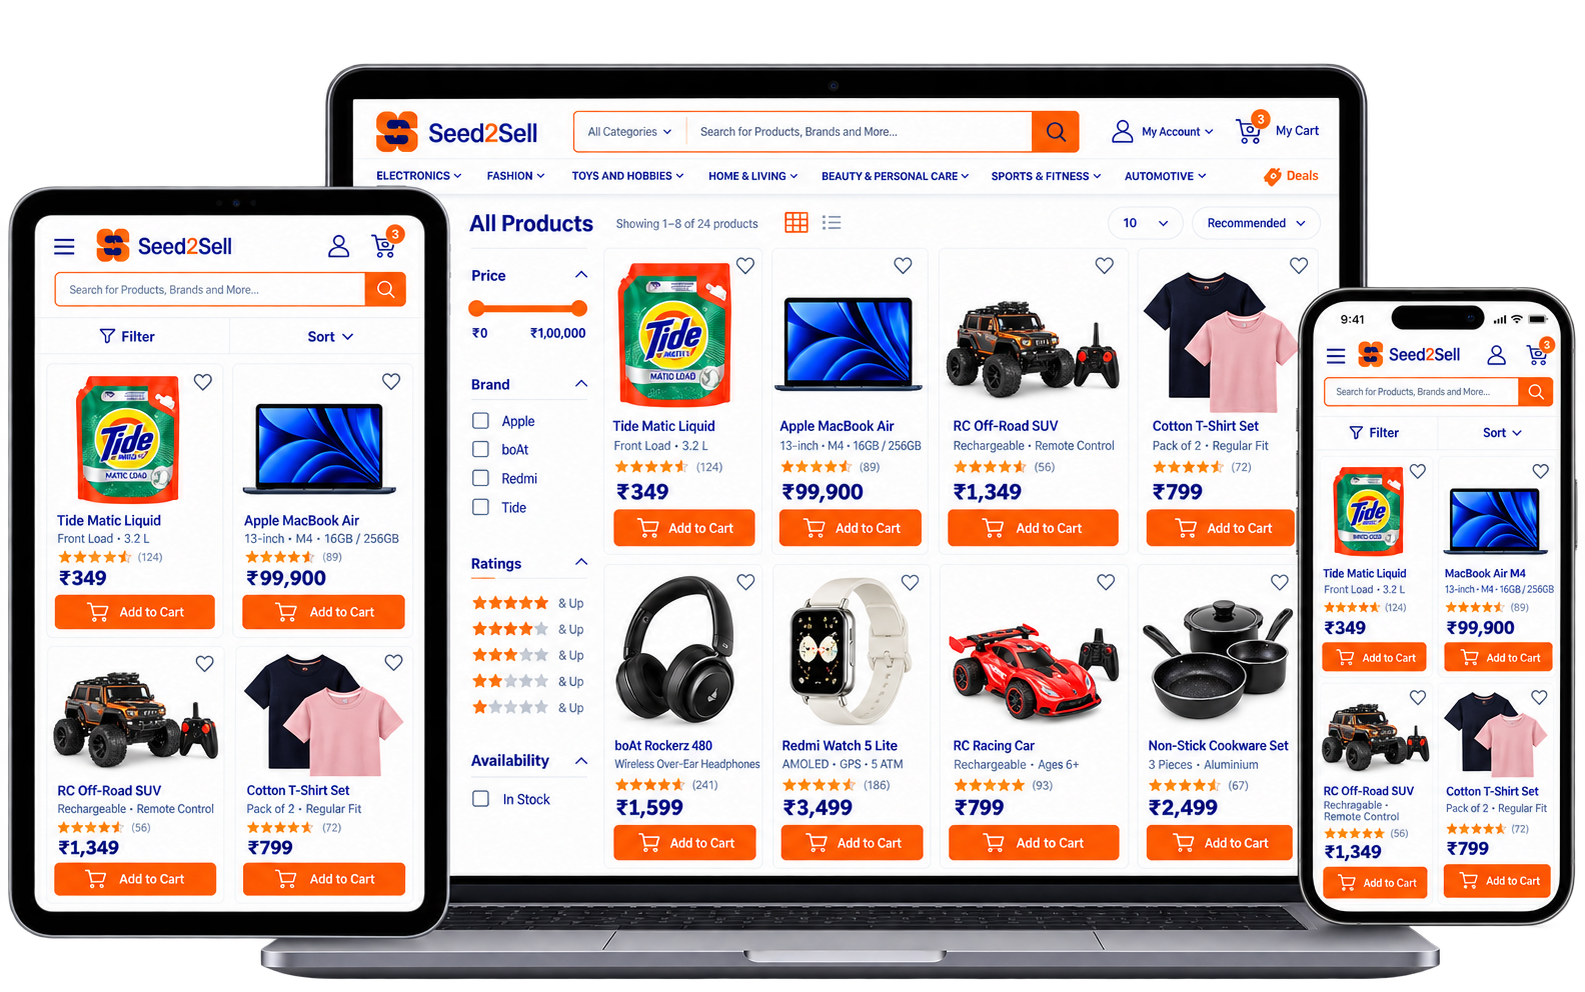
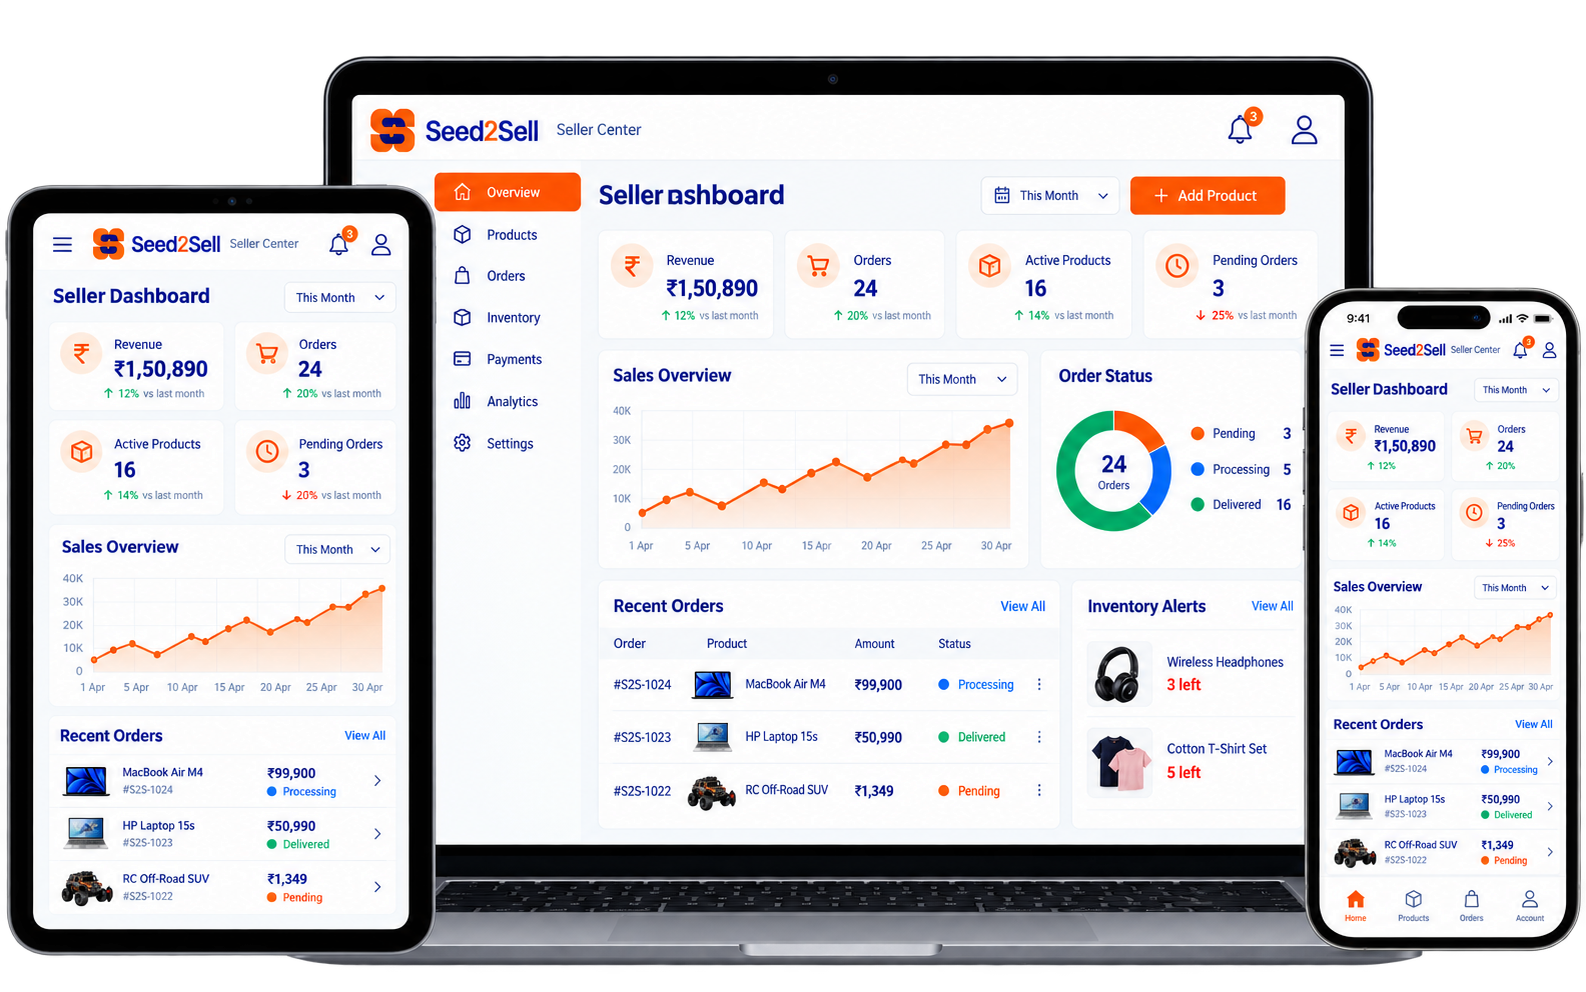
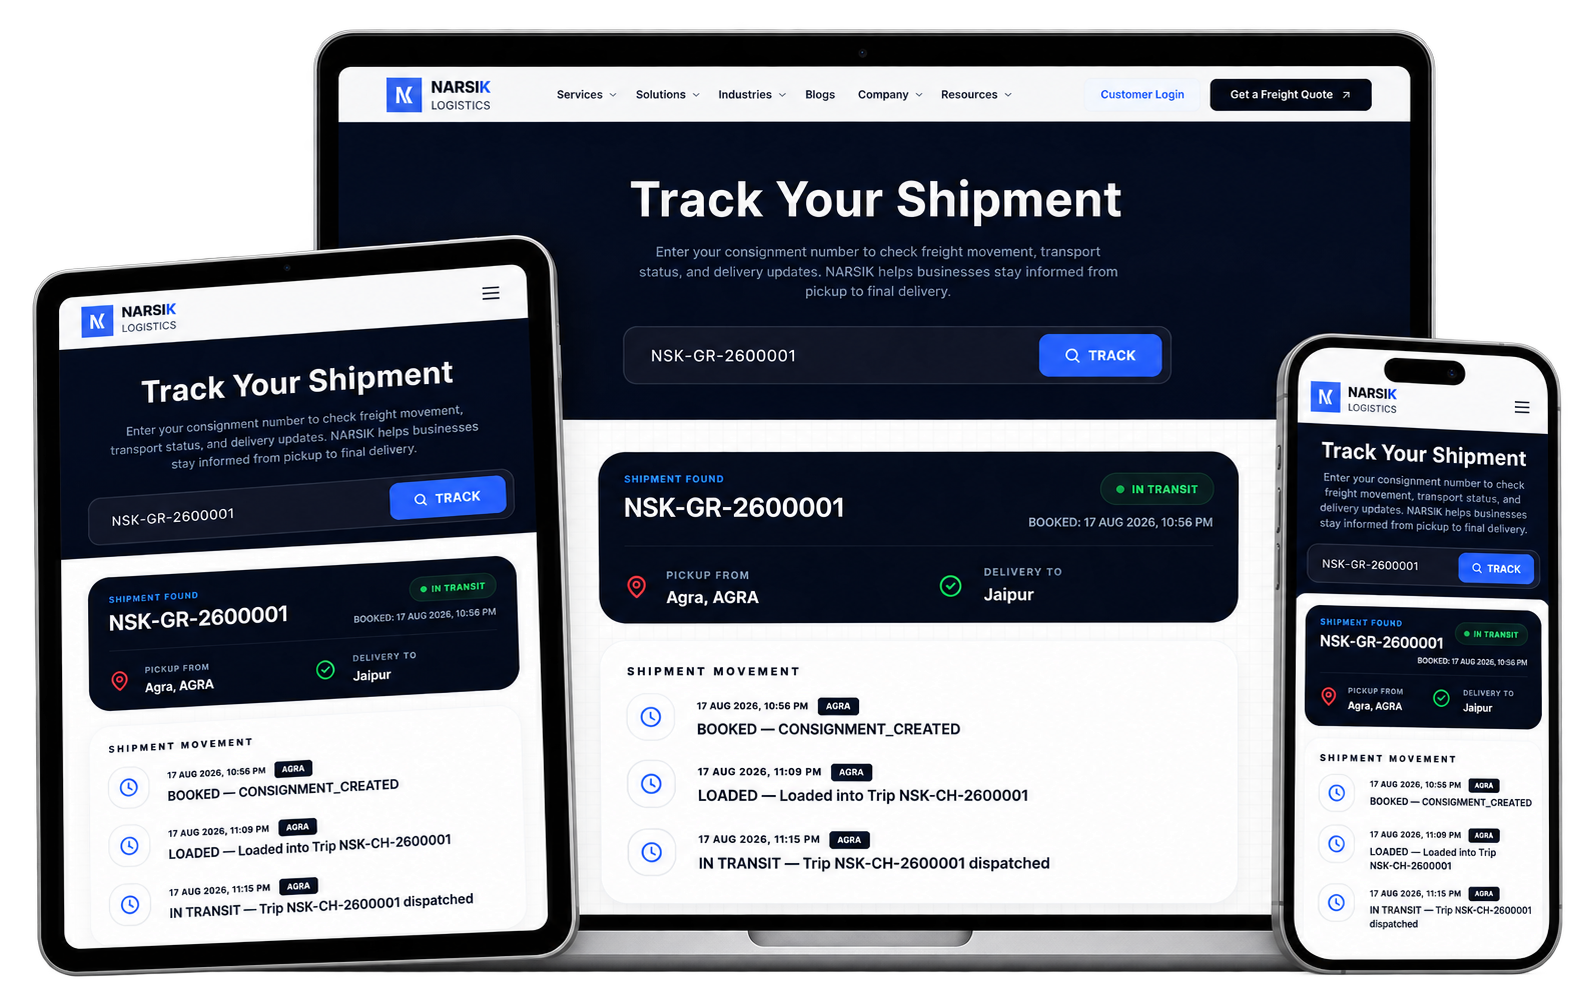
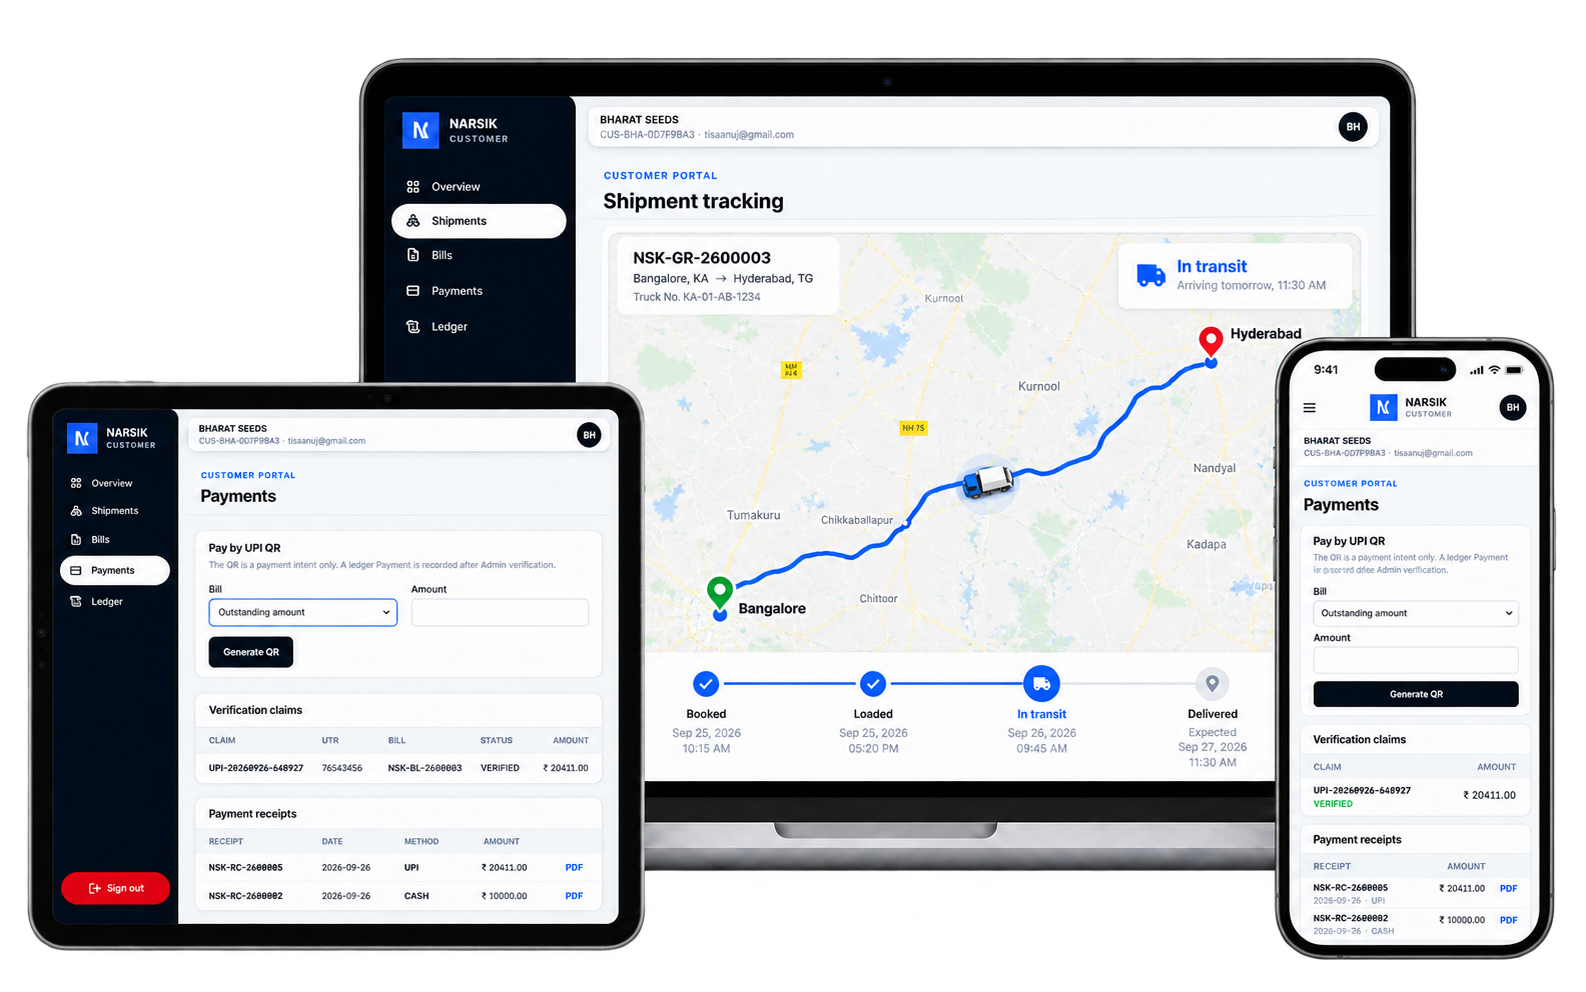
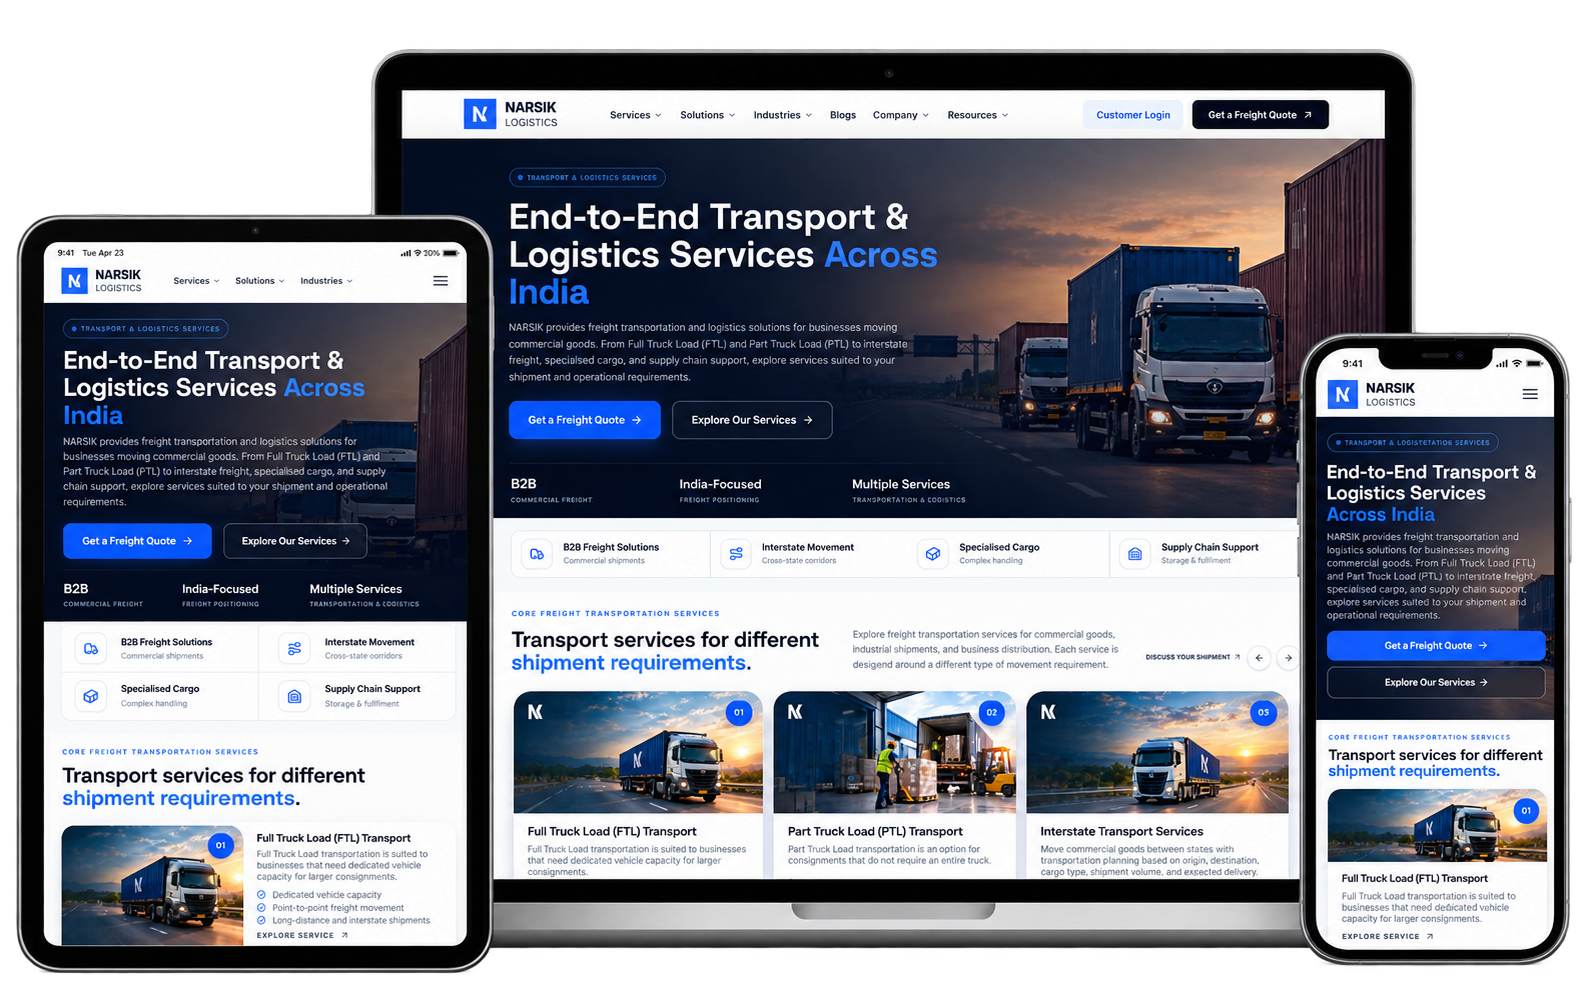
These are published case studies that include money movement, orders or billing. Seed2Sell covers a B2B marketplace with payment and OTP checks. Narsik Logistics covers freight booking and tracking. A payments, wallet or lending case study will be added here when it is published.

Seed2Sell marketplace home

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

Seed2Sell product list

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

Seed2Sell seller dashboard

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

Narsik Logistics shipment tracking

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Narsik Logistics customer portal

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Narsik Logistics services

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Explore all case studies

How Much Does Neobank
App Development Cost?

A neobank app costs $90,000 to $400,000 in software. BaaS fees, card programme costs and compliance staff come on top. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.

How Much Does Neobank App Development Cost?
ProductCost (USD)Timeline
Neobank scopeMVP: account, debit card, transfers150,000
5–7 monthsFull consumer neobank250,000
7–10 monthsDirect sponsor bank integration with own ledger400,000

Process we follow
for this product

The neobank app development build moves through 1. Product and economics model (interchange, fees, unit costs), 2. Partner selection and due diligence support, 3. Ledger and reconciliation design, 4. Compliance programme alignment with the bank, 5. Build, test and partner review, 6. Closed beta, then phased public launch. Each step ends with a written outcome and a handoff, so the next step starts from an agreed scope.

  1. 01

    Product and economics model (interchange, fees, unit costs)

  2. 02

    Partner selection and due diligence support

  3. 03

    Ledger and reconciliation design

  4. 04

    Compliance programme alignment with the bank

  5. 05

    Build, test and partner review

  6. 06

    Closed beta, then phased public launch

These stages sit inside the studio software development process. The chart is the order for this product. The linked page explains how a build moves from discovery through release and handover.

See the development process

Tech Stack we use
for this product

Swift, Kotlin, Flutter · Node.js, Go, Java · PostgreSQL, Kafka · AWS · OpenAI and Claude for support. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Swift
Kotlin
Flutter
Node.js
Go
Java
PostgreSQL
AWS
OpenAI
Claude

Why Choose THE TISA for
Neobank App Development

Teams hire THE TISA for neobank app development because one team owns the product, the integrations and the evidence. You receive the code, the records and a launch handover when the build is done.

  • Per-customer reconciliation against the bank's records
  • Partner-ready compliance tooling sponsor banks ask for
  • Card, deposit and ledger experience in one team
  • Consumer-grade UX with transparent fees
  • Full IP ownership

Related Fintech Services
for this product

Pages related to neobank app development include Banking software development. Open the one that matches the next part of the product, or return to the fintech hub for the full list.

Banking Software and Website Development

Online banking portals, customer onboarding websites, internal banking dashboards and integrations with core banking systems for banks, credit unions and digital lenders, connected to the core system you already run today.

Explore Service

fintech software development services

What they say about working with THE TISA

The Seed2Sell team, and other founders we have shipped with, on the work itself. These notes come from published case studies and from founders whose products we built, not from a rating we have not verified.

We really appreciate the TISA team. They are hardworking, committed, and clear about our needs. They built a platform that works well today and will grow with us in the future.

THE TISA demonstrated excellent project management, clear communication, and a highly professional approach throughout our collaboration. They delivered the project on time and exceeded our expectations with outstanding results.

Parmeshwar Kumawat

Founder & CEO, NARSIK Logistics

Parmeshwar Kumawat

THE TISA helped us build a reliable e-commerce operations platform with clean workflows, strong delivery, and a product foundation ready to scale.

Sam Patel

Founder, EZSKU

Sam Patel

The student portal gave us a structured platform to manage learning, operations, reporting, and AI-powered student support from one system.

Albert Joe

Product Owner, Education Technology Platform

Albert Joe

THE TISA delivered a scalable hotel platform with strong architecture, complex backend logic, and a performance-focused execution process.

Luke Thompson

Founder, Group Hotel Index

Luke Thompson

The platform helped us shape a modern multilingual learning experience with a clear product structure and dependable technical execution.

Abdul Aziz Sudais

Director, Global Language Center

Abdul Aziz Sudais

More of the same work is written up in the case studies, and the public reviews sit on Clutch and GoodFirms.

Frequently asked questions about
this fintech service

Answers on cost, timelines, licences and compliance for neobank app development. The same questions and answers are in the page text and in the structured data, so a reader can find them without opening the accordion.

Software costs $90,000 to $400,000. An MVP costs 150,000. BaaS, card and compliance costs are extra. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
No, most US neobanks partner with an FDIC-insured sponsor bank. The bank holds the charter and deposits. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
BaaS lets non-banks offer bank accounts and cards through a licensed bank's infrastructure via APIs. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Mainly from debit card interchange, plus subscriptions, cash-advance tips or fees, lending and partner products. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
On a BaaS platform, 5–8 months. With direct sponsor bank integration, 8–14 months. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Banks now demand accurate per-customer ledgers, daily reconciliation and stronger oversight of fintech partners. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Only with accurate language naming the sponsor bank and explaining pass-through insurance. Your partner and counsel must approve it. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We build KYB onboarding, multi-user access, cards, invoicing and accounting sync. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes, with a lending partner and bureau reporting. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We prepare architecture, security and compliance documentation for partner reviews. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Plan your next build with our team

Plan Your Neobank Tell us your audience, products and partners. We reply within one business day with a launch plan and cost range. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Explore our work across 10 capability areas, from AI integrations and intelligent agents to web platforms, mobile apps, SaaS products, and cloud solutions. 20 projects are published as case studies.
50+Team Members
100+Projects Delivered
40+Happy Clients
12+Industries Served
30+Technologies
10+Countries Reached
20+Technical Specialists
35+AI Projects
25+Products Launched
20Published Case Studies

Share your scope

Tell us about the workflow or product. A solutions architect replies within one business day.

4 + 5 =