Banking Software Development for Banks, Credit Unions and Digital Banks

THE TISA is a banking software development company that helps US community banks, credit unions and digital banks launch modern digital banking without risky big-bang replacements. We build online and mobile banking, account opening, business banking portals and integration layers on top of FIS, Fiserv and Jack Henry cores. Your members get a modern experience. Your core keeps running. Your examiners see controls they recognise. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Banking Software Development
  • CampusFlow — THE TISACampusFlow
  • EZSKU — THE TISAEZSKU
  • Group Hotel Index — THE TISAGroup Hotel Index
  • LockYantra — THE TISALockYantra
  • Narsik Logistics — THE TISANarsik Logistics
  • OpsPilot — THE TISAOpsPilot
  • Ratiwal — THE TISARatiwal
  • Speakify — THE TISASpeakify
  • 50+Team Members
  • 100+Projects Delivered
  • 40+Happy Clients
  • 12+Industries Served
  • 30+Technologies
  • 10+Countries Reached
  • 20+Technical Specialists
  • 35+AI Projects
  • 25+Products Launched
  • 20Published Case Studies

What Is Banking Software Development
for your team?

Banking software development is building the systems banks use to open accounts, hold deposits, move money, lend and serve customers. It includes the core banking system that keeps the account ledger, the digital banking channels on top of it, and the integration layer that connects cores to payment rails, fintech partners and data. Most US banks modernise by adding a digital layer and APIs around the core before replacing the core itself.

Banking Software We Build
for this product

The banking software development products in this section are Digital Banking Platforms, Digital Account Opening, Business and Commercial Banking Portals, Core Banking Integration and Modernisation, Banking-as-a-Service Platforms for Sponsor Banks, Branch and Teller Systems, Banking Data and Analytics. Each product covers the customer flow, the records behind it, and the checks that have to be ready before release.

Digital Banking Platforms

Online and mobile banking with balances, transfers, bill pay, Zelle access , card controls, statements and alerts. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Digital Account Opening

Consumer and business account opening in under ten minutes with KYC, KYB, funding and e-signature. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Business and Commercial Banking Portals

Multi-user access, approvals, ACH and wire origination, positive pay and cash management reporting. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Core Banking Integration and Modernisation

API layers, event streaming and data sync around legacy cores; staged migration to cloud-native cores when you are ready. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Banking-as-a-Service Platforms for Sponsor Banks

Partner onboarding, programme management, FBO ledgers, partner oversight dashboards and compliance reporting. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Branch and Teller Systems

Staff-facing dashboards for customer service, account maintenance and case management. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Banking Data and Analytics

Customer 360, deposit analytics and regulatory reporting data pipelines. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Modernisation Path: Wrap,
Extend or Replace

We favour progressive modernisation. Each phase delivers value and lowers risk before the next one starts. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Modernisation Path: Wrap, Extend or Replace
PathBest forTimelineTypical cost (USD)
Wrap: digital channels and APIs on your current coreCommunity banks and credit unions improving experience fast4–8 months$300,000
Extend: side-car core for new productsBanks launching a digital brand or BaaS programme6–12 months$500,000
Replace: core migration in stagesBanks retiring a legacy core12–36 months$500,000+

The Banking Engine
for this product

Integration layer around the core. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Account and transaction consistency

Digital channels read from the core of record or a reconciled cache. Balances shown to customers always tie to the core. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Payments hub

One service for ACH, wires (Fedwire in ISO 20022 since July 2025), RTP, FedNow and card transactions with consistent statuses. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Entitlements and approvals

Role-based permissions, dual control and approval limits for business banking and staff tools. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Failures handled, not hidden

Core downtime, batch windows and payment exceptions have defined fallbacks, customer messages and staff alerts. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Banking Software Features
for this product

Features for banking software development are grouped by who uses them: Retail Customers, Business Customers, Bank Staff. Each group is the set of screens and actions that role needs in the finished product.

Retail Customers

  • Account opening with ID verification and instant funding
  • Balances, transactions and e-statements
  • Internal, external and P2P transfers
  • Bill pay and mobile check deposit
  • Card controls, travel notices and card replacement
  • Alerts, budgets and savings goals
  • Secure messaging and video support

Business Customers

  • Multiple users with roles and approvals
  • ACH and wire origination
  • Positive pay and fraud alerts
  • Cash position and reporting
  • Accounting integrations

Bank Staff

  • Customer 360 view
  • KYC and BSA case management
  • Account maintenance and disputes
  • Product and fee configuration
  • Audit logs for examiners

Build Digital Banking Like Chase, Capital
One or SoFi

These names describe the product type for banking software development, not a client list: Like the Chase app, Like Capital One, Like SoFi, Like Mercury, Like Chime. They show the shape of the product. This page does not use those brands' logos or claim that we built their apps.

These names describe the product type only. This page does not use those brands' logos or visual identity. They are here so you can compare the product shape, not as a claim that we built those companies' apps.

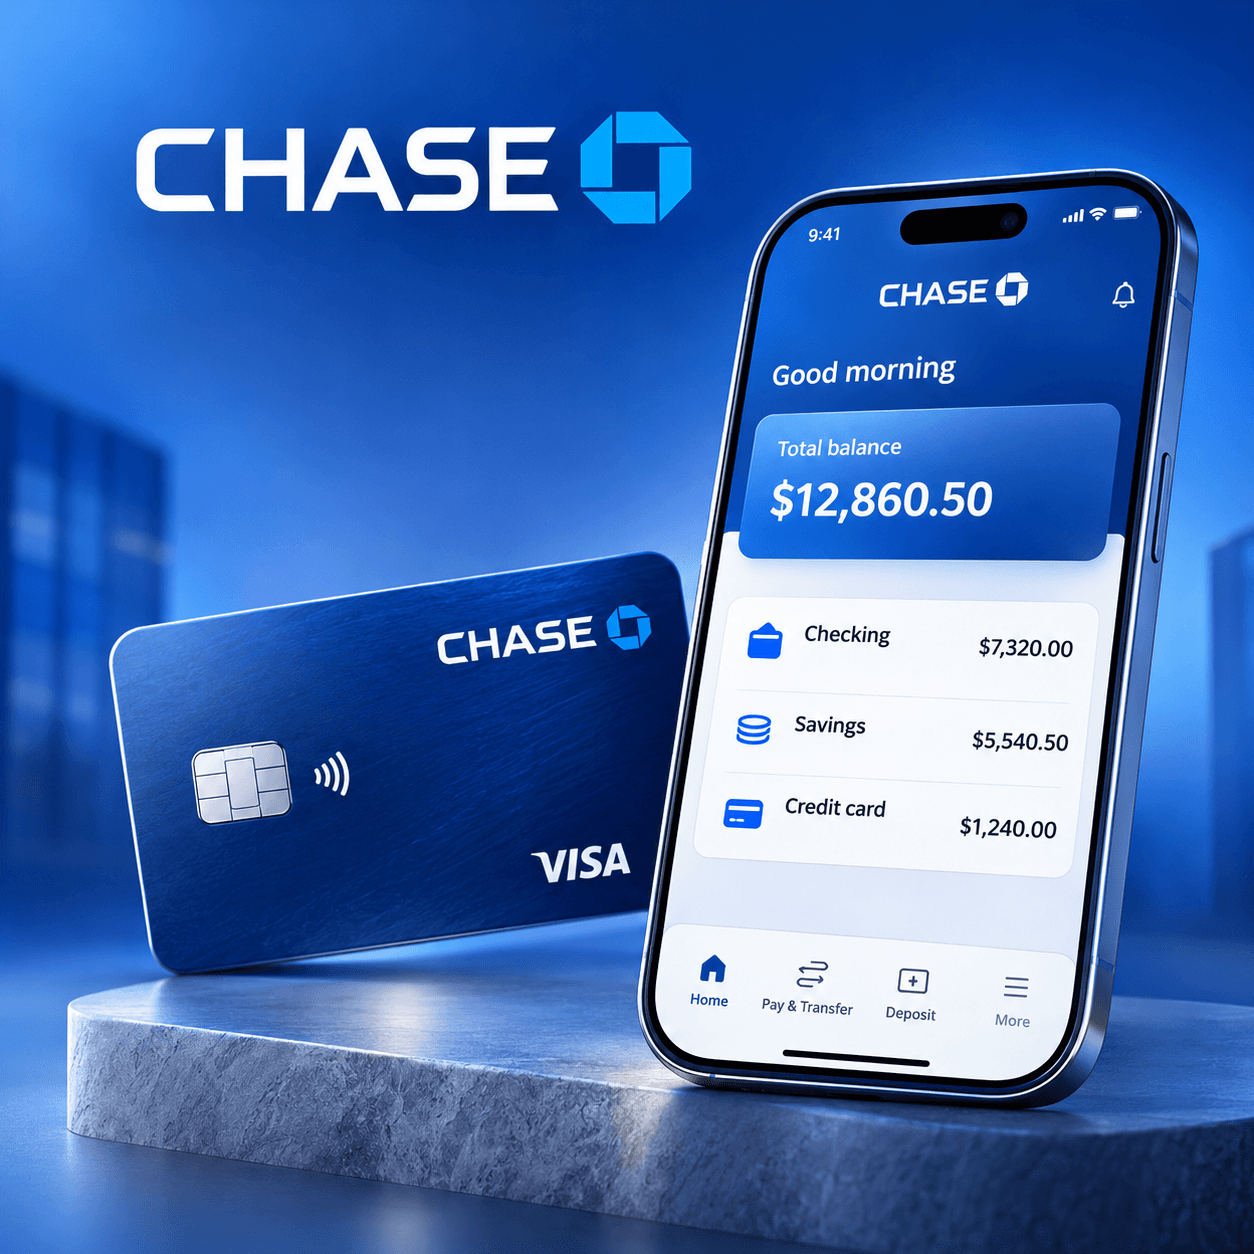
Like the Chase app

A retail banking app of this type covers everyday accounts, card controls, transfers, bill pay, and statements in one mobile experience. People lock a card, set a limit, and see a pending charge before it posts. The core or sponsor bank remains the system of record, and the app shows that record. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a mobile banking app with accounts, transfers, and a debit card

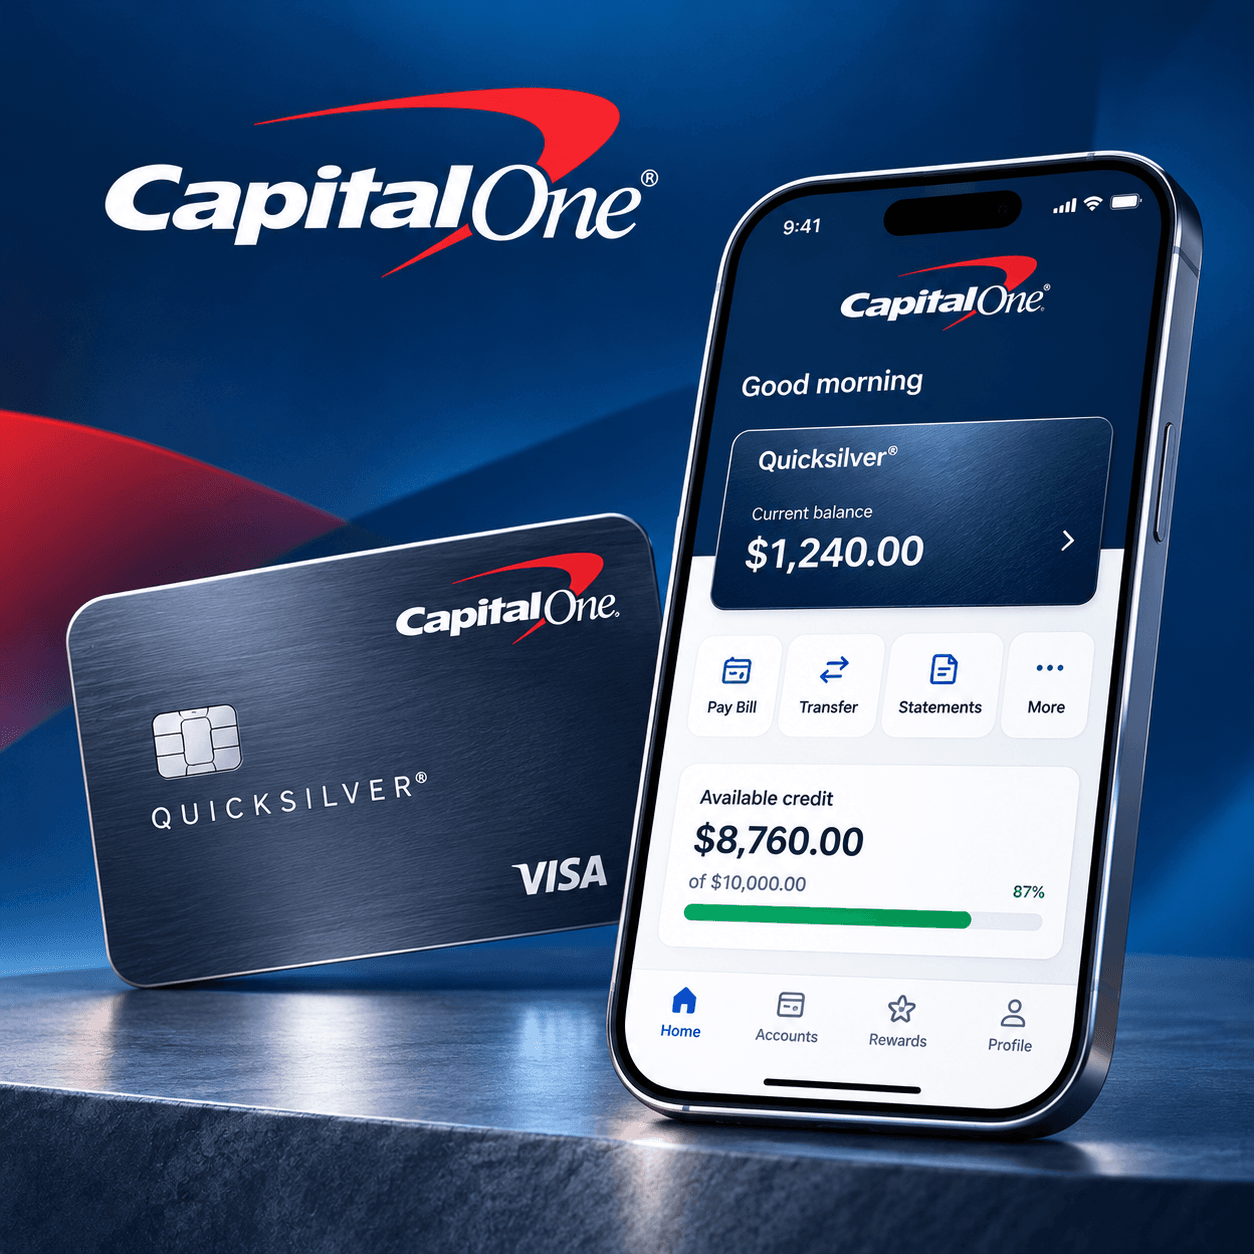
Like Capital One

A digital-first bank app of this type opens accounts on the phone, then stays useful with alerts, spending insights, and card management. Identity checks finish before the account is live. Customers can see why a transaction was flagged, and the bank keeps the application file for a later review. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a card and banking app with a balance, rewards, and payments

Like SoFi

A combined finance app of this type holds banking, lending, and investing in one login, with a clear line between each balance. A payment to a loan is not the same record as a deposit to spending. Each product still has its own disclosures, and the customer can see which balance changed. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a consumer finance app with banking, investing, and a debit card

Like Mercury

A business banking app of this type is built for startups and small companies that live in software. It covers accounts, cards for the team, approvals before a payment leaves, and an API so the company's books can read the transactions. Every payout names who approved it. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Mockup of a business banking dashboard with accounts, cards, and payments

Like Chime

A mobile-first spending app of this type offers everyday checking and savings through a sponsor bank, with early direct deposit where the bank supports it, alerts, and simple savings tools. There is no branch workflow. The ledger reconciles to the bank each day, and the customer sees pending and posted money separately. The work is custom software you own, with the records and handover your team needs before launch. The familiar name describes the product type only.

Related service
Mockup of a digital banking app with checking, savings, and a debit card

Banking Integrations we cover
for this product

Integrations for banking software development cover Core banking systems, Payment rails, Card processing, Identity and KYC, Data aggregation, Digital channels, CRM. Each connection uses a documented interface, stores the response, and reconciles it against the product record.

Core banking systems

  • FIS
  • Fiserv
  • Jack Henry
  • Temenos
  • Thought Machine
  • Mambu

Payment rails

  • ACH
  • Fedwire
  • RTP
  • FedNow
  • Visa
  • Mastercard

Card processing

Card processors and issuers via the core or partners

Identity and KYC

  • Alloy
  • Socure
  • Persona

Data aggregation

  • Plaid
  • MX
  • Finicity

Digital channels

Online banking providers and mobile SDKs

CRM

  • Salesforce Financial Services Cloud

Banking Compliance and Regulatory Expectations
for this product

Compliance for banking software development covers GLBA Safeguards and privacy rules, FFIEC IT Examination Handbook guidance, Interagency Guidance on Third-Party Relationships (June 2023), BSA/AML and CIP, Regulation E and Regulation CC, ADA and WCAG 2.1 AA, PCI DSS v4.0.1. Each control is built into the software, and the product keeps the evidence a reviewer can ask for later.

Banking Compliance and Regulatory Expectations for this product
RequirementApplies toHow we build for it
GLBA Safeguards and privacy rulesCustomer informationEncryption, access control, monitoring and privacy notices
FFIEC IT Examination Handbook guidanceBank IT systemsDocumentation, change management, resilience and authentication controls examiners expect
Interagency Guidance on Third-Party Relationships (June 2023)Banks using vendors and fintech partnersVendor documentation, SOC reports from providers, monitoring and exit plans
BSA/AML and CIPAccount opening and monitoringKYC, CDD, beneficial ownership and alert workflows. RegTech compliance software
Regulation E and Regulation CCElectronic transfers and funds availabilityDispute workflows and availability schedules
ADA and WCAG 2.1 AADigital channelsAccessible design and testing
PCI DSS v4.0.1Card dataTokenisation and scope reduction

General information, not legal advice. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
AI in Banking Software
for this product

AI in banking software development covers Member service assistant, Fraud and scam detection, BSA alert triage, Staff co-pilot, Deposit insights. The model scores or drafts, a person can still review the result, and the product keeps a record of what happened.

AI in Banking Software for this product
AI featureWhat it doesHuman control
Member service assistantAnswers questions from policies and account dataEscalates money issues to staff
Fraud and scam detectionFlags unusual payments and account takeoverAnalyst review. AI fraud detection
BSA alert triageSummarises alerts and gathers contextInvestigator decides and files
Staff co-pilotDrafts responses and proceduresStaff approve before sending
Deposit insightsPredicts attrition and next-best productsModel risk management under SR 11-7

Showcasing published work and
fintech excellence from shipped products

These are published case studies that include money movement, orders or billing. Seed2Sell covers a B2B marketplace with payment and OTP checks. Narsik Logistics covers freight booking and tracking. A payments, wallet or lending case study will be added here when it is published.

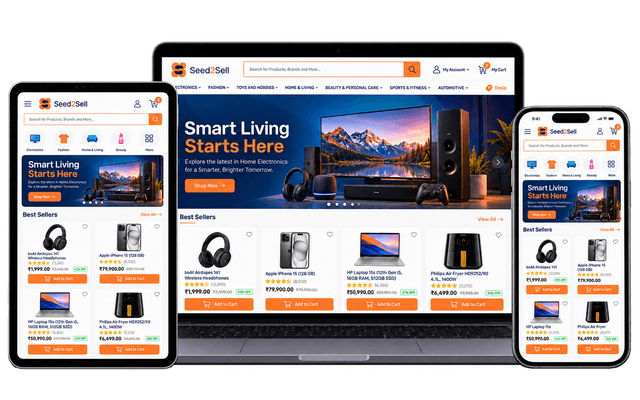
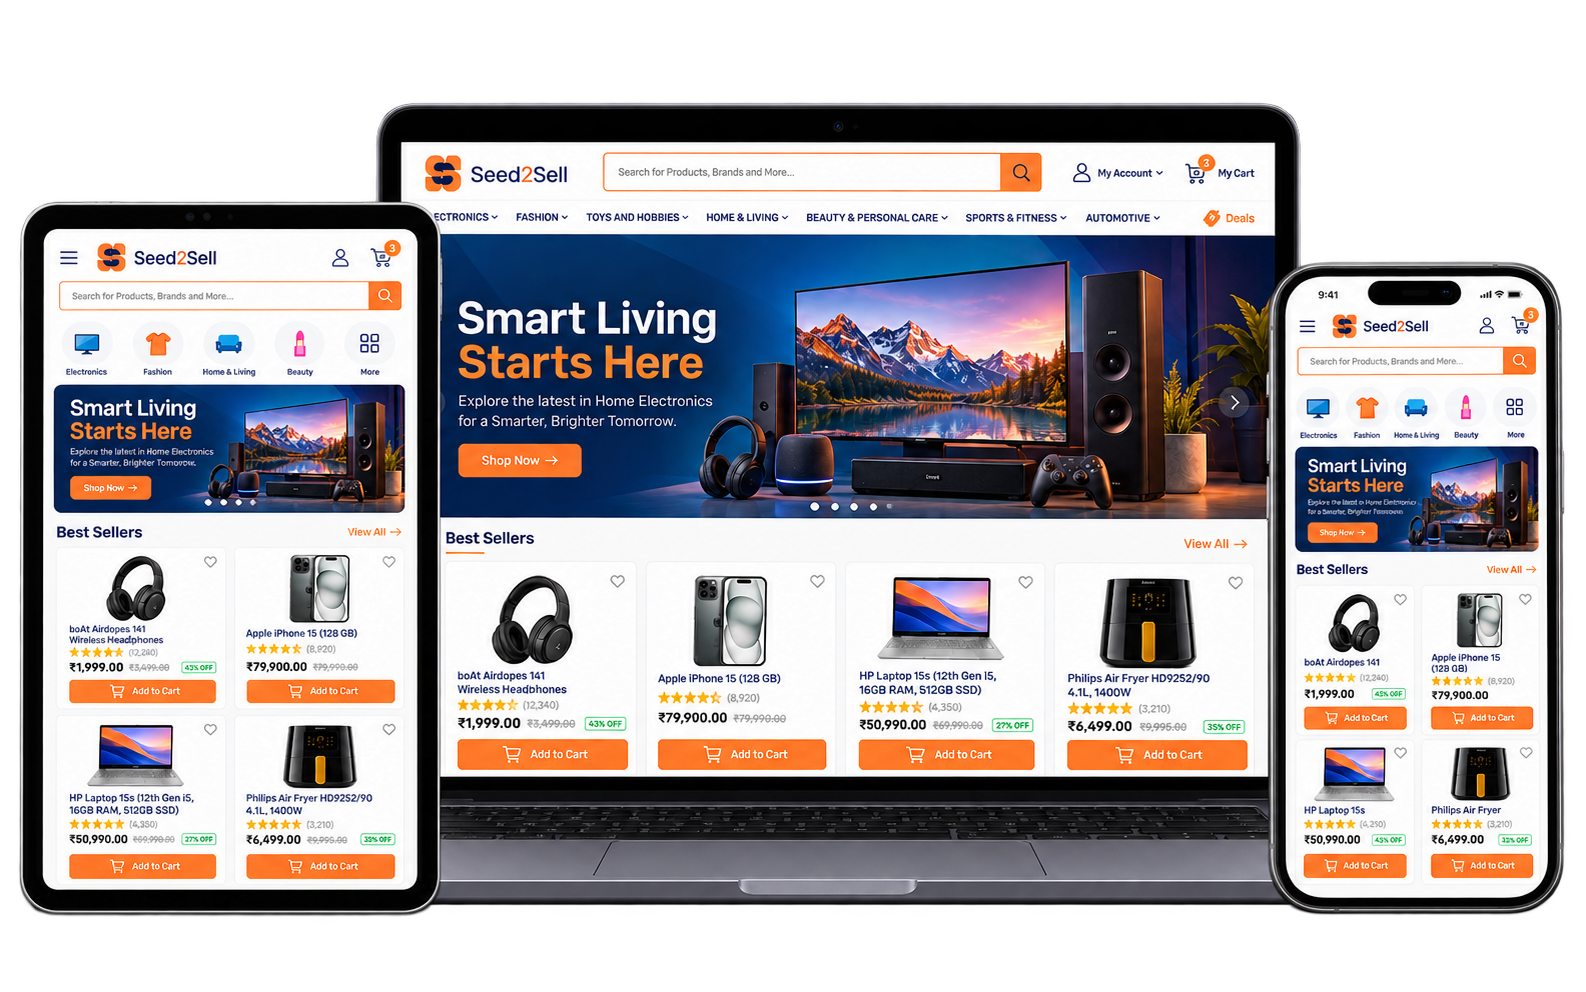
Seed2Sell marketplace home

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

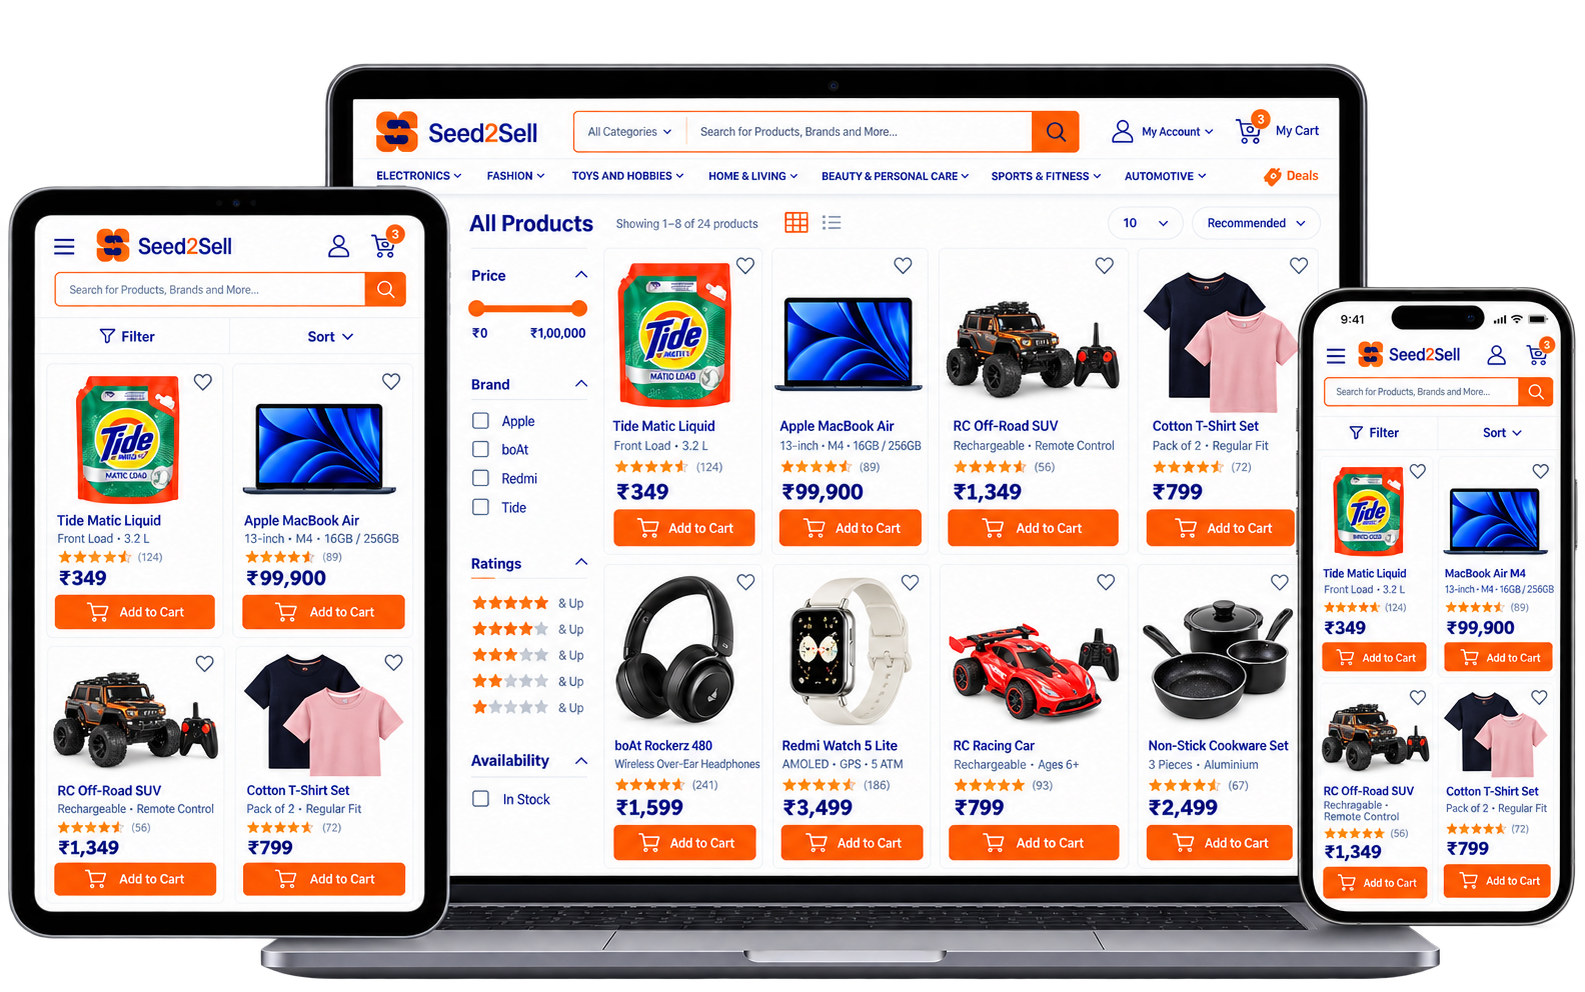
Seed2Sell product list

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

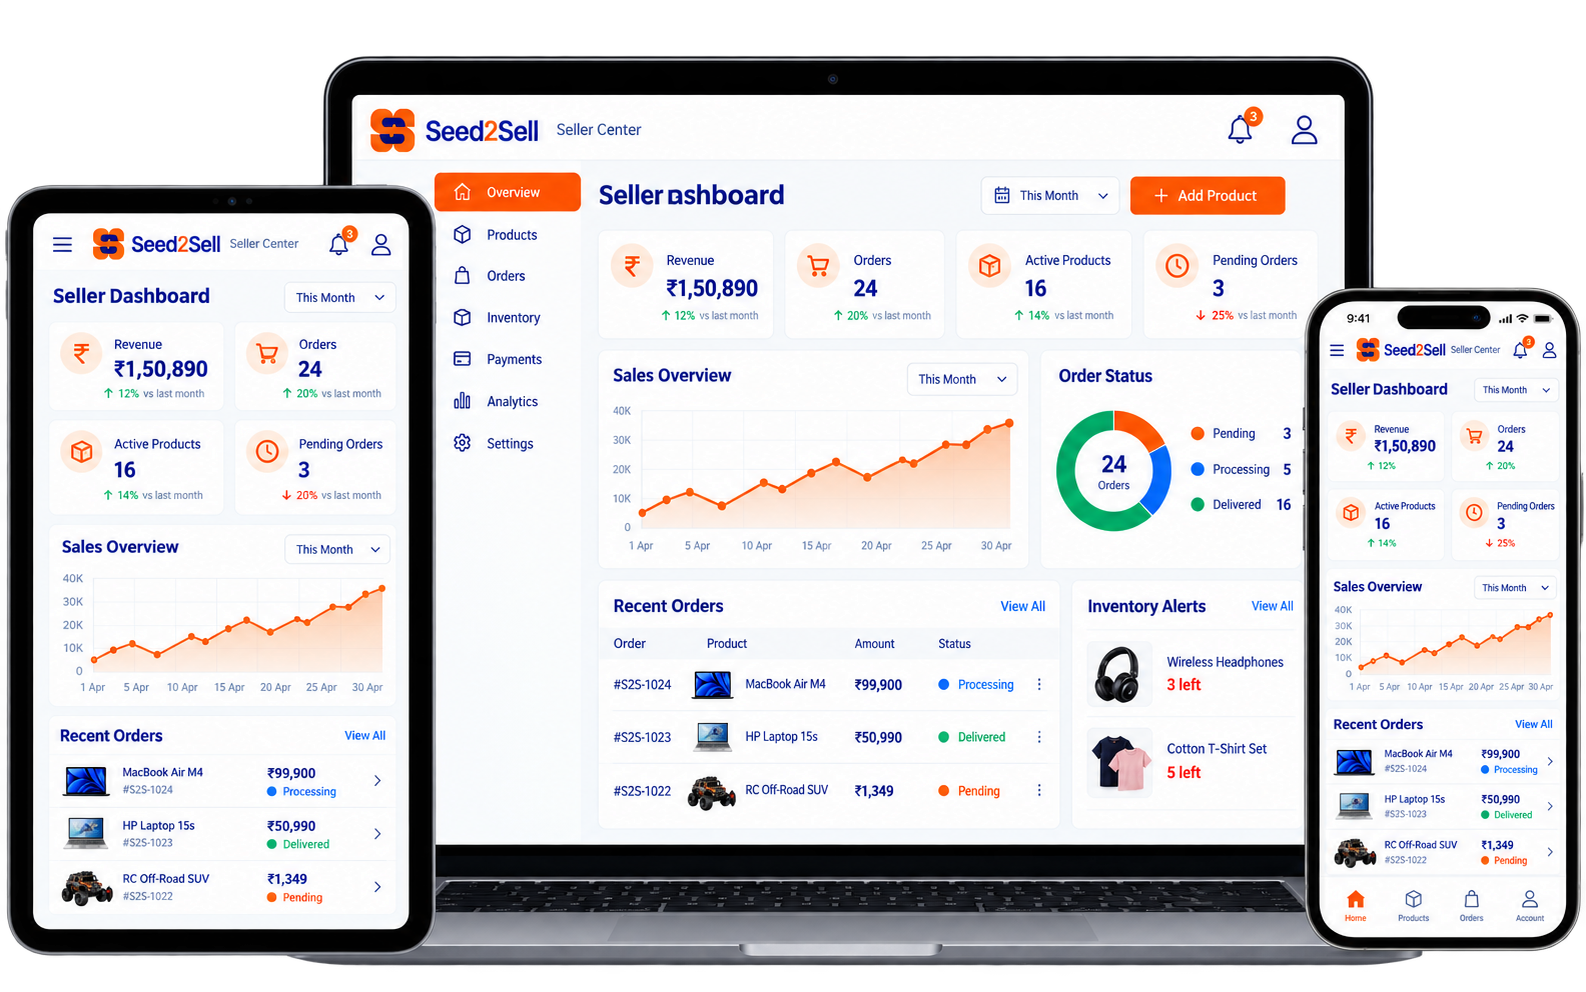
Seed2Sell seller dashboard

Seed2Sell

A B2B bulk marketplace with live bidding, orders and three role-based dashboards. Buyers, sellers and admins work from one system, including payment and OTP checks, so the order and the payment stay in the same product.

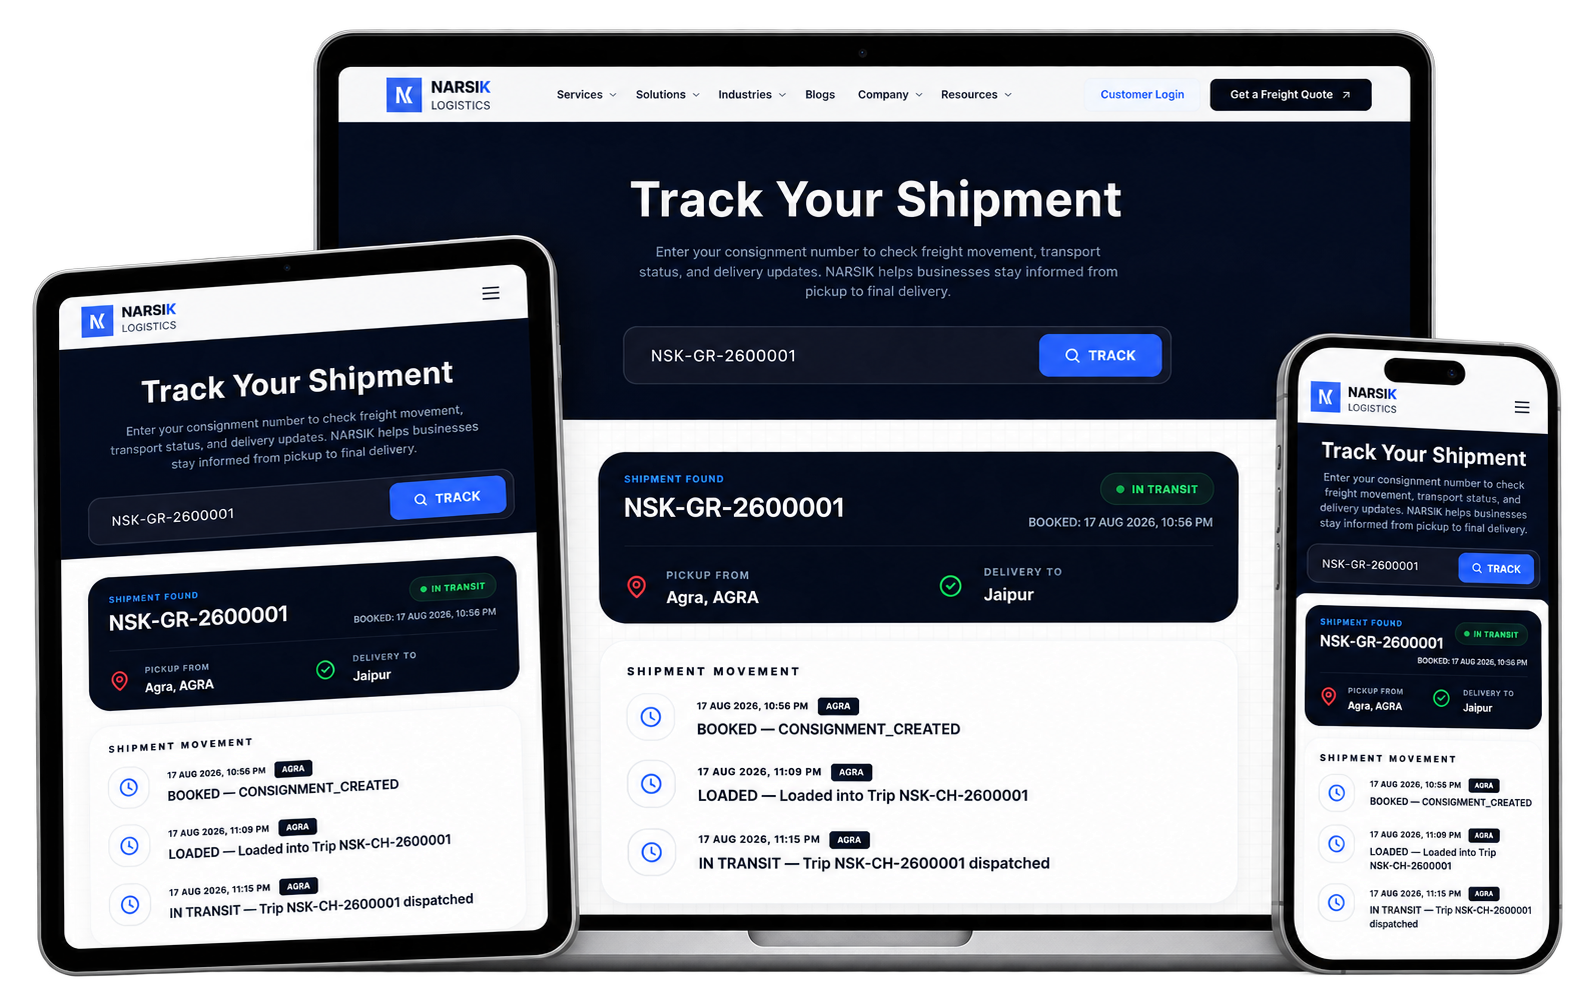
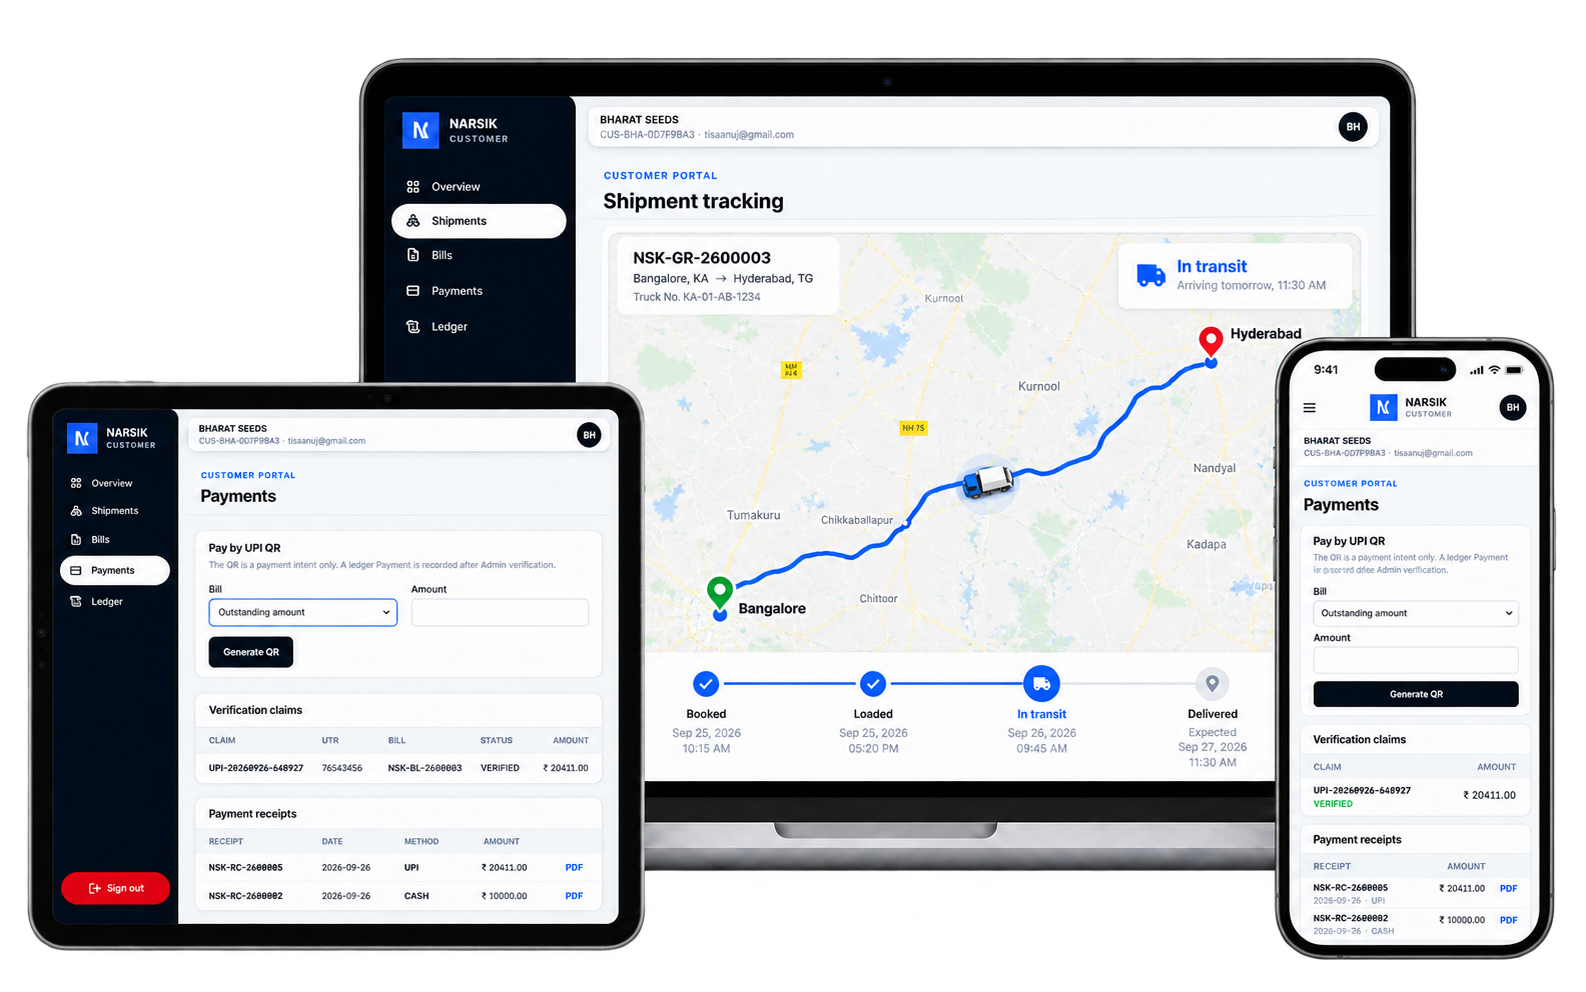
Narsik Logistics shipment tracking

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Narsik Logistics customer portal

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

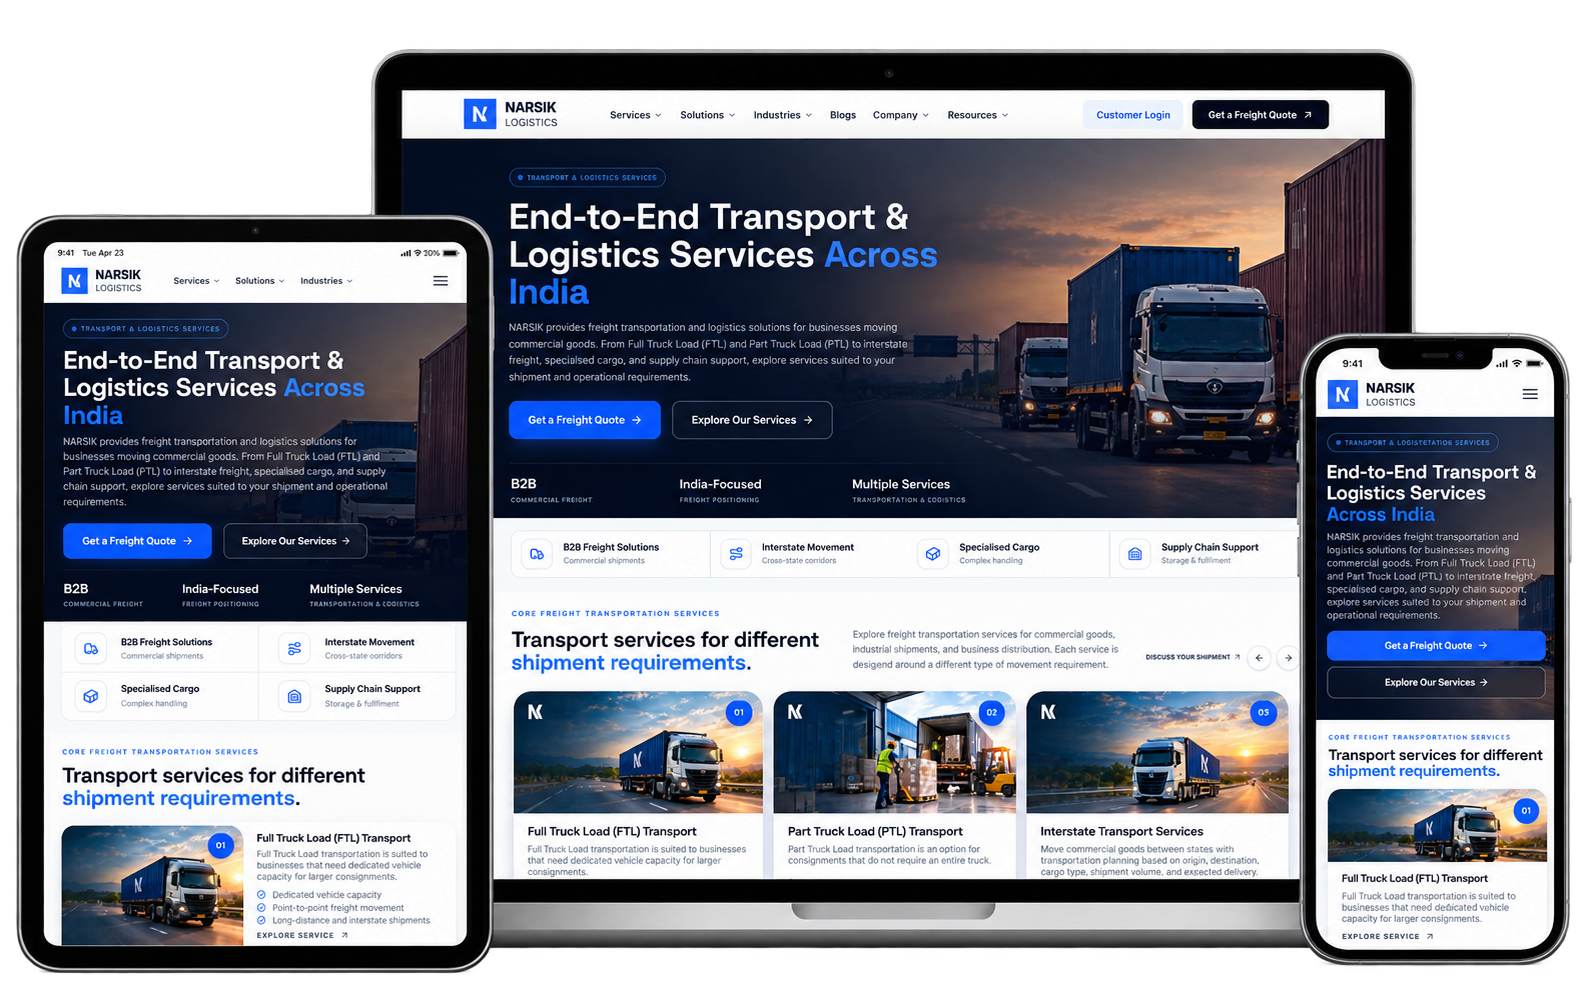
Narsik Logistics services

Narsik Logistics

A B2B freight booking platform with quotations, transportation bookings, shipment tracking and consignment details, so a customer can follow a shipment from the first quote all the way through to delivery.

Explore all case studies

How Much Does Banking
Software Development Cost?

Banking software development costs $100,000 to $500,000+. Core integration, security reviews and staged migration drive the cost. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.

How Much Does Banking Software Development Cost?
ProductCost (USD)Timeline
Banking softwareDigital account opening150,000
3–5 monthsMobile and online banking on existing core300,000
4–8 monthsBusiness banking portal280,000
5–8 monthsBaaS programme platform for a sponsor bank500,000
6–12 monthsCore migration programme$500,000+

Banking Software Development Process
for this product

The banking software development build moves through 1. Discovery with IT, operations, compliance and vendor management, 2. Core and integration assessment, Third-party risk package, 4. Phase plan with measurable outcomes, 5. Build, test and parallel run, 6. Staged rollout with member communication, 7. Ongoing support and release management. Each step ends with a written outcome and a handoff, so the next step starts from an agreed scope.

  1. 01

    Discovery with IT, operations, compliance and vendor management

  2. 02

    Core and integration assessment

  3. 03

    Third-party risk package

    security documentation, architecture and data flows. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
  4. 04

    Phase plan with measurable outcomes

  5. 05

    Build, test and parallel run

  6. 06

    Staged rollout with member communication

  7. 07

    Ongoing support and release management

These stages sit inside the studio software development process. The chart is the order for this product. The linked page explains how a build moves from discovery through release and handover.

See the development process

Tech Stack we use
for this product

Java, Kotlin, .NET, Node.js · Kafka, API gateways · PostgreSQL, SQL Server · Swift, Kotlin, React · AWS, Azure · ISO 20022, FDX APIs. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Java
Kotlin
.NET
Node.js
PostgreSQL
Swift
React
AWS
Azure

Why Choose THE TISA for
Banking Software Development

Teams hire THE TISA for banking software development because one team owns the product, the integrations and the evidence. You receive the code, the records and a launch handover when the build is done.

  • Progressive modernisation that delivers value without big-bang risk
  • Third-party risk ready: documentation your vendor management team needs
  • Core integration experience
  • Accessible, member-friendly UX
  • Transparent pricing and US-hour collaboration

Related Fintech Services
for this product

Pages related to banking software development include Neobank app development, Fintech API integration. Open the one that matches the next part of the product, or return to the fintech hub for the full list.

Neobank and Banking-as-a-Service Apps

Accounts, debit cards and transfers launched on a sponsor bank through a banking-as-a-service partner, without building a bank from scratch. Your partner holds the licence. We build the software that sits on it.

Explore Service

Fintech API Integration

Reliable connections to banks, processors, KYC vendors, open banking APIs and accounting systems, with retries, monitoring and a daily reconciliation against the ledger.

Explore Service

fintech software development services

What they say about working with THE TISA

The Seed2Sell team, and other founders we have shipped with, on the work itself. These notes come from published case studies and from founders whose products we built, not from a rating we have not verified.

We really appreciate the TISA team. They are hardworking, committed, and clear about our needs. They built a platform that works well today and will grow with us in the future.

THE TISA demonstrated excellent project management, clear communication, and a highly professional approach throughout our collaboration. They delivered the project on time and exceeded our expectations with outstanding results.

Parmeshwar Kumawat

Founder & CEO, NARSIK Logistics

Parmeshwar Kumawat

THE TISA helped us build a reliable e-commerce operations platform with clean workflows, strong delivery, and a product foundation ready to scale.

Sam Patel

Founder, EZSKU

Sam Patel

The student portal gave us a structured platform to manage learning, operations, reporting, and AI-powered student support from one system.

Albert Joe

Product Owner, Education Technology Platform

Albert Joe

THE TISA delivered a scalable hotel platform with strong architecture, complex backend logic, and a performance-focused execution process.

Luke Thompson

Founder, Group Hotel Index

Luke Thompson

The platform helped us shape a modern multilingual learning experience with a clear product structure and dependable technical execution.

Abdul Aziz Sudais

Director, Global Language Center

Abdul Aziz Sudais

More of the same work is written up in the case studies, and the public reviews sit on Clutch and GoodFirms.

Frequently asked questions about
this fintech service

Answers on cost, timelines, licences and compliance for banking software development. The same questions and answers are in the page text and in the structured data, so a reader can find them without opening the accordion.

Banking software costs $100,000 to $500,000+. Digital banking on an existing core costs 300,000. Core migrations cost $500,000 or more. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We build through the core provider's APIs and integration programmes, with an event and caching layer that protects core performance. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Usually not first. Most banks gain faster results by modernising digital channels and APIs, then moving products to a modern core in stages. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.

We provide security documentation, data flow diagrams, access controls, testing evidence and exit plans that align with the 2023 interagency guidance. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We build consumer and business account opening with KYC, KYB, funding and e-signature in under ten minutes. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We build member-focused digital banking, account opening and member service tools. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We integrate FedNow and RTP through your core or payment provider, with real-time status in digital channels. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Digital account opening takes 3–5 months. Full digital banking takes 4–8 months. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We build partner onboarding, FBO ledgers, oversight dashboards and compliance reports. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Yes. We design and test for WCAG 2.1 AA. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Plan your next build with our team

Plan Your Banking Modernisation Tell us your core, products and goals. We reply within one business day with a phased plan and cost range. We include this in the product scope, connect it to the systems around it, and leave the records, access and handover your team needs before the first release goes live.
Explore our work across 10 capability areas, from AI integrations and intelligent agents to web platforms, mobile apps, SaaS products, and cloud solutions. 20 projects are published as case studies.
50+Team Members
100+Projects Delivered
40+Happy Clients
12+Industries Served
30+Technologies
10+Countries Reached
20+Technical Specialists
35+AI Projects
25+Products Launched
20Published Case Studies

Share your scope

Tell us about the workflow or product. A solutions architect replies within one business day.

6 + 2 =